


EN
Exponent (EXPO) Could Be 11% Undervalued As Earnings And Guidance Rise
Exponent (EXPO) just combined a busy earnings day with a dividend update. The consultancy reported higher Q3 2026 revenue and profit, raised full year guidance, and confirmed another quarterly cash payout.
That backdrop has come through in the chart too, with Exponent’s share price up 19.26% over the past month and 17.56% across 90 days, while the 1 year total shareholder return of 15.39% contrasts with a 5 year total shareholder return that is still down 27.62%. This suggests improving momentum after a tougher longer stretch.
Scan other consulting and AI beneficiaries showing similar earnings momentum to Exponent by running through the hand picked 39 AI small caps.
The question now is whether Exponent’s latest jump reflects investors finally catching up with the underlying earnings and AI work, or whether sentiment has simply sprinted ahead of what the current valuation supports.
Most Popular Narrative: 11% Undervalued
On the most followed view of Exponent, the fair value sits at $90.67 compared with the latest close of $80.26. This view puts fresh earnings strength and AI related work at the center of the story, while using a 7.48% discount rate to bridge today's price to those future cash flows.
The capital light consulting model, with 2026 capex guided to only US$12 million to US$14 million and management expecting over US$100 million of free cash flow in the second half of 2026 after already returning US$272 million to shareholders over the prior 12 months, gives Exponent scope to continue dividends and buybacks while still funding growth initiatives. This can influence per share earnings and support net margin resilience.
See why 6 investors see Exponent as 11% undervalued.
Result: Fair Value of $90.67 (UNDERVALUED)
Still, two pressure points could challenge that 11% undervalued story for Exponent if costs remain elevated and clients rely more on automated AI tools.
Find out about the key risks to this Exponent narrative.
Another View On Exponent’s Valuation
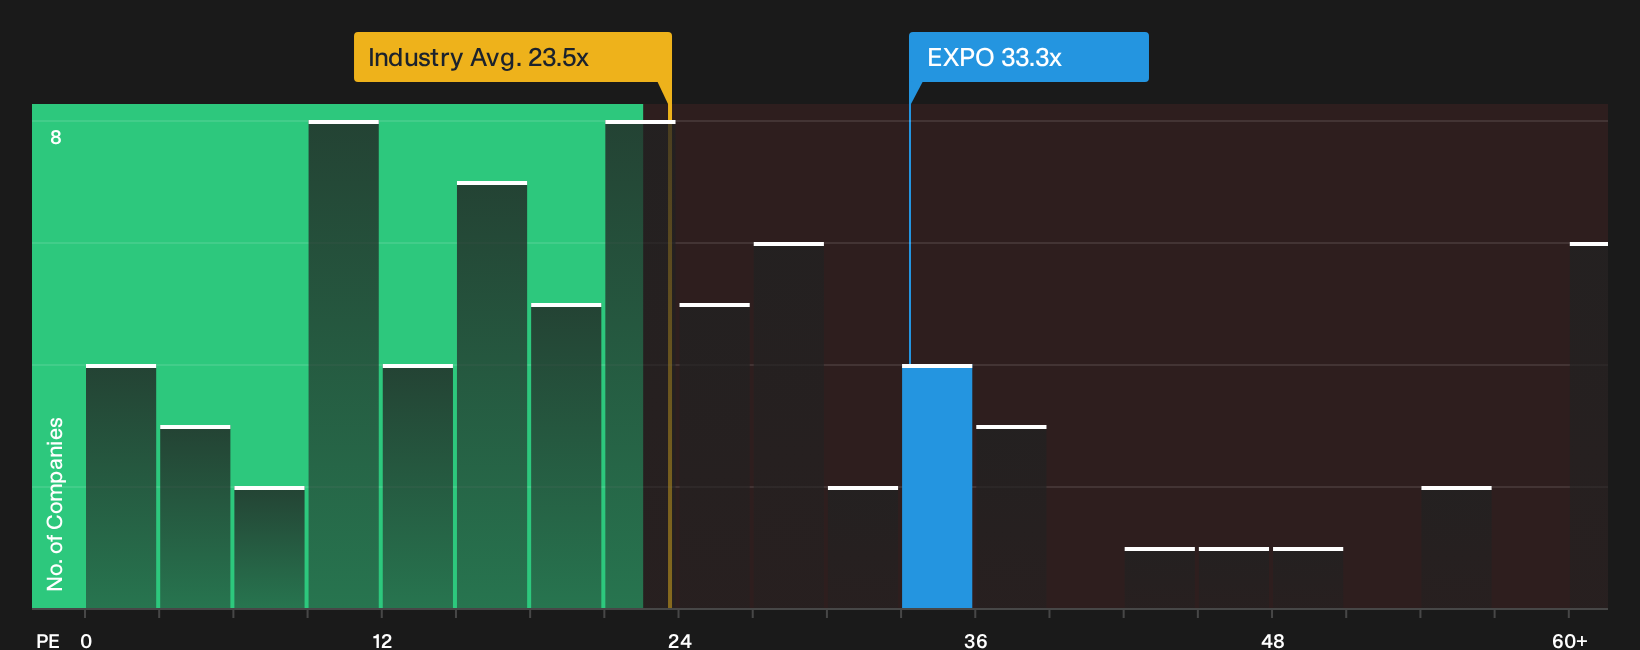
There is a catch in the Exponent story. On earnings based measures, the stock trades on a P/E of 33.3x, which is higher than the US Professional Services industry at 22.5x, peers at 23.4x, and even the fair ratio estimate of 18.5x. That gap points to valuation risk rather than a clear bargain. The key question is how much of that premium you are really comfortable paying for this quality profile.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Recent moves around Exponent have sparked plenty of debate, so it makes sense to pull up the numbers yourself and pressure test the bullish angles. To see exactly which potential upsides investors are focused on, and then decide how that fits your own view, check the 4 key rewards.
Looking for more Exponent sized ideas?
If Exponent has sharpened your thinking on quality and price, do not stop here. Broaden your watchlist now with a few targeted stock shortlists.
- Target resilient upside by scanning a curated pool of quality companies trading below fair value through the 33 high quality undervalued stocks.
- Strengthen your income stream by zeroing in on companies with robust payouts and balance sheets using the 5 dividend fortresses.
- Reduce portfolio shock by focusing on businesses with stronger financial footing and cleaner fundamentals via the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com