


EN
Will Raised Guidance Change OBIC Business Consultants Stock Narrative
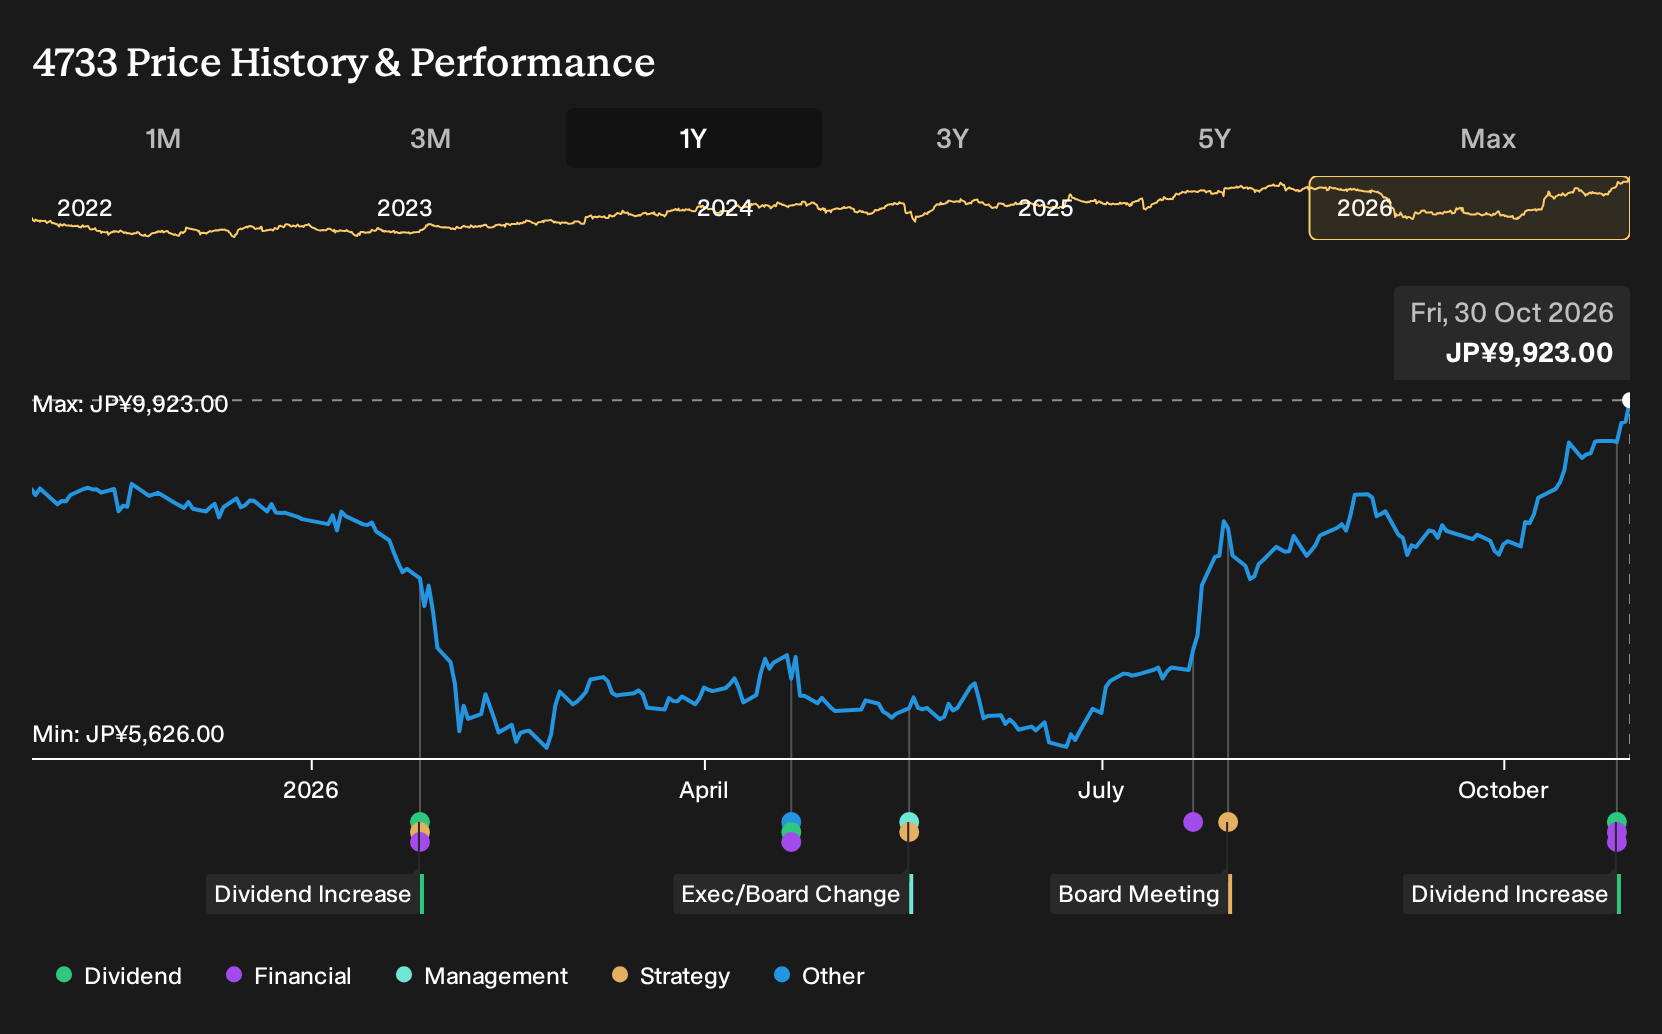
- OBIC Business Consultants announced a cash dividend of ¥65.00 per share for the year ending March 31, 2027, raised full-year earnings guidance, and reported half-year sales of ¥28,666.7 million with net income of ¥10,135.05 million and basic EPS of ¥134.82.
- The higher dividend and upgraded profit outlook are grounded in stronger than expected demand for OBIC Business Consultants' cloud and AI driven services, which management cites as key drivers of the revised sales and earnings forecasts.
- Now attention turns to how OBIC Business Consultants' upgraded earnings guidance, underpinned by its cloud and AI focus, may influence the broader investment narrative.
Scan beyond OBIC Business Consultants and see how other AI focused software firms with rising earnings and shareholder payouts line up in our hand picked 16 high quality undervalued stocks.
What Is OBIC Business Consultants' Investment Narrative?
To own OBIC Business Consultants, you need to be comfortable with a fairly simple story. This is a mature software producer that leans on accounting, HR and payroll packages, then layers on cloud delivery and AI tools to keep demand healthy and pricing power intact. The raised guidance and higher dividend fit that picture. Recent half year sales of ¥28,666.7 million and net income of ¥10,135.05 million show that the current execution around cloud security and AI features is feeding through to earnings.
In the short term, the raised outlook and ¥65.00 dividend support the idea that OBIC Business Consultants can fund shareholder returns while investing in its own infrastructure, which tends not to be hugely capital intensive compared with hardware heavy sectors. The trade off is valuation and expectations. The stock carries a P/E of 37.3x against 17.7x for the wider JP software group, and shares have already climbed 21.9% over the past month, so any stumble on demand, pricing or AI adoption could matter more than usual.
Yet there is a less comfortable angle to this story if ...
There's only one way to know the right time to buy, sell or hold OBIC Business Consultants. Head to Simply Wall St's company report for the latest analysis of OBIC Business Consultants's Fair Value.
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your OBIC Business Consultants research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for OBIC Business Consultants. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate OBIC Business Consultants' overall financial health at a glance.
Looking For More Investment Ideas Beyond OBIC Business Consultants?
If OBIC Business Consultants has sharpened your focus on quality, earnings power and shareholder returns, it can be useful to widen the lens and see how other listed companies stack up on similar traits using the Simply Wall St Screener.
- For investors who want income that looks more durable, scan a curated field of companies offering higher yields and stronger coverage using our 28 dividend fortresses.
- If capital protection matters most to you, filter for businesses with sturdier finances and cleaner balance sheets through this list of solid balance sheet and fundamentals (21 results).
- When you are hunting for potential future leaders that are still off most radars, start with this hand picked 69 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com