


EN
Seacoast Banking Corporation Of Florida (SBCF) Raises Dividends, Is The Stock Still Cheap?
Seacoast Banking Corporation of Florida (SBCF) just put three signals on the table at once: higher quarterly net charge offs, a completed share repurchase plan, and a bigger dividend on both common and preferred stock.
Seacoast Banking Corporation of Florida’s share price has moved sideways overall in recent months, with a 30 day share price return of 1.07% and a 90 day decline of 5.39%. This suggests momentum has cooled even as the latest dividend hike and completed buyback keep total shareholder return supported, with a 1 year total shareholder return of 11.62% and a 3 year total shareholder return of 55.20% contrasting with a slightly negative 5 year total shareholder return of 1.03%.
Scan how Seacoast Banking Corporation of Florida compares with other income focused financials by reviewing our hand picked 5 dividend fortresses.
Seacoast Banking Corporation of Florida now trades close to analyst targets, yet far from some intrinsic value estimates, after a modest drift in the share price and richer dividends. So where does fair value really sit in that spread?
Most Popular Narrative: 11% Undervalued
On the main narrative, Seacoast Banking Corporation of Florida screens as undervalued, with a fair value estimate of $37.04 against a last close of $33.03. That gap rests on a detailed view of balance sheet strength, fee income growth, and how acquired platforms can be used over time.
A self described fortress balance sheet that includes Tier 1 capital ratios around 14% to 14.5%, tangible equity to tangible assets near 9.2% to 9.8%, and a loan to deposit ratio close to 75% provides room for Seacoast Banking Corporation of Florida to fund loan growth, pursue capital returns and support net interest margin and earnings.
See why 0 investors see Seacoast Banking Corporation of Florida as 11% undervalued.
Result: Fair Value of $37.04 (UNDERVALUED)
Still, the Seacoast Banking Corporation of Florida story can be knocked off course if lending competition squeezes pricing, or if higher revenue fails to lift per share profitability.
Find out about the key risks to this Seacoast Banking Corporation of Florida narrative.
Another View: Seacoast Banking Corporation of Florida Looks Pricey On Earnings
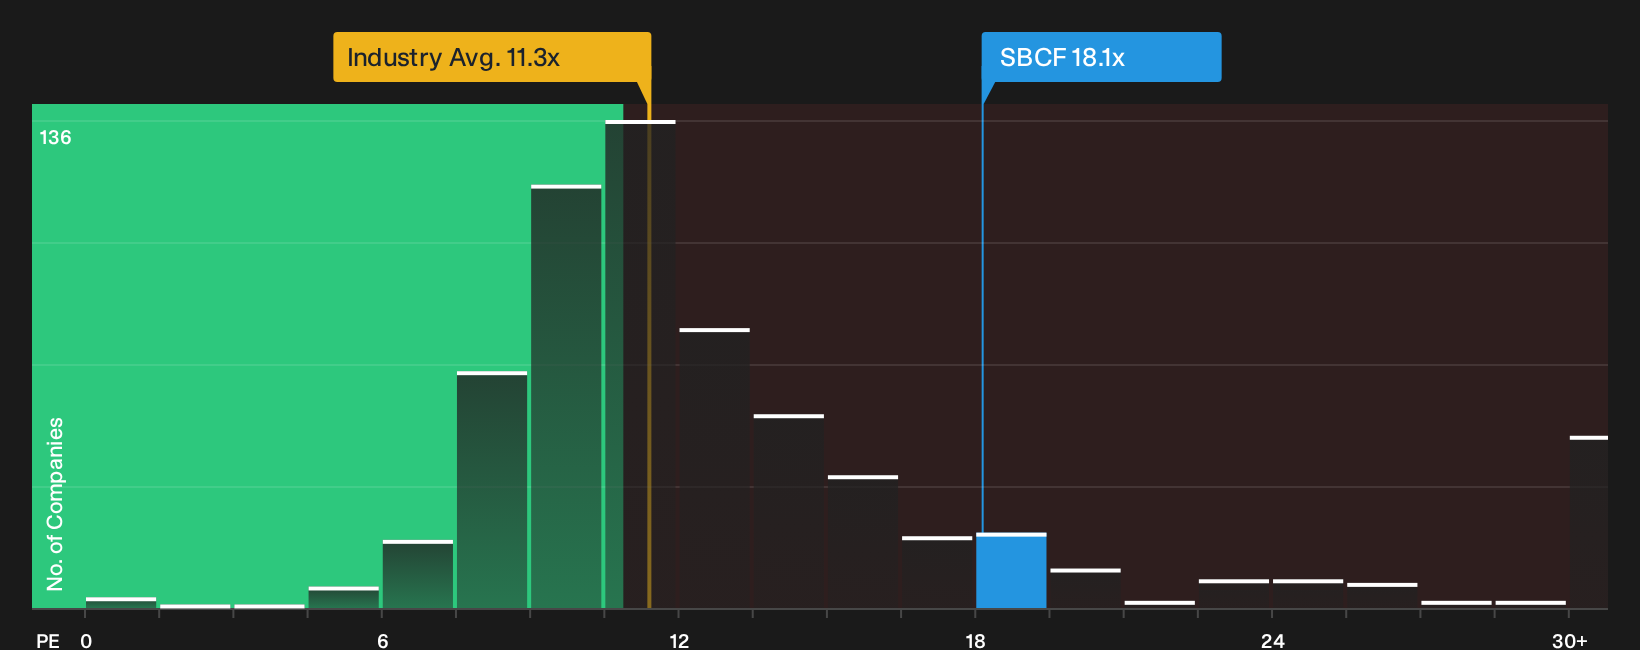
The first story presents Seacoast Banking Corporation of Florida as undervalued on fair value estimates. A simple earnings multiple offers a different perspective. The stock trades on a P/E of 18.1x, compared with a fair ratio of 15.2x, the US Banks average of 11.4x, and peer levels around 13x. That richer valuation suggests less margin for error if the growth narrative slows, so how comfortable are you paying a higher multiple for this kind of bank exposure?
Before relying too heavily on any single metric, it is worth checking how this earnings-based view aligns with our broader valuation work, including the detailed fair ratio framework and peer checks in the See what the numbers say about this price — find out in our valuation breakdown..
For a clearer sense of how Seacoast Banking Corporation of Florida compares on valuation with the wider sector on this measure, review the latest comparison in
Next Steps
Sentiment across these valuation angles on Seacoast Banking Corporation of Florida is mixed, so treat this as a starting point and move fast to form your own stance using the detailed breakdown in 2 key rewards.
Looking for more Seacoast Banking Corporation of Florida style investment ideas?
If Seacoast Banking Corporation of Florida has you thinking harder about valuation and income, do not stop with just one ticker. Broaden your watchlist with a few focused idea lists that surface very different types of opportunities.
- Target potential mispricings early and sift through companies that combine quality with attractive entry points using the 33 high quality undervalued stocks.
- Prioritise resilience by checking businesses that pair sturdy finances with measured risk profiles through the 29 resilient stocks with low risk scores.
- Hunt for future leaders before the crowd by scanning the 19 high quality undiscovered gems that already show strong underlying fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com