


EN
Is Boot Barn Holdings (BOOT) Undervalued After Its 75 To 80 Store Expansion Plan?
What the store expansion and guidance update signal for Boot Barn Holdings
Boot Barn Holdings (BOOT) has put a clear marker down for fiscal 2027. Management plans to open 75 to 80 new stores and has paired that rollout with updated earnings guidance.
The expansion plan arrives alongside fresh projections for the December 2026 quarter and the full fiscal year ending March 27, 2027. Investors now have a more detailed view of how the retailer expects sales, operating income and net income per diluted share to track against recent performance.
Recent trading shows how quickly sentiment around Boot Barn Holdings can pivot. The share price has climbed 14.8% over the past week and 8.5% over the past month, even though the year to date share price return is down 29.1% and the 1 year total shareholder return is down 30.3%. However, the 3 year total shareholder return of 75.7% points to a much stronger longer term journey.
Scan how Boot Barn Holdings stacks up against other retailers targeting growth through expansion with the hand picked 33 high quality undervalued stocks that combine balance sheet strength with earnings power.
After a near 15% jump in a week and fresh guidance on the table, Boot Barn Holdings now forces a simple question: Does the current price still compensate you for the expansion risk ahead?
Most Popular Narrative: 36% Undervalued
At a last close of $132.24 against a widely followed fair value estimate of about $207.87, the dominant narrative around Boot Barn Holdings argues that the market is still pricing the retailer below its projected earnings power.
The main thing that has to go right is that new stores, exclusive-brand penetration, digital channels and the work and B2B categories continue to generate attractive economics despite higher occupancy and distribution costs and pockets of softer Western demand.
See why 11 investors see Boot Barn Holdings as 36% undervalued.
Result: Fair Value of $207.87 (UNDERVALUED)
Still, the Boot Barn Holdings story frays quickly if aggressive store openings outpace demand or if softer Western categories linger and drag on same store sales.
Find out about the key risks to this Boot Barn Holdings narrative.
Another View: Boot Barn Holdings Through A Cash Flow Lens
The analyst narrative presents Boot Barn Holdings as 36% undervalued, yet the SWS DCF model points in the opposite direction. On an estimated future cash flow value of about $84.04 versus a $132.24 share price, the stock screens as overvalued. Which story do you think fits your own expectations better?
If you rely more on cash generation than headline earnings, it can be useful to see how the SWS DCF model is built and what assumptions sit underneath that $84.04 figure, before leaning too heavily on any single fair value number Look into how the SWS DCF model arrives at its fair value..
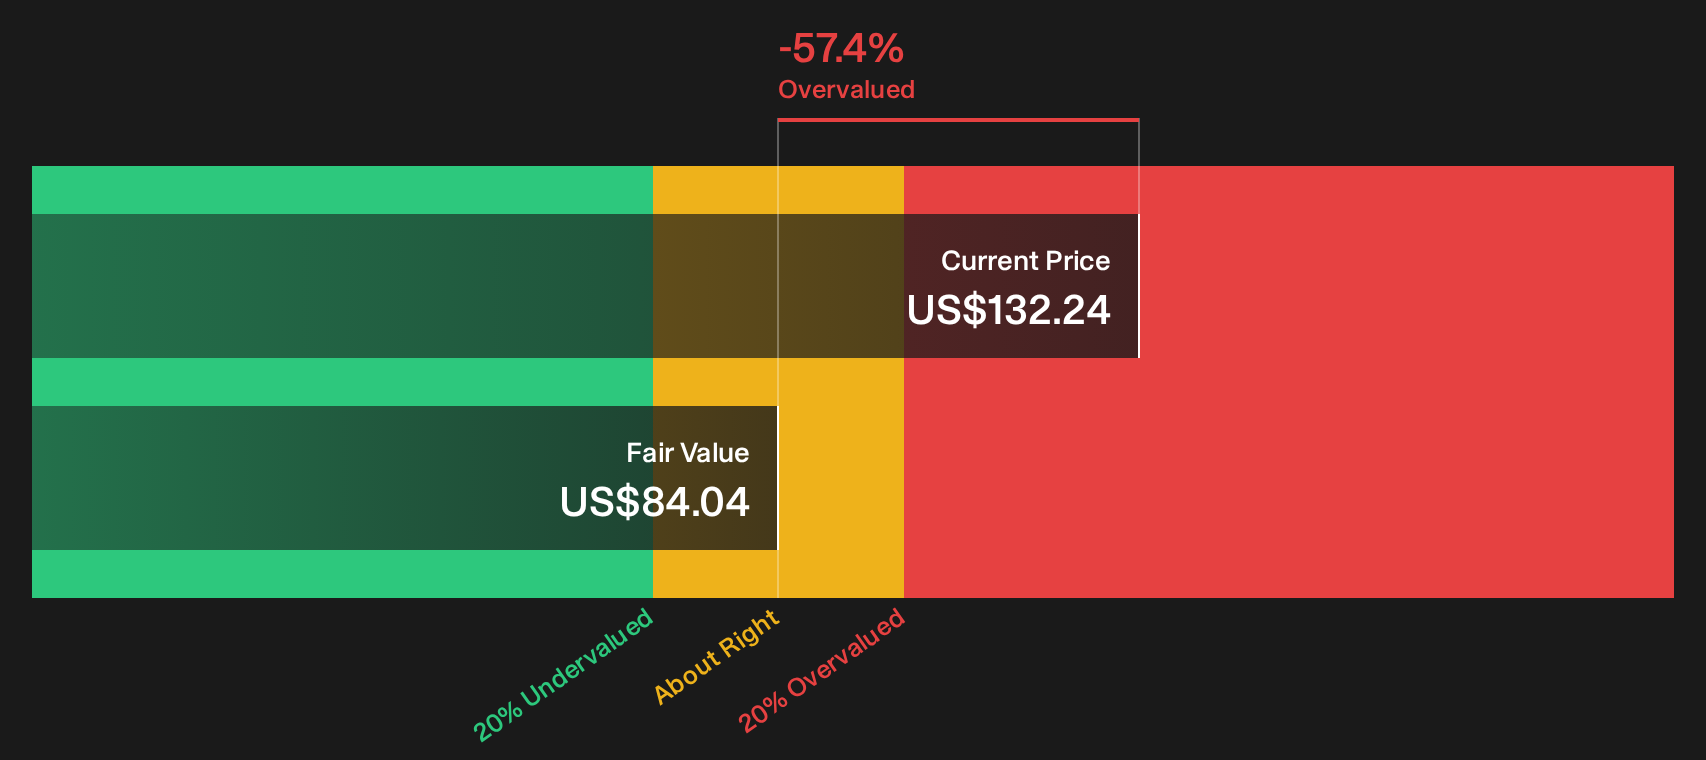
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Boot Barn Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Boot Barn Holdings is clearly split, which is exactly when doing your own work matters most. If you want to move quickly and stress test your view against what the data actually shows, start with the 3 key rewards.
Looking for more Boot Barn Holdings style investment ideas?
If you stop with just one stock, you miss the chance to compare Boot Barn Holdings against other opportunities that might suit your risk profile even better.
- Target steadier compounding by checking companies screened for stronger cash generation and attractive pricing through the 33 high quality undervalued stocks.
- Focus on resilience by reviewing businesses highlighted in the 29 resilient stocks with low risk scores that pair financial strength with lower historical risk scores.
- Hunt for potential future standouts by scanning the 19 high quality undiscovered gems that combine quality fundamentals with limited current attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com