


EN
Should Strong Earnings And Dividend Hike Require Action From 1st Source (SRCE) Investors?
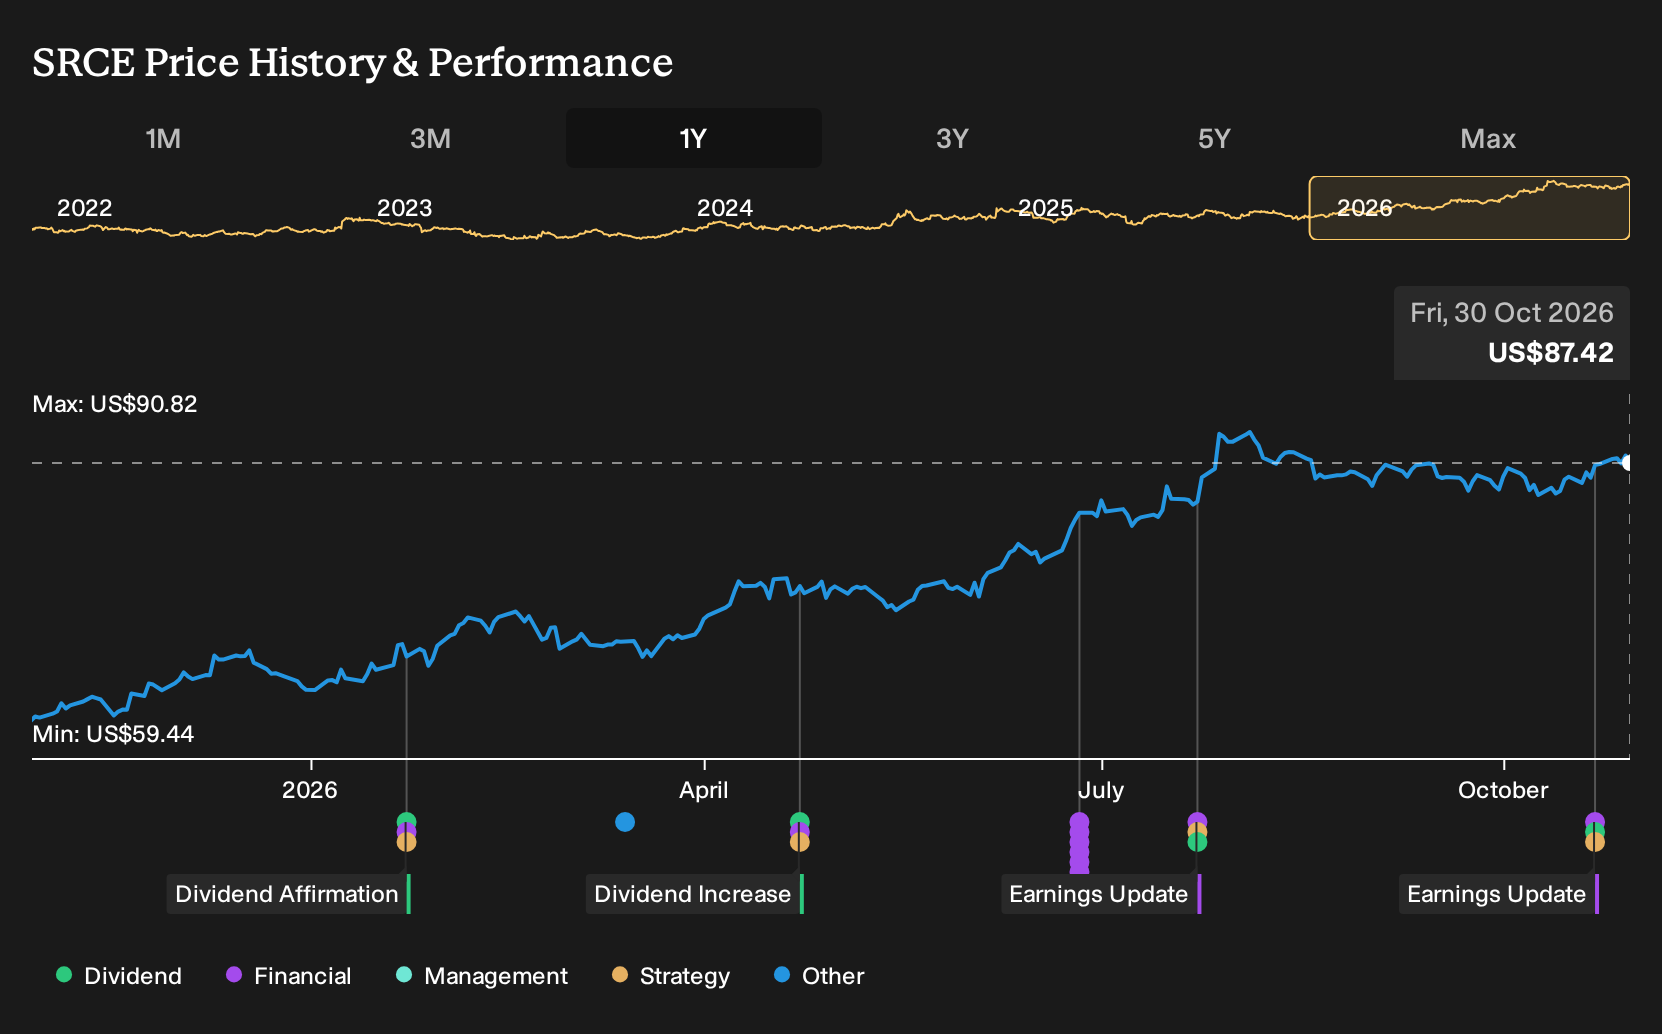
- 1st Source reported third quarter 2026 net interest income of US$95.59 million and net income of US$49.54 million, along with higher basic and diluted earnings per share from continuing operations compared with the same period a year earlier. The board approved a US$0.45 per share cash dividend for payment in November 2026.
- Beyond earnings, 1st Source also reported lower net charge offs of US$0.33 million for the third quarter of 2026 compared with US$1.88 million a year earlier, indicating improved credit outcomes alongside the dividend increase.
- Next, investors may consider how 1st Source's higher earnings per share relate to its investment narrative for long term shareholders.
What Is 1st Source's Investment Narrative?
For anyone considering 1st Source, the core belief is about a fairly traditional regional bank that relies on consistent lending demand, disciplined credit and steady fee income instead of big swings. The latest quarter, with higher net interest income and net income versus a year ago, supports that story of solid execution. A higher dividend and lower net charge offs point to a management team that currently feels comfortable with both earnings power and asset quality, which matters more for the near term than any headline on valuation.
Short term catalysts now sit around how well 1st Source can sustain this earnings run rate without leaning on outsized risk taking in loans or securities. The bank already trades on a P/E above some peers, while still screening as good value on some cash flow measures, so fresh financial results carry extra weight. That mix of rising dividend, high margins and forecast revenue and earnings growth that is not especially fast means you are essentially looking at stable operations and consistent credit discipline rather than rapid expansion.
Yet there is a quieter factor here that could matter more than the last quarter’s beat or the higher dividend...
There's only one way to know the right time to buy, sell or hold 1st Source. Head to Simply Wall St's company report for the latest analysis of 1st Source's Fair Value.
Exploring Other Perspectives
Fair value estimates for 1st Source from the Simply Wall St Community span two retail perspectives, from US$95 up to roughly US$135 per share. Those views were formed before the October 22 earnings release and dividend decision, so you are weighing community models against fresh profitability and credit data that could materially shift how you and others frame the story.
Explore another 1st Source fair value estimate, including one that suggests it could be worth just $95.00.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your 1st Source research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for 1st Source. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate 1st Source's overall financial health at a glance.
Looking For More Investment Ideas Beyond 1st Source?
If you want to cross check 1st Source against other opportunities, a quick scan of curated stock lists can help you spot businesses with similar or complementary qualities.
- For investors who care most about stability, start with companies that pair financial strength with low risk profiles by reviewing the 29 resilient stocks with low risk scores.
- If value is your priority, compare 1st Source with other attractively priced businesses that also have quality fundamentals through the 33 high quality undervalued stocks.
- Income focused investors can round out their watchlist by searching for high yield opportunities with robust balance sheets using the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com