


EN
Marqeta (MQ) Gains A Fresh Valuation Test As Square Credit Card Win Lifts The Story
Why the Square Credit Card deal matters for Marqeta
Marqeta (MQ) is back in focus after Square chose its platform to power the Square Credit Card, consolidate multiple card programs with a single processor, and broaden access to the American Express network.
Recent trading reflects that tension between excitement and caution. Marqeta’s 30 day share price return of 9.37% points to fresh momentum around the Square Credit Card news. However, the 1 year total shareholder return is roughly flat and the 5 year total shareholder return is down sharply, which shows long term holders are still waiting for a sustained turnaround.
Scan beyond Marqeta and this Square Credit Card headline by reviewing 19 high quality undiscovered gems that may be building similar payment infrastructure stories before they hit the mainstream.
Marqeta has climbed on the Square Credit Card news, yet long term returns remain deeply underwater. Is this move the early stage of a reset, or has most of the easy upside already been priced in?
Most Popular Narrative: 12% Undervalued
Marqeta’s most followed thesis pegs fair value at $20.65 compared with a last close of $18.10. This frames the Square Credit Card deal inside a wider argument that the platform is being priced below its long range potential.
The build out of a unified money movement and digital asset stack that includes ACH, real time payments, wires, push to card, and stablecoin backed card payments positions Marqeta to participate in new payment flows beyond traditional cards and to generate incremental fee and value added services income that can support gross profit growth and operating margin expansion.
See why 14 investors see Marqeta as 12% undervalued.
Result: Fair Value of $20.65 (UNDERVALUED)
Still, concentration in a few large customers and pressure on gross profit take rates could quickly challenge the Marqeta narrative if those trends worsen.
Find out about the key risks to this Marqeta narrative.
Another View: What Marqeta’s P/S Ratio Is Telling You
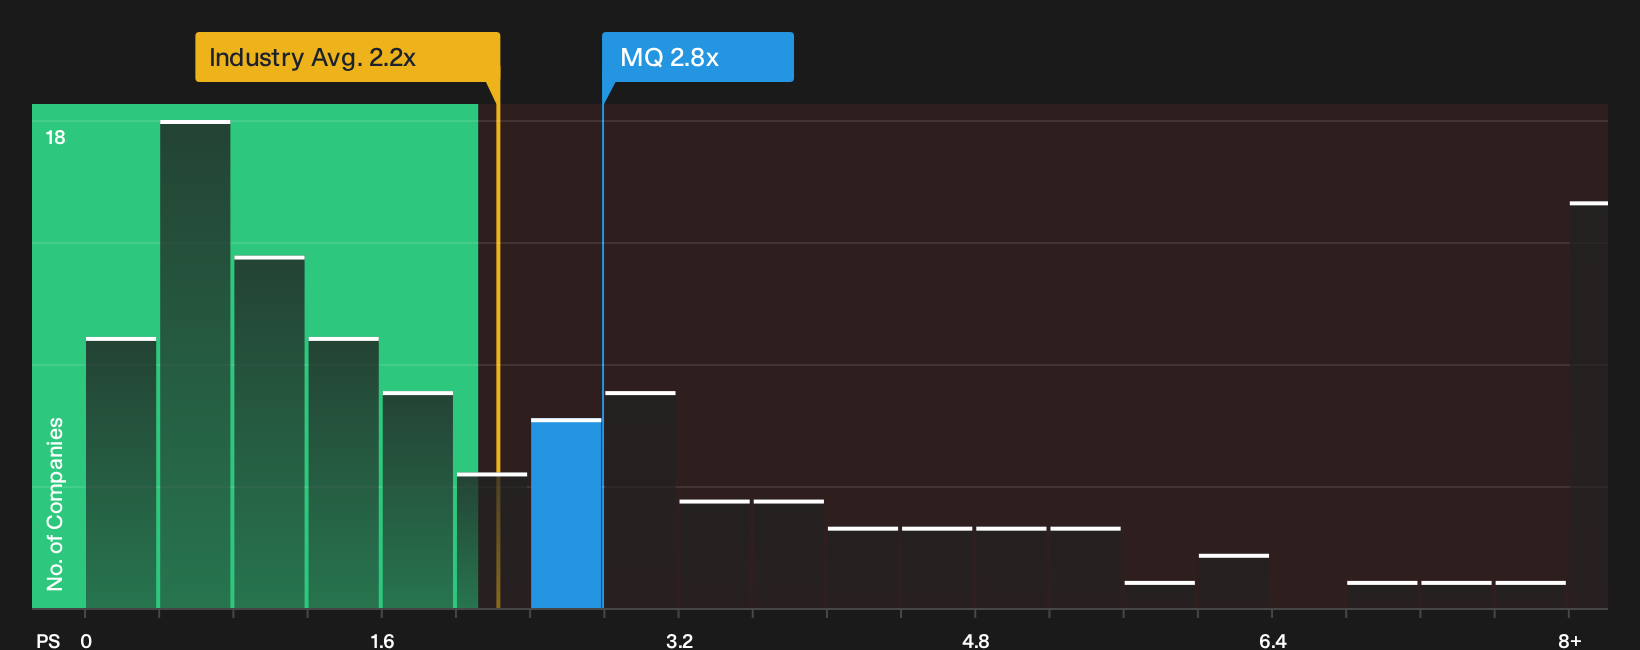
The first narrative leans on future earnings and analyst fair value. A simple P/S check paints a tougher picture. Marqeta trades around 2.8x sales, above the US Diversified Financial industry at 2.2x and well above peer levels near 0.8x, while the fair ratio is estimated at 2.1x.
That spread suggests investors are already paying a premium that could compress if sentiment cools. The key question is whether the Square Credit Card deal and broader platform story are strong enough for you to stay comfortable with that kind of valuation risk.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and concern around Marqeta feels familiar, treat it as a signal to check the numbers yourself and move quickly while sentiment is still forming. Then weigh those data points against the 2 key rewards.
Looking for more investment ideas beyond Marqeta?
Do not just stop at the Marqeta story. Use this momentum to broaden your watchlist while the market is still sorting through the latest payment headlines.
- Target stronger balance sheets by tracking companies on our list of solid balance sheet and fundamentals (24 results) that combine financial resilience with room for future execution.
- Hunt for mispriced opportunities through the 33 high quality undervalued stocks and see which businesses the numbers suggest may be trading below their fundamentals.
- Prioritise resilience by scanning the 29 resilient stocks with low risk scores and focus on companies that score well on stability when conditions get rough.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com