


EN
What The Bulls Got Wrong Before Evotec Fell 60%
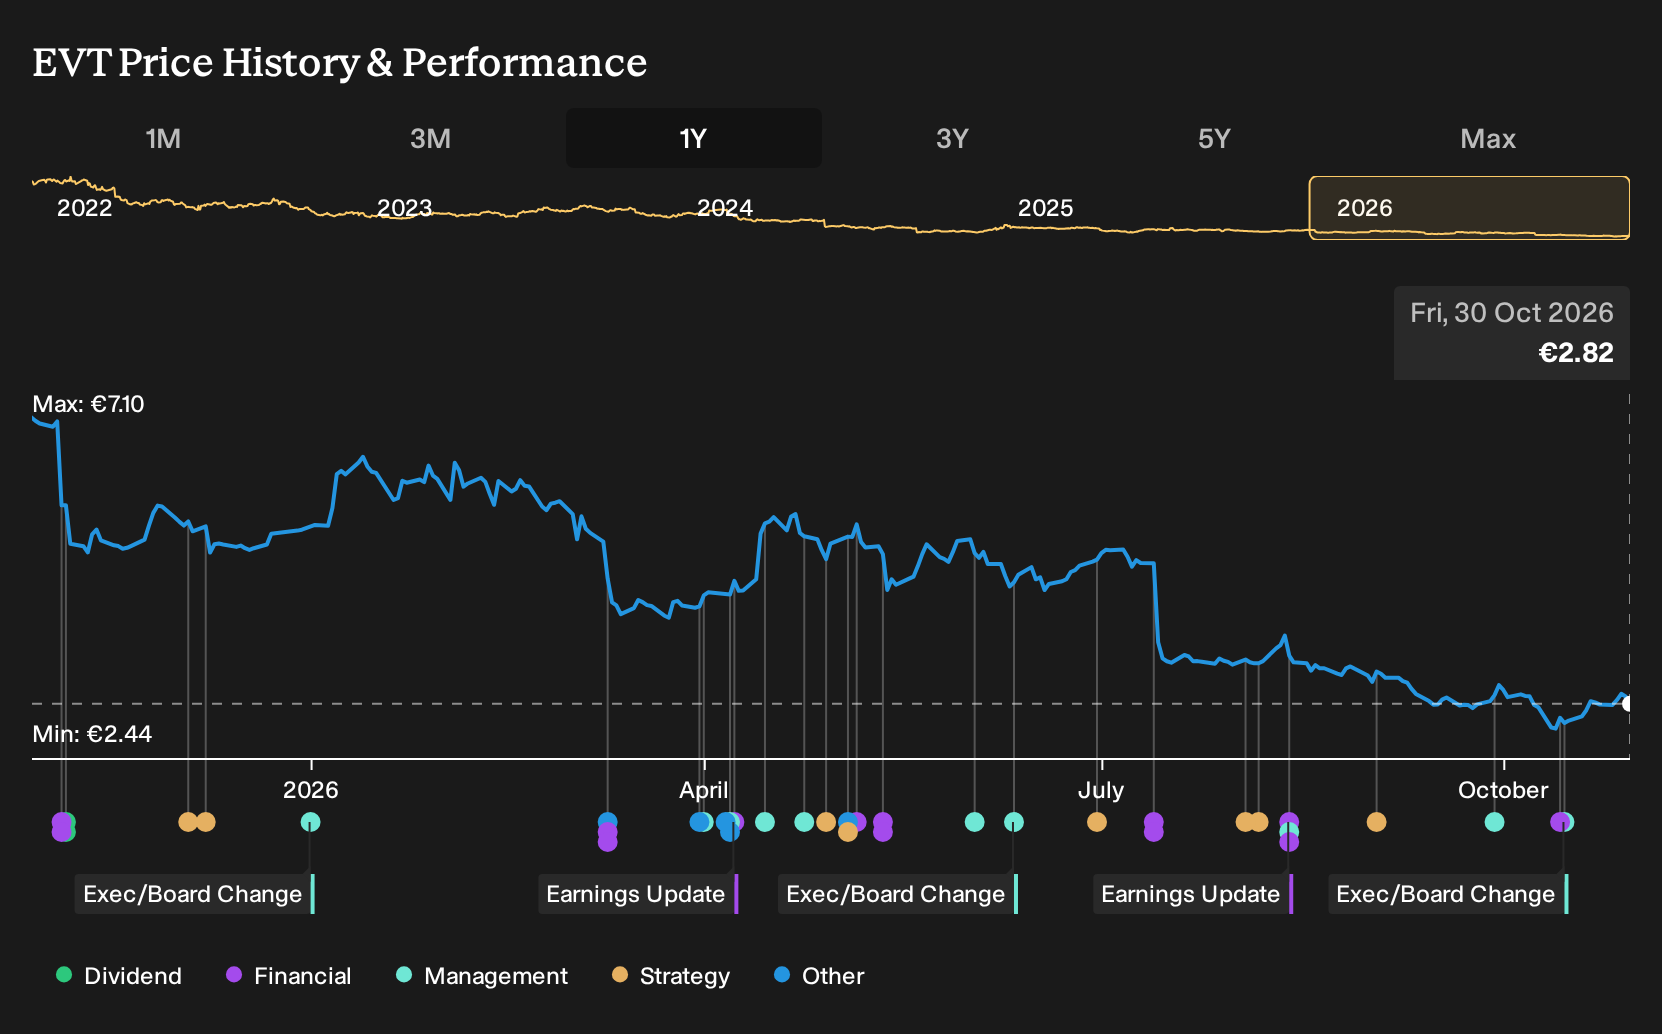
If you had looked at Evotec in late October 2025 and decided to skip it while bulls talked up AI drug discovery and recurring revenue, the choice may feel very different now. For Evotec shareholders, the loss over the past year was 60.1%, including dividends. With guidance later cut and profitability still some way off, which original assumption about growth, margins or valuation would you want to interrogate most carefully today?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
Evotec has already moved. Pinpoint other ways to investigate the theme among 125 healthcare AI stocks.
The Two Evotec Stories Investors Had To Weigh
The shares cost €7.1 at the start of the period, and Evotec sat between two very different stories about what might come next.
The bullish narrative put fair value at €12. It leaned on revenue growing 13.6% a year and profit margins moving from a loss to 11.0%, supported by confidence in AI driven discovery and higher margin partnerships.
The bearish view set fair value at €6. It assumed just 4.2% annual revenue growth and flagged inflation, regulation and commoditised services as threats to margins, even with a 6.6% profit margin assumption and a 21.7x future P/E.
What The Results Changed For The Evotec Narratives
The clearest development was Evotec cutting its 2026 revenue and EBITDA guidance, pointing to delayed milestones and slower new partnerships, which directly challenged the bullish confidence in smooth, fast scaling. Reported figures told a similar story. Q2 2026 revenue was €143.5 million against €171.2 million a year earlier, and the net loss widened, with net margin slipping from 25.4% to 32.5%. On profitability, the period supported the cautious case.
The lesson to carry to other stocks is simple. When an upbeat thesis leans on rapid margin repair, keep checking guidance against the reported net margin and EBITDA line rather than just watching the top line.
What Evotec’s New Price Asks You To Believe
Evotec trades at €2.82 today, and the selected Narrative’s Fair Value sits above that level, which treats the current quote as pricing in a lot of recent pain.
The bullish argument leans on cost cuts, an asset lighter Just unit and healthier Discovery & Preclinical Development signals. For the fall to look like opportunity rather than warning, a buyer must believe Horizon execution really turns today’s order interest into profitable, higher margin revenue.
"The main thing that has to go right is that Evotec executes on the Horizon restructuring and the shift to an asset lighter, technology and licensing focused model so that improving D&PD demand indicators and Just technology revenues translate into the mid term revenue and margin framework management has outlined."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Go Straight To The Source
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 35% below our estimate - uses recent acquisitions and digital tools to address long-term infrastructure and water projects.
- Company 2 - 43% below our estimate - extends composite know how into new mobility platforms while pursuing a cash focused efficiency program.
- Company 3 - 22% below our estimate - ramps capacity and digitalisation to deliver complex munitions, vehicles, electronics and space contracts.
Those are three of them. See every one of the 204 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com