


EN
Should Lower Q3 Earnings Require Action From Boyd Gaming (BYD) Investors?
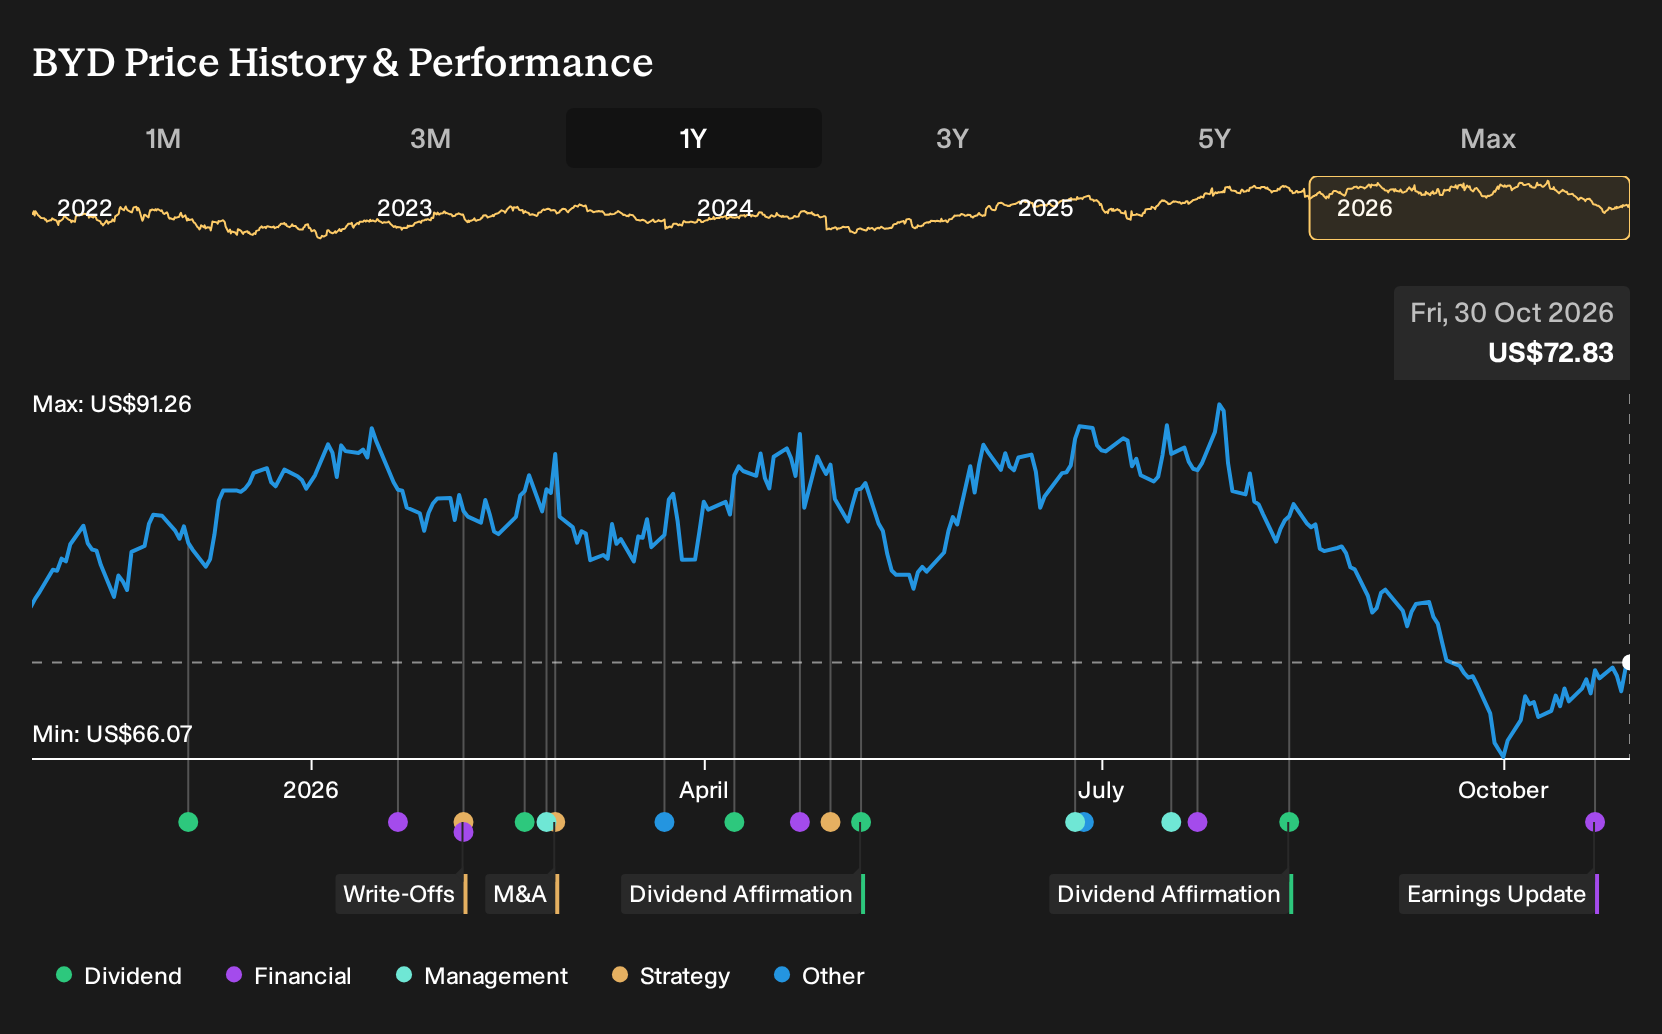
- Boyd Gaming reported third quarter 2026 results with revenue of US$990.46 million and net income of US$124.93 million, both lower than the prior year period, alongside a sharp drop in earnings per share from continuing operations.
- The nine month figures show revenue broadly flat at US$3.02b, while net income and earnings per share declined significantly. This points to margin pressure rather than top line weakness as the key issue.
- We will look at how Boyd Gaming's investment narrative compares with the sharply lower year over year earnings per share.
Compare Boyd Gaming's earnings reset against a curated mix of resilient operators by scanning our list of solid balance sheet and fundamentals (24 results), which highlights companies that can better withstand profit swings like this.
Boyd Gaming Investment Narrative Recap
For Boyd Gaming, the simple thesis is that steady locals and regional play, supported by online and managed operations, can carry the story while construction projects and destination softness are worked through. The latest quarter complicates that picture. Revenue stayed broadly similar, yet earnings dropped sharply, so you now have to be comfortable with compressed profitability in the near term.
The key short term catalyst is execution on the capex program without further erosion in margins. Construction disruption and softer destination demand are already weighing on EBITDAR, and the new earnings print underlines that risk rather than changing it. If anything, the report makes operational discipline more central to the Boyd Gaming case.
The most relevant announcement is the October 22 earnings release itself, which showed third quarter revenue of US$990.46 million and net income of US$124.93 million, compared with US$1,004.36 million and US$1,439.99 million respectively a year earlier. Earnings per share from continuing operations reset from US$17.81 to US$1.71, which is a very steep change.
Those figures sit alongside nine month revenue of US$3.02b that is roughly level with the prior period, while net income dropped to US$361.71 million from US$1.70b. That mix of flat top line and sharply lower earnings points you back to the existing risks around margin pressure, construction drag and high debt, and keeps execution on Boyd Gaming’s project pipeline and operating costs front and center for catalysts.
Boyd Gaming's narrative projects US$4.4b revenue and US$206.6 million earnings by 2029. This scenario is based on 2.4% yearly revenue growth and an earnings decrease of about US$1.6b from US$1.8b today.
Uncover why Boyd Gaming's fair value indicates a 27% potential upside to its current price before the window for that discount narrows.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community span roughly 0.4x to more than 148x. This shows some holders see Boyd Gaming as heavily discounted, while others lean toward a rich outcome. Set that against construction disruption, destination softness and the Norfolk and Sky River projects, and you get very different expectations for future earnings power. Readers should compare these viewpoints directly.
Explore 2 other Boyd Gaming fair value estimates, including one that suggests as much as 104% above the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Boyd Gaming research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Boyd Gaming. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Boyd Gaming's overall financial health at a glance.
Looking For More Ideas Beyond Boyd Gaming?
If Boyd Gaming's latest results have you reassessing where to put fresh capital to work, it can help to widen the lens and compare it with other businesses filtered for the traits you care about most. The Simply Wall St Screener lets you do exactly that by zeroing in on balance sheet strength, valuation appeal or income potential in a few quick steps.
- If capital preservation sits high on your list, start with companies that screen for lower risk profiles through the 29 resilient stocks with low risk scores and see which ones line up with your tolerance for volatility.
- For investors focused on long term compounding, use our filter highlighting 19 high quality undiscovered gems and look for strong fundamentals that the wider market may not be paying close attention to yet.
- If reliable income is a priority, target higher yielding payers by scanning the 5 dividend fortresses and shortlist the payouts you want to research next.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com