


EN
Should Impairment Charge Require Action From RPC (RES) Investors?
- RPC, Inc. reported third quarter 2026 sales of US$467.74 million and a net loss of US$41.93 million, and its board affirmed a regular US$0.04 per share quarterly dividend payable on December 10, 2026 to stockholders of record on November 10, 2026.
- The business recorded a US$74.5 million non cash impairment related to Pintail Wireline, which turned higher sales into a quarterly loss despite improved adjusted EBITDA margins.
- We will now assess how RPC's investment narrative is affected by the Pintail Wireline impairment and the shift from profit to loss.
RPC Investment Narrative Recap
To own RPC, you need to be comfortable with a cyclical completion services provider that is leaning on technology, efficiency and a diversified service mix rather than pure volume growth. The big near term swing factor is how disciplined the firm can stay on pricing while keeping fleets utilized. Management signaling caution around new equipment reactivations suggests that the impairment does not change that near term focus in a material way.
The Pintail Wireline write down does, however, underline the key risk. Wireline and pressure pumping remain exposed to pricing pressure, job mix shifts and customer spending cuts, which have already pushed RPC into a net loss despite higher sales and better adjusted EBITDA margins. Investors need to be comfortable that future capital allocation into these segments is more selective and that management protects cash generation through the cycle.
The most relevant announcement here is the third quarter 2026 earnings release. It pairs higher sales of US$467.74 million and stronger adjusted EBITDA margins with a net loss of US$41.93 million after the US$74.5 million non cash Pintail impairment. That mix indicates that RPC is still working through legacy bets while trying to lean into more differentiated tools and services.
For catalysts, watch how quickly wireline profitability stabilizes and whether pricing in core basins allows the business to keep adjusted margins near current levels without adding fleets. At the same time, the regular US$0.04 per share dividend, alongside an unprofitable nine month period, keeps the sustainability question front and center for income focused holders who care about coverage from earnings and free cash flow.
RPC's current earnings of US$19.6 million are projected by analysts to reach US$116.0 million by 2029, implying an increase of about US$96 million. Their narrative pairs this with an expected revenue path to US$1.9b by the same year, which aligns with a 2.6% yearly revenue growth assumption in the consensus models.
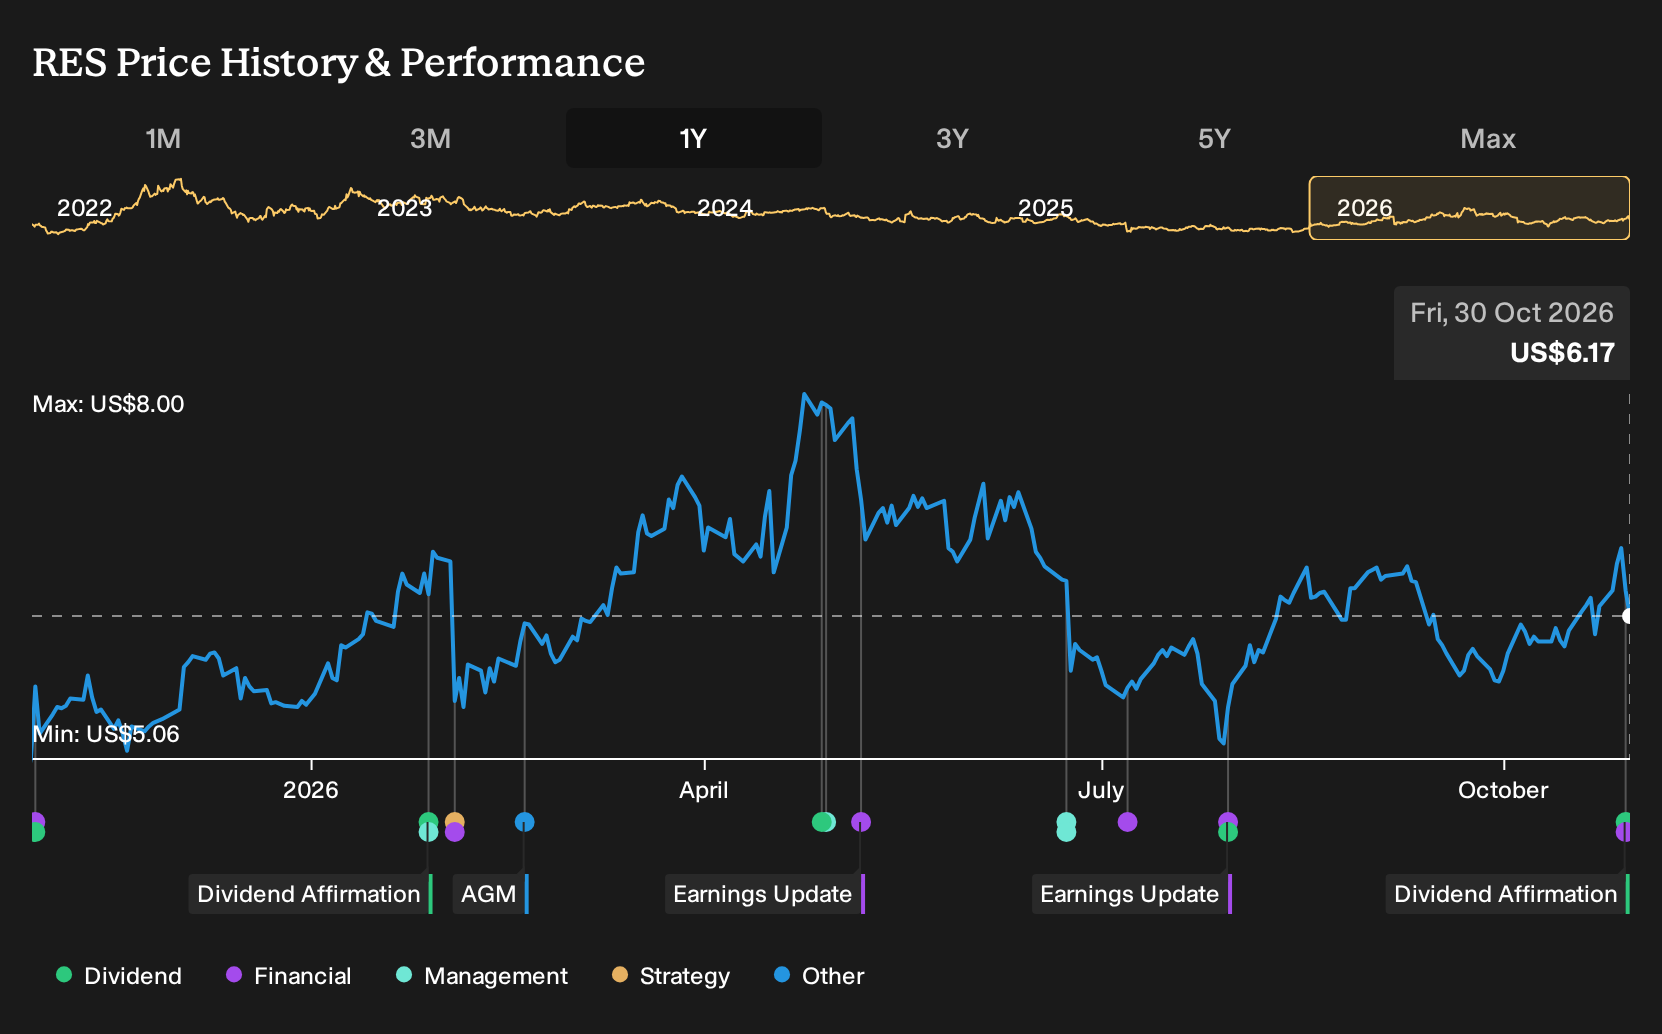
Uncover why RPC's fair value indicates a 6% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view on RPC leans hard on the risk that heavier capital expenditure caps free cash flow. The most bearish analysts were already assuming flattish revenue toward roughly US$1.8b and earnings of about US$91.4 million by 2029 before this impairment and dividend affirmation. This could prompt those expectations to be revisited.
Explore 3 other RPC fair value estimates, including one that suggests as much as 29% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your RPC research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for RPC. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate RPC's overall financial health at a glance.
Looking For More Investment Ideas Beyond RPC?
If the RPC story leaves you wanting a broader watchlist, using the Simply Wall St Screener can help you line up other opportunities across very different risk and income profiles.
- For investors who want resilience at the portfolio core, start with companies that appear built to absorb shocks and still compound steadily by reviewing 29 resilient stocks with low risk scores.
- If a stronger balance sheet matters more to you than headline growth, narrow the field to businesses with cleaner leverage and liquidity metrics using the list of solid balance sheet and fundamentals (24 results).
- Those hunting for underappreciated quality can focus on companies where fundamentals and valuation look out of sync by scanning the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com