


EN
Should Earnings Beat Momentum Require Action From GigaCloud Technology Stock Investors?
- GigaCloud Technology has recently reported a pattern of outperforming earnings expectations, with the last two quarters showing an average earnings surprise of 28.01% and the most recent quarter coming in at $1.16 per share versus a $0.85 per share consensus.
- The company’s positive Earnings ESP of 12.78% and Zacks Rank #1 have sharpened focus on how its marketplace and logistics execution might be translating into stronger profitability than many models had assumed.
- This article examines how GigaCloud Technology's investment narrative is affected by repeated earnings beats that exceed analysts' profit expectations.
Scan other stocks that have been hand-picked for strong fundamentals and potential earnings momentum alongside GigaCloud Technology through the 19 high quality undiscovered gems.
GigaCloud Technology Investment Narrative Recap
To own GigaCloud Technology, you have to believe its supplier-fulfilled marketplace and logistics engine can keep drawing in manufacturers and resellers across the US, Europe and Asia, even as conditions shift. The recent pattern of earnings beats suggests the operating model is currently converting gross merchandise volume and acquired portfolios into profits more efficiently than many expected.
The near term swing factor still looks like execution in Europe and on acquisitions like New Classic, paired with keeping logistics and freight costs in check. The latest upside surprise supports confidence in that execution. It does not remove the risk that higher shipping, warehousing or regulatory friction could pressure margins again.
The most relevant recent data point is the company repeatedly reporting earnings ahead of forecasts, including the US$1.16 per share result against a US$0.85 consensus in the last quarter. For a platform like GigaCloud Technology, that kind of beat usually reflects solid marketplace throughput, disciplined acquisition integration and reasonably tight cost control.
This matters for the current catalysts. International scaling, especially in Europe, and deeper marketplace network effects are more credible when profits track ahead of earlier expectations. At the same time, investors still need to watch known pressure points like the soft revenue trend in New Classic, logistics cost swings and any slowdown in cross-border demand.
GigaCloud Technology's current analyst playbook points to revenues of US$2.0b and earnings of US$221.8 million by 2029. These figures are built on an assumed 10.0% yearly revenue growth rate and an earnings lift of about US$65.7 million from the US$156.1 million reported today.
Uncover why GigaCloud Technology's fair value indicates a 5% potential upside to its current price that could narrow quickly.
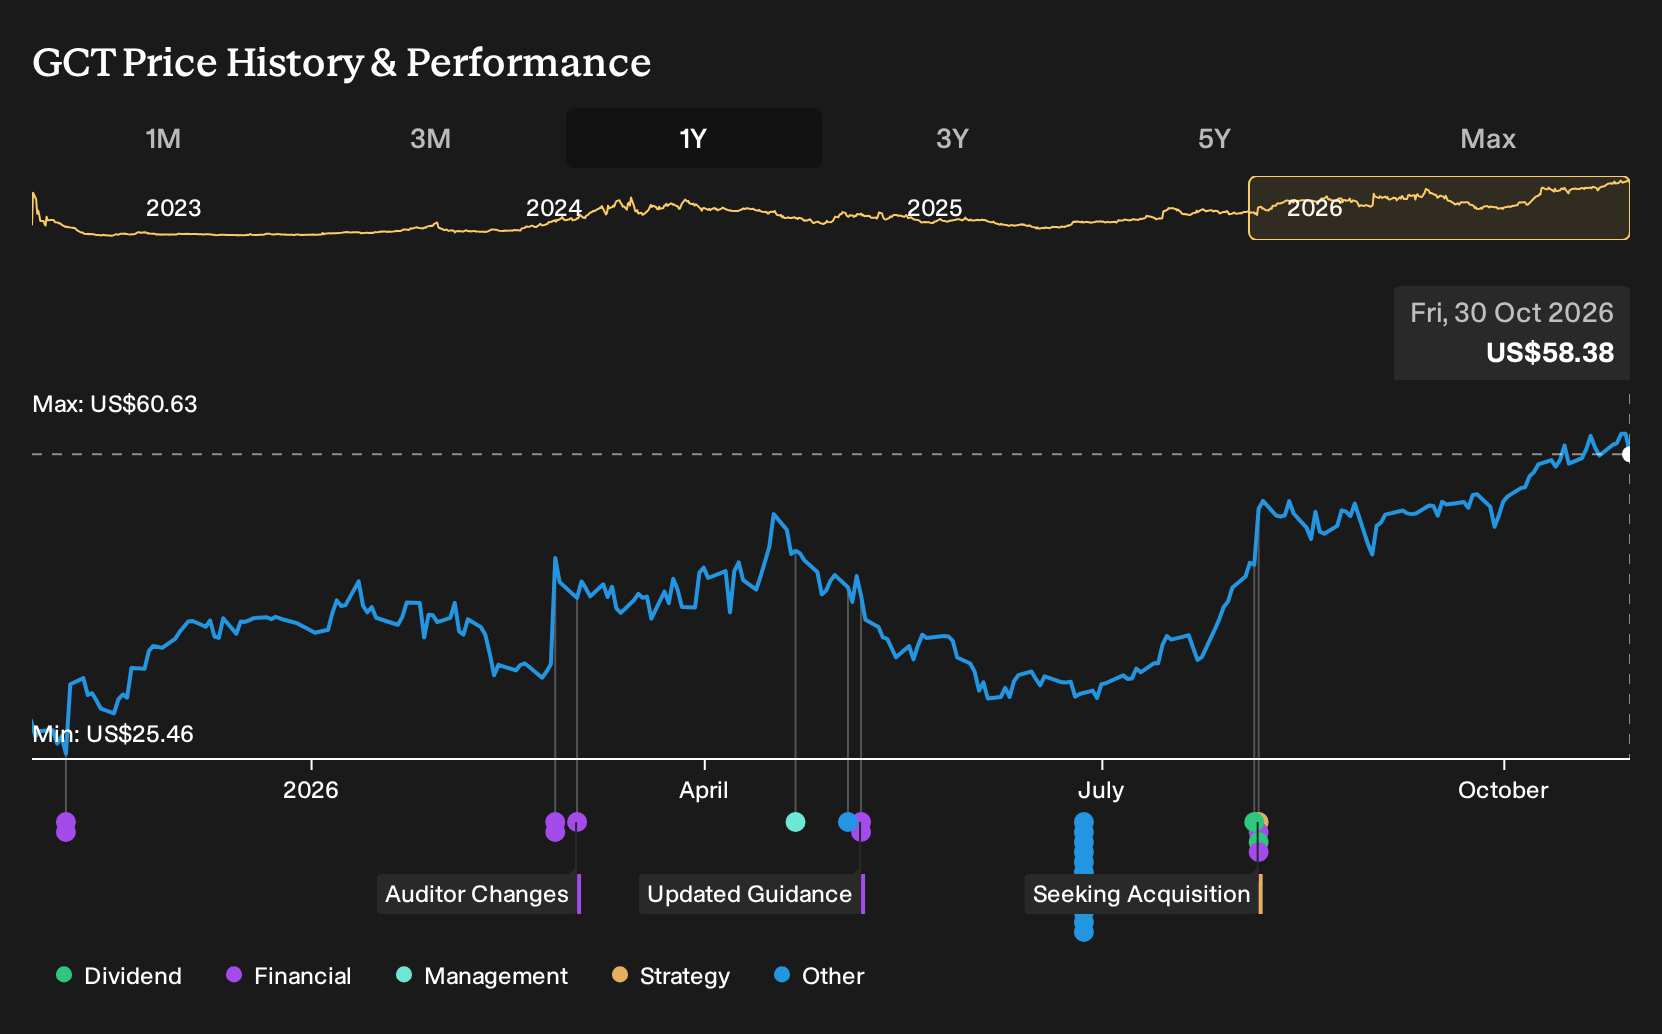
Exploring Other Perspectives
Some of the most optimistic analysts frame the big swing factor very differently. You might worry about freight costs or Europe. They focus on buybacks and earnings power. Their pre news models were already pencilling in US$2.0b of revenue and around US$252.4 million of earnings by 2029. That is a much punchier GigaCloud Technology story, and this latest earnings surprise could push those projections in new directions.
Explore 3 other GigaCloud Technology fair value estimates, including one that suggests up to 31% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your GigaCloud Technology research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for GigaCloud Technology. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate GigaCloud Technology's overall financial health at a glance.
Looking for more investment ideas beyond GigaCloud Technology?
If GigaCloud Technology has sharpened your focus on earnings quality and balance sheet strength, it can help to compare it with other companies that meet similar filters. The Simply Wall St Screener gives you a quick way to sort through stocks by fundamentals, risk profile and income potential so you can build a watchlist that suits your own approach.
- If capital preservation comes first for you, start with a basket of stocks screened for resilience through the 29 resilient stocks with low risk scores.
- If you want businesses with room for a potential re rating, filter for attractively priced opportunities using the 33 high quality undervalued stocks.
- If steady income matters in your plan, focus on companies offering robust payout profiles through the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com