


EN
Budweiser Brewing Company APAC (SEHK:1876) Following Q3 Profit Squeeze Is The Undervalued Case Intact
Budweiser Brewing Company APAC (SEHK:1876) is back in focus after its nine month 2026 earnings call on 29 October, following a sharp squeeze in third quarter profitability and softer group revenue.
At a share price of HK$5.89, Budweiser Brewing Company APAC has seen pressure build over time, with the 90 day share price return down 10.49% and the year to date share price return down 24.20%. The 3 year total shareholder return has fallen 55.36%, pointing to fading momentum as investors reassess earnings risks after the recent profit squeeze in China.
Spot under-pressure consumer stocks like Budweiser Brewing Company APAC and compare them with our handpicked 204 high quality undervalued stocks, which pair resilient cash generation with stronger recent share price trends.The selloff already prices in a sharp profit squeeze at Budweiser Brewing Company APAC. The key question now is whether to pay today’s HK$5.89, or wait and hope sentiment and valuation reset even further.
Most Popular Narrative: 26% Undervalued
Budweiser Brewing Company APAC’s most followed narrative sees fair value at HK$8.00 against the last close of HK$5.89, which puts the recent selloff in a different light for anyone focused on long term earnings power.
Further growth and mix improvement in India and South Korea, where India delivered double digit revenue growth and South Korea recorded low teens volume growth with strong double digit normalized EBITDA growth and a 400 bps margin expansion in Q2 2026, provide Budweiser Brewing Company APAC with earnings contributions from markets that currently perform better than China and can lift group level revenue and EBITDA margins over time.
See why 4 investors see Budweiser Brewing Company APAC as 26% undervalued.
That storyline uses a 7.07% discount rate and assumes Budweiser Brewing Company APAC can shift more volume and profit mix into India and South Korea, while gradually turning China from a drag into a contributor through premium brands and in home and O2O channels. On those inputs, a fair value of HK$8.00 implies the current HK$5.89 quote reflects a sizeable gap to the narrative’s assessment of future cash generation and profitability.
Result: Fair Value of HK$8.00 (UNDERVALUED)
Still, the whole narrative can wobble if China’s volume and EBITDA weakness proves more structural, or if rising aluminum costs cut more deeply into margins.
Find out about the key risks to this Budweiser Brewing Company APAC narrative.
Another View: What The Market Multiple Says
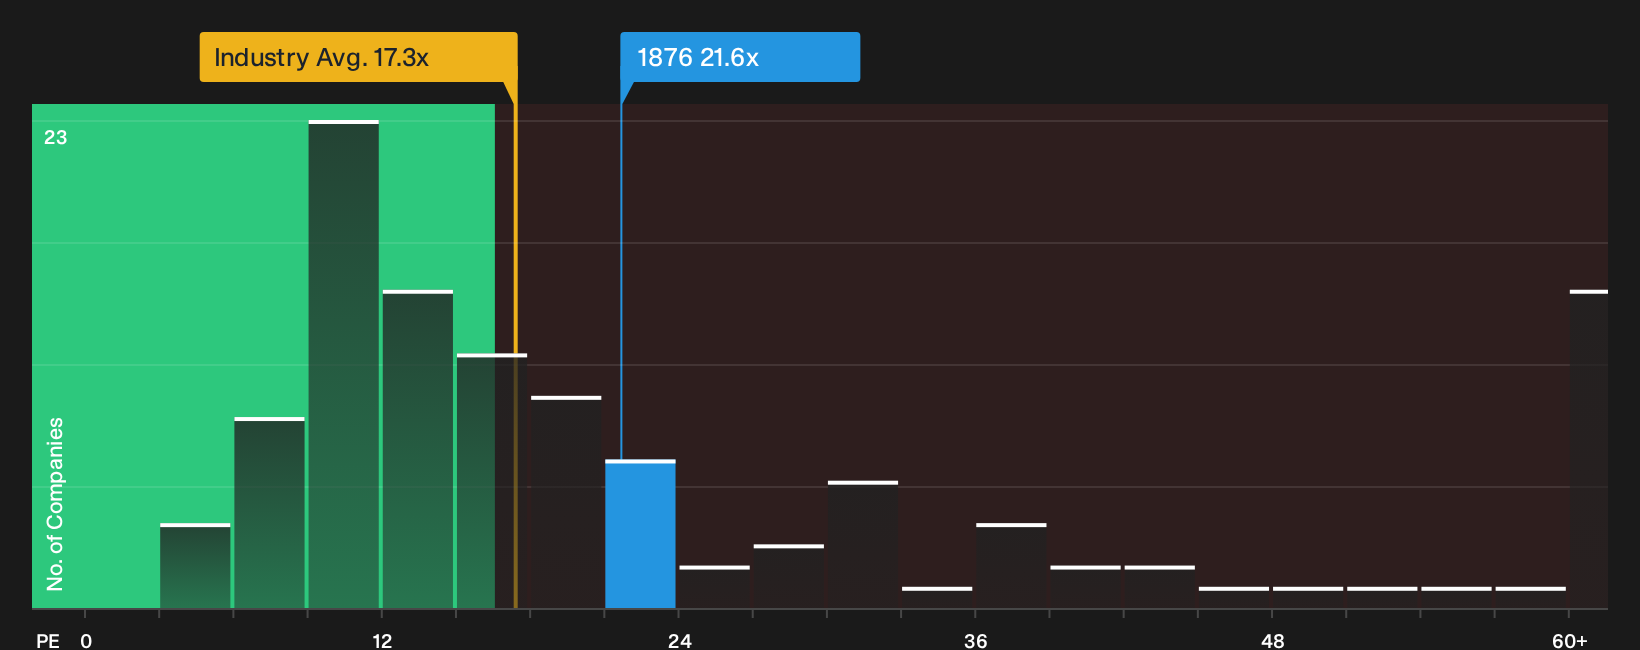
The first narrative presents Budweiser Brewing Company APAC as undervalued on a fair value of HK$8.00, while the market is pricing the stock on a richer 21.6x P/E. That level is higher than both the Asian Beverage group on 17.2x and the estimated fair ratio of 14.7x, which suggests meaningful valuation risk if sentiment weakens again.
This leads to a straightforward question for you as an investor: is this a genuine disconnect between price and long-term cash flows, or is the market already paying for a recovery that still needs to be earned, given the pressure in China and softer margins?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in Budweiser Brewing Company APAC’s story can be useful. Use the full data set, then weigh the 2 key rewards and 1 important warning sign against your own view.
Looking for more investment ideas beyond Budweiser Brewing Company APAC?
If you stop your research with Budweiser Brewing Company APAC, you miss chances elsewhere. Broaden your watchlist and let stronger setups come to you.
- Target powerful income streams by reviewing companies in the 221 dividend fortresses and see which payouts might better match your cash flow goals.
- Spot potential mispriced opportunities early by scanning the 614 high quality undiscovered gems before attention and capital crowd the trade.
- Dial down portfolio stress by focusing on the 218 resilient stocks with low risk scores, which may align with steadier balance sheets and more measured volatility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com