


EN
Missed Regeneron Pharmaceuticals' Run? What Holders Believed
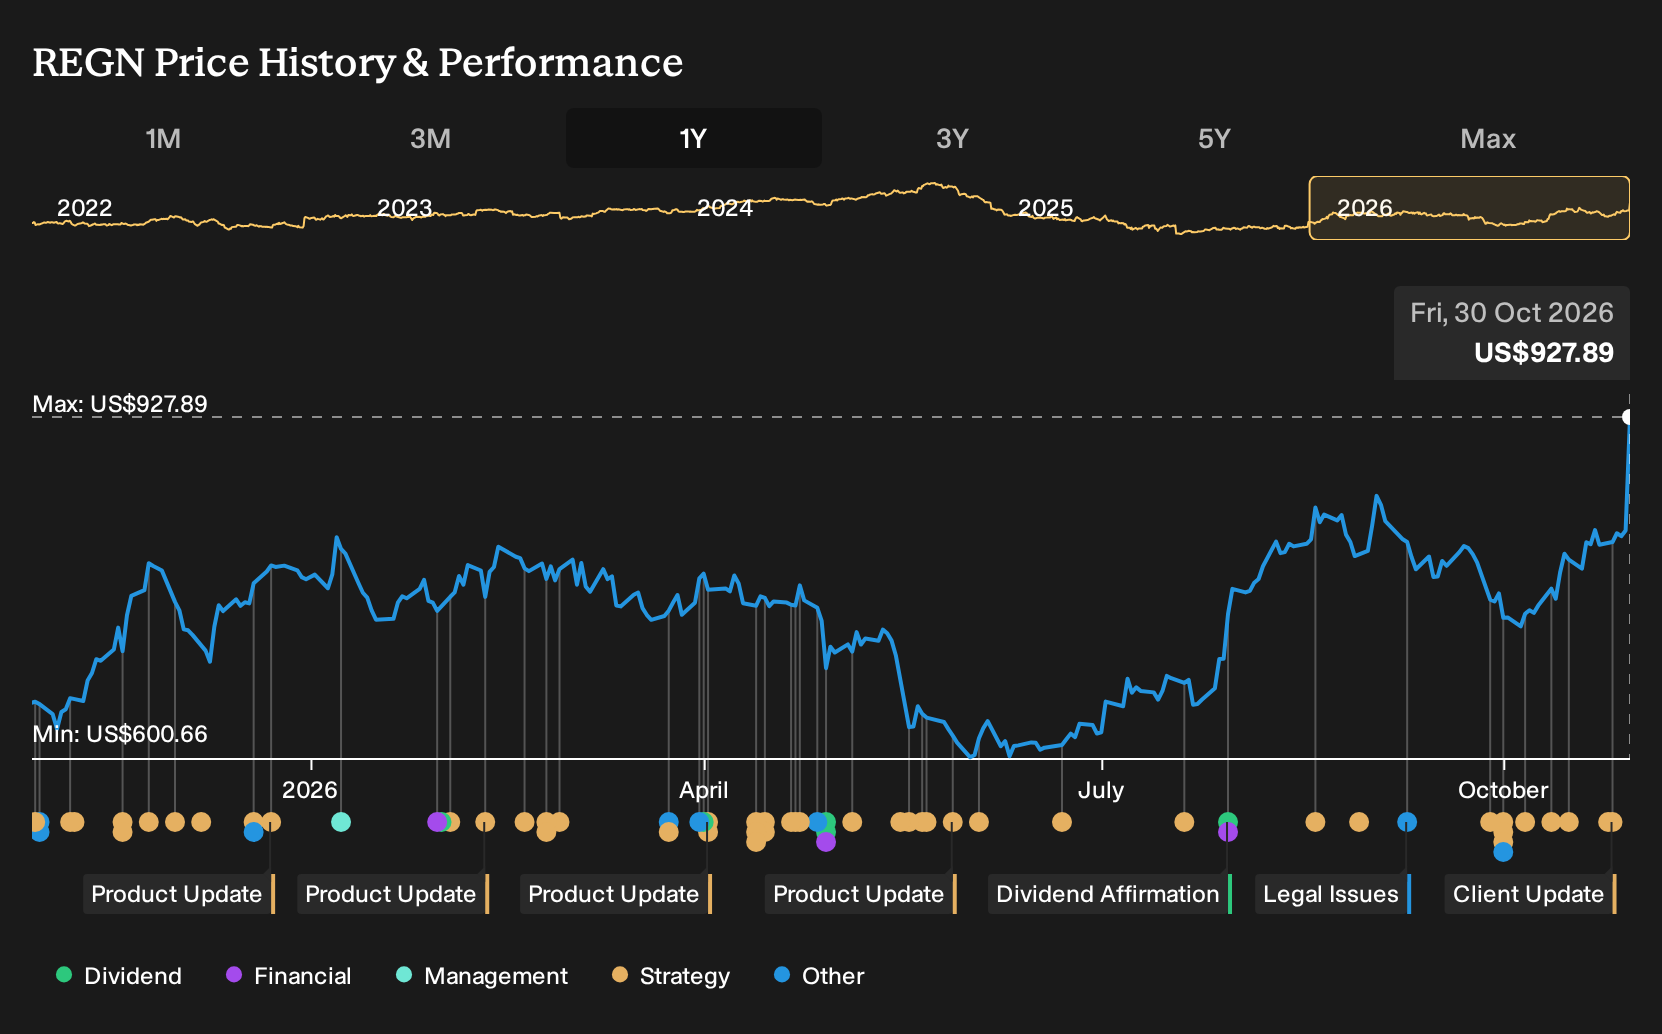
Regeneron Pharmaceuticals spent the past year signing billion dollar research alliances and pushing new drugs like Pasatru and Otarmeni toward patients. Yet one smaller headline in April 2026 stood out: a US$4.3b radiopharmaceutical tie up with Telix that pulled the group deeper into solid tumor treatments. Holding Regeneron Pharmaceuticals over the past year would have returned 43.1%, including dividends. If you had bought on 30 October 2025, what exactly needed to be true in your mind for that Telix deal to feel like confirmation rather than a surprise?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
The move put Regeneron Pharmaceuticals in the middle of this trade. Scan 34 healthcare AI stocks for other companies exposed to it.
The Argument You Would Have Been Weighing Up On Regeneron Pharmaceuticals
The shares cost US$654 at the start of the period, which meant any view on Regeneron Pharmaceuticals hinged on which story felt more realistic.
The bullish narrative put fair value at US$722, or 10% above the start price, based on assumptions of revenue growth of 5.4% a year and a future P/E of 16.1x, supported by a broad pipeline and products like Dupixent and EYLEA HD.
The bearish view set fair value at US$540, 17% below the start price, and focused on the risk that healthcare reforms and biosimilars would compress profit margins toward 22.5% despite ongoing R&D spend.
What The Evidence Did To The Regeneron Pharmaceuticals Argument
The Telix radiopharmaceutical collaboration pulled Regeneron Pharmaceuticals deeper into solid tumors, which supported the optimistic case that partnerships could broaden the oncology toolkit beyond Fianlimab and Lynozyfic. At the same time, the failed Phase 3 Fianlimab Libtayo melanoma trial and related class actions challenged confidence in clinical execution and differentiation. Q3 2026 revenue and profit were higher than Q3 2025, while net margin slipped from 38.9% to 38.1%, so the evidence cut both ways.
The lesson is simple. When a thesis leans on pipeline strength, it helps to track how each flagship program and deal shows up in later trial outcomes, regulatory milestones and reported margins, rather than assuming every headline supports the same story.
What Regeneron Pharmaceuticals' Price Now Assumes
Today Regeneron Pharmaceuticals trades at US$928. The selected Narrative places its Fair Value below that level, which means the current quote already bakes in a lot of confidence about execution and durability.
The Narrative focuses on concentrated product exposure, complex late stage programs and legal overhangs. Anyone paying today effectively assumes newer franchises offset pressure on Dupixent, EYLEA HD and margins. The open question is how those specific risks intersect with that expectation.
"Although Dupixent currently anchors Regeneron Pharmaceuticals as a leading immunology franchise with large underpenetrated indications, management already flags that year over year growth is expected to moderate in the second half of 2026 as recent launches annualize and comparisons get tougher, which could slow the pace of revenue and earnings expansion just as investors extrapolate current growth rates."
The price and this Narrative do not agree. → Uncover what this Narrative says Regeneron Pharmaceuticals is actually worth
How Could You Get There Earlier?
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 32% below our estimate - builds AI superclusters that large model developers use for overflow compute capacity.
- Company 2 - 38% below our estimate - ramps high horsepower engine capacity to serve long-duration data center power contracts.
- Company 3 - 46% below our estimate - expands higher margin payment products as merchants route more emerging market volumes.
That is three of the list. See all 33 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com