


EN
Rogers (ROG) Dropped, So What Is Driving Attention Now?
Rogers (ROG) is back in focus after its third quarter report showed basic earnings per share from continuing operations of US$1.27, compared with US$0.48 a year earlier.
Rogers’ strong third quarter has arrived alongside choppy trading, with the latest 1-day share price return down 5.18%, the year-to-date share price return up 44.68%, and the 1-year total shareholder return at 52.00%, suggesting that recent momentum has cooled while remaining firmly positive over a longer horizon.
Spot opportunities that follow the same earnings and margin themes as Rogers by scanning our hand picked list of 19 high quality undiscovered gems in related sectors.Rogers has already delivered a sharp rerating, and recent softness suggests that investors may be pausing rather than closing the book on the story. Is the bigger move now behind the stock, or does valuation still leave meaningful upside on the table?
Most Popular Narrative: 31% Undervalued
Rogers is trading at $133.06, while the most widely followed narrative anchors fair value at $193.33, so the market is treating that long term earnings path with a sizeable discount.
Expansion into AI data center connectivity and cooling through next generation PTFE-based laminates that already meet and exceed M9 performance requirements, with a path to M10, and direct-to-chip microchannel coolers now being prototyped with several major AI chip and data center customers, alongside management’s expectation that these adjacencies contribute meaningfully to roughly US$450 million of targeted incremental revenue by 2030, provides a potential new leg of growth and margin mix improvement.
See why 2 investors see Rogers as 31% undervalued.
Result: Fair Value of $193.33 (UNDERVALUED)
Still, the Rogers narrative can be knocked off course if the high P/E ratio does not reconcile with future earnings delivery, or if EV substrate demand underwhelms.
Find out about the key risks to this Rogers narrative.
Another View: Rogers Through The Cash Flow Lens
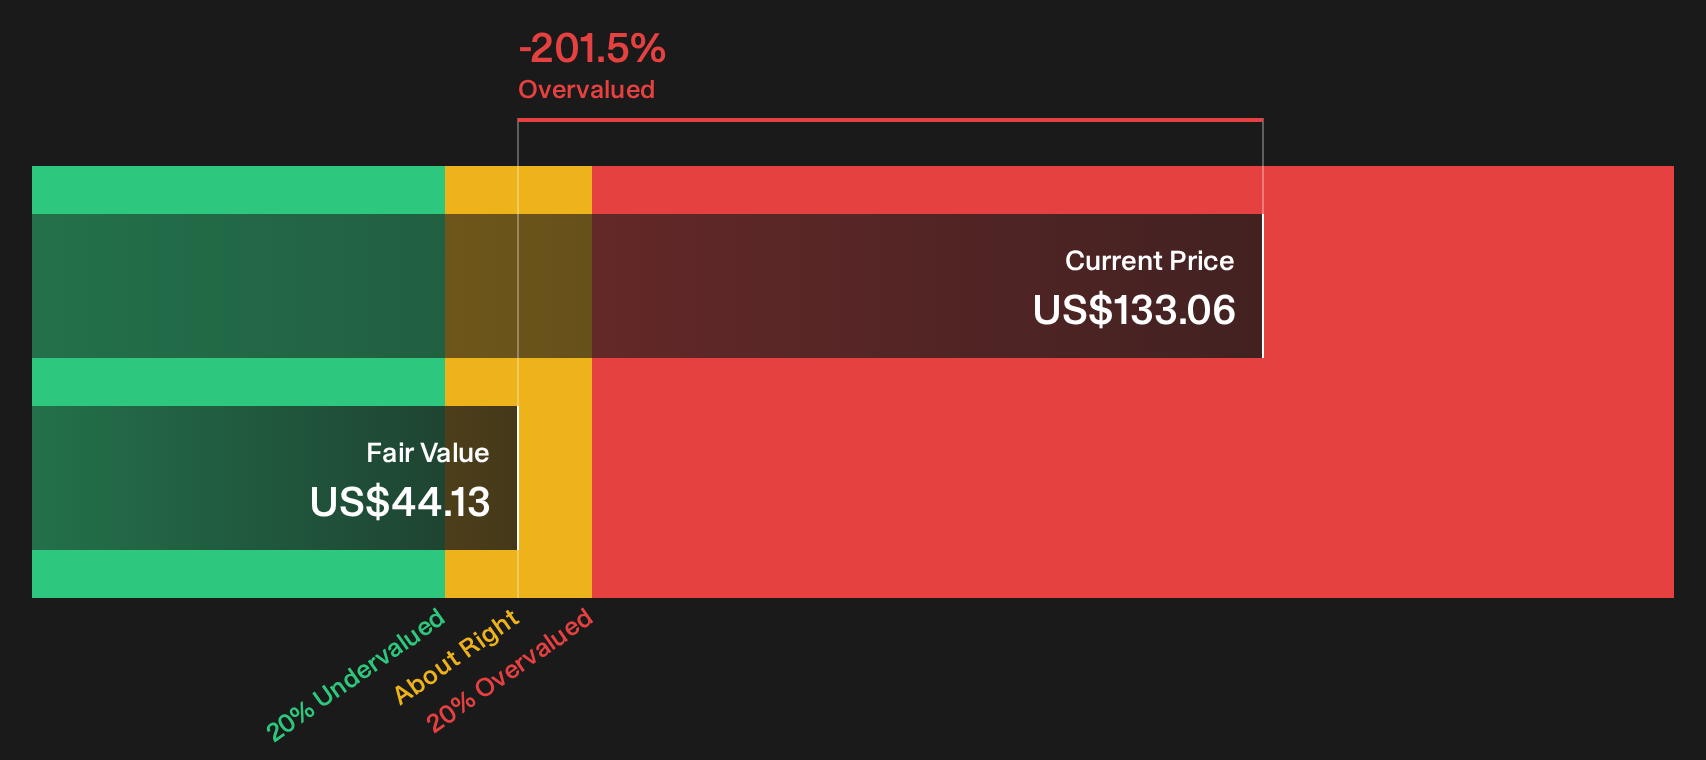
There is a different read on Rogers when the SWS DCF model is used instead of analyst targets. On that framework, the stock at $133.06 trades well above an estimated future cash flow value of $44.13, which screens as overvalued and raises the question of how much optimism is already baked in.
Investors comparing these approaches may want to understand how sensitive that cash flow view is to margins, growth and discount rate assumptions. Each method highlights a different risk boundary for Rogers. Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Rogers for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Rogers is split, which is exactly when fresh data can be most useful and time sensitive for your own decision making. Before settling on any conclusion, check how the upside case compares in our breakdown of 3 key rewards.
Looking For More Investment Ideas Beyond Rogers?
If Rogers has sharpened your thinking, do not stop there. Broader opportunity often sits just outside the first stock that caught your attention.
Use the Simply Wall Street Screener to quickly surface fresh ideas that fit different roles in your portfolio, from potential upside stories to steadier ballast.
- Target potential bargains that pair quality and value by scanning our hand picked set of 33 high quality undervalued stocks.
- Prioritise resilience by reviewing companies highlighted in the 29 resilient stocks with low risk scores that score well on stability and risk checks.
- Strengthen your core holdings by checking the list of solid balance sheet and fundamentals (24 results) for businesses with cleaner balance sheets and healthier fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com