


EN
What Unicharm (TSE:8113)'s East Africa Sales Launch Means For Shareholders
- Unicharm brought its East African joint venture with Toyota Tsusho, SOFY UNICHARM EAST AFRICA LIMITED, into full-scale operation in October 2026. The company shifted from a wholesale model to a direct sales system to steer its own marketing and distribution across Kenya and nearby markets.
- The new entity, the first overseas subsidiary to carry the SOFY brand, links Unicharm’s commercial push to social goals such as addressing Period Poverty, expanding hygiene education, investing in local female talent, and partnering with governments. It has a stated aim of KSH 1.5 billion in net sales by 2030.
- We will look at how Unicharm’s investment narrative is shaped by this East African direct sales rollout and women-focused hygiene agenda.
Scan how Unicharm’s push into women’s hygiene in East Africa compares with other under-the-radar quality plays by reviewing our curated list of 69 high quality undiscovered gems in similar transition phases.
What Is Unicharm's Investment Narrative?
To own Unicharm, you need to buy into a fairly simple idea. This is a hygiene heavyweight that leans on broad everyday demand across personal care and pet products, while trying to sharpen execution in regions where disposable income and population growth can support higher volumes. The new SOFY UNICHARM EAST AFRICA direct sales push fits that logic. It targets more control over pricing, branding, and distribution in Kenya and nearby markets, with the social agenda around Period Poverty and hygiene education helping build trust with consumers and regulators.
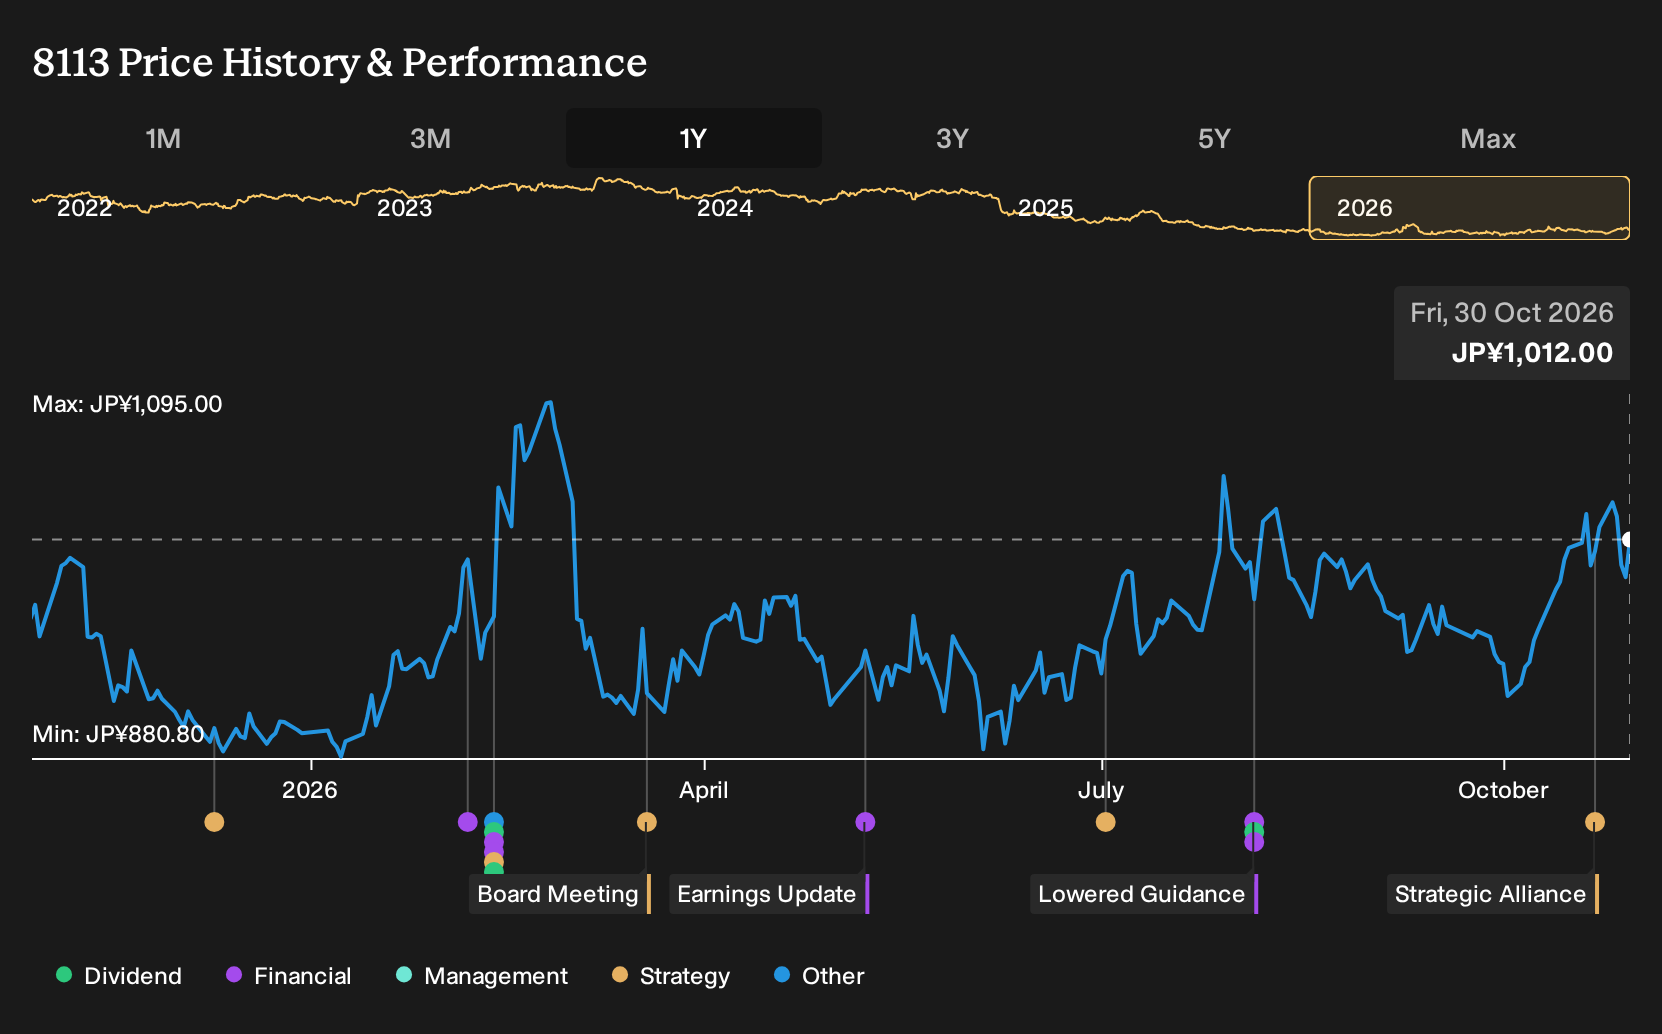
In the near term, the key questions are all operational. Direct sales can tighten feedback loops on demand and margins, but it also adds execution risk and can be capital hungry if Unicharm needs more local capacity or working capital to support distributors. Earnings are forecast to grow 11.63% per year, while the share price is up 12.9% year to date but still below some estimates of fair value. Progress or missteps in East Africa could influence how patient investors are with slower revenue growth forecasts and a relatively high P/E versus regional peers.
Even so, one uncomfortable thread runs through this otherwise tidy story that only becomes obvious when you look closely at...
There's only one way to know the right time to buy, sell or hold Unicharm. Head to Simply Wall St's company report for the latest analysis of Unicharm's Fair Value.
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your Unicharm research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Unicharm. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Unicharm's overall financial health at a glance.
Looking For More Investment Ideas Beyond Unicharm?
If the Unicharm story has sharpened your thinking on quality, risk, and execution, it can be useful to widen the lens and compare it with other businesses that share similar strengths or offer a different balance of income, resilience, and value.
- If you care most about resilient balance sheets and solid fundamentals, start with this list of solid balance sheet and fundamentals (21 results) to see which businesses fit that profile.
- Income focused investors who want yields with staying power can review this curated set of 28 dividend fortresses and stress test their current holdings against them.
- If you prefer to keep risk in check while still staying in equities, use this 23 resilient stocks with low risk scores as a filter for ideas that may better fit a cautious approach.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com