


EN
Is Late Stage Drug Progress Altering The Investment Case For Novartis Stock (SWX:NOVN)?
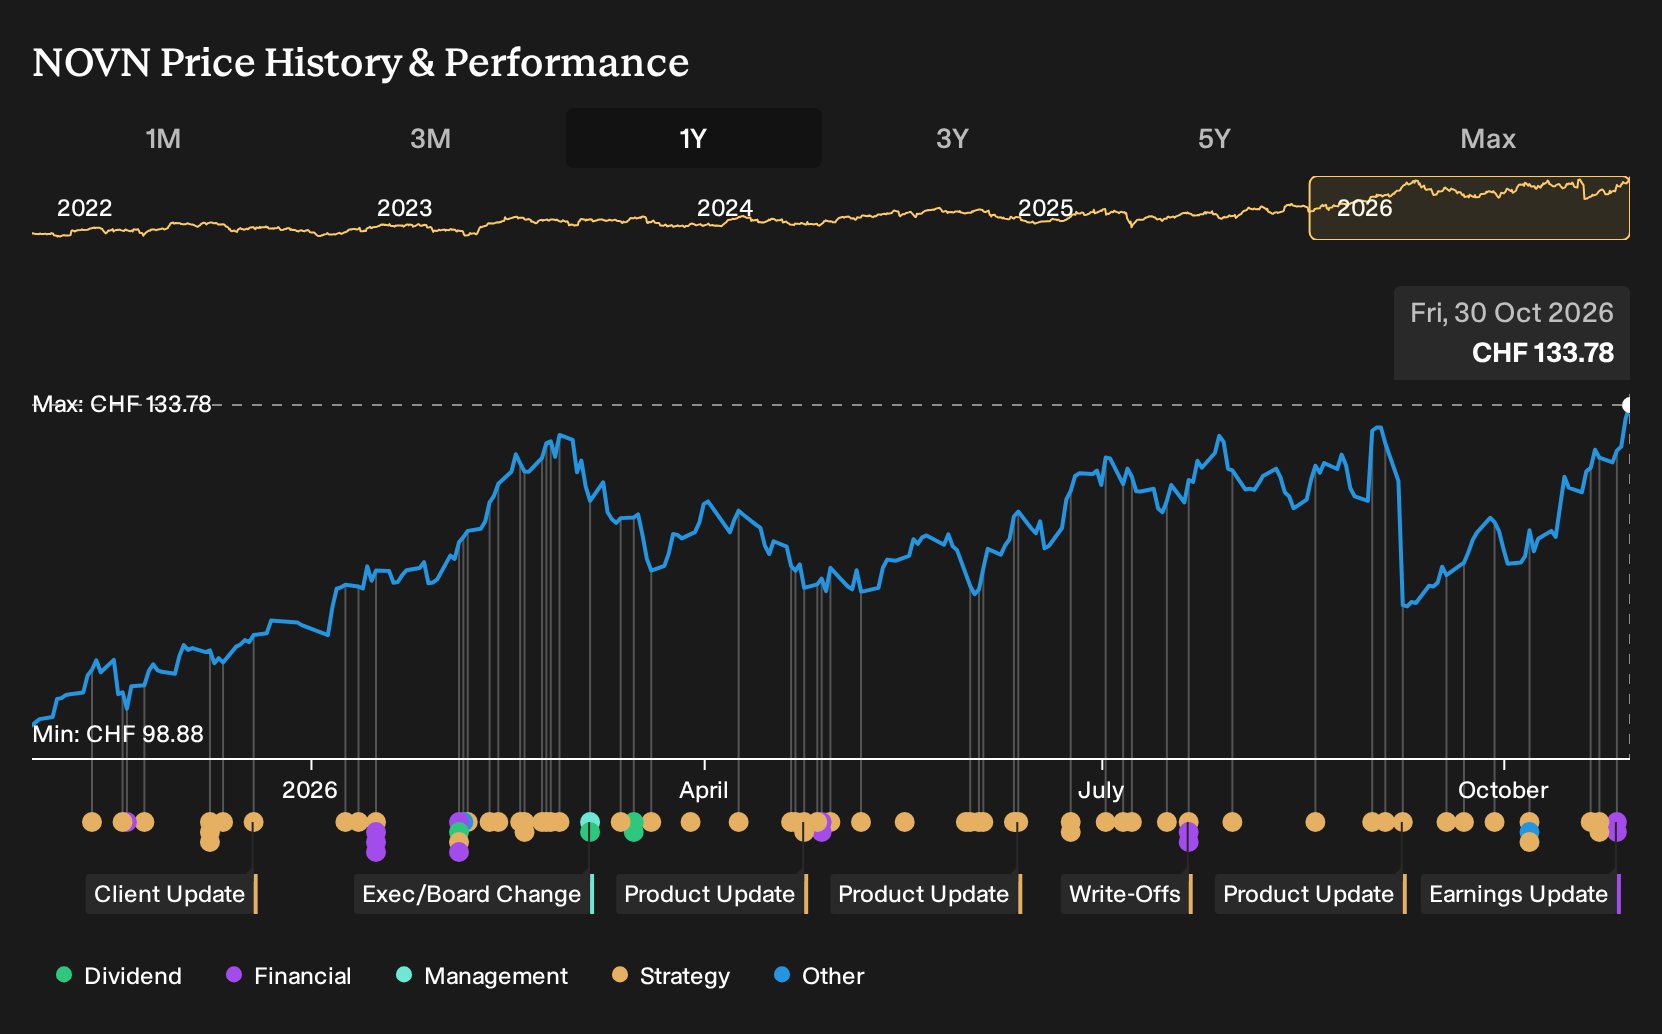
- Novartis reported Q3 2026 sales of US$14.5b and released new late stage data across remibrutinib, Kisqali and Cosentyx, alongside fresh 2026 net sales guidance.
- The combination of remibrutinib Phase III results in relapsing multiple sclerosis and expanded indications for Kisqali and Cosentyx could influence how investors view the depth of Novartis' specialty medicine portfolio.
- Investors may now consider how Novartis' remibrutinib Phase III data could shape the broader investment narrative around its portfolio.
Scan how Novartis fits alongside other defensible healthcare plays by comparing it to 218 resilient stocks with low risk scores that may hold up better when news flow turns choppy.
Novartis Investment Narrative Recap
To own Novartis, you need to believe its newer medicines can offset pressure from older drugs and keep the business moving forward while margins hold up. Q3 2026 results point to that trade off in real time. Sales were US$14.5b, but net income for the quarter and year to date was lower than the prior periods, and profit margins compressed.
The short term swing factor is execution on the priority brands and late stage assets, along with protecting that 40% plus core operating margin that management has targeted historically. The biggest risk right now is that loss of exclusivity, one off hits and Xolair profit share erosion bite harder than expected, before the next wave of launches can fully contribute.
The remibrutinib Phase III data in relapsing multiple sclerosis looks central to that next wave. Novartis reported superior relapse control versus teriflunomide, meaningful reductions in disability progression measures and a clean liver safety profile in REMODEL 1 and 2, which collectively strengthen the case for a broad BTK inhibitor platform.
For you as an investor, this data sits at the intersection of catalysts and risks. A successful launch and label build out could support the specialty medicines mix that management is leaning on as net income and EPS remain under pressure. Any delay in regulatory progress or uptake would leave Novartis more exposed to generic competition and the drag from recent one off items.
Novartis' current analyst narrative points to US$68.8b in revenue and US$18.8b in earnings by 2029, based on an assumed 6.3% yearly revenue growth rate and an earnings increase of about US$8.8b from US$10.0b today.
Uncover why Novartis' fair value indicates a 5% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
One alternate view leans hard into Novartis as a growth story. The most optimistic analysts were sketching out revenue of about US$72.7b and earnings of US$23.5b by 2029 before this Q3 and remibrutinib news. That is a much punchier earnings path than consensus, and it may be revised again once these updates are fully absorbed.
Explore 3 other Novartis fair value estimates, including one that suggests as much as 202% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Novartis research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Novartis. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Novartis' overall financial health at a glance.
Looking for more investment ideas beyond Novartis?
Once you have formed a view on Novartis, it can help to compare it with other opportunities that match your risk profile and income goals using the Simply Wall St Screener.
- If capital preservation is your priority, you can scan for defensible businesses with steadier profiles through our 218 resilient stocks with low risk scores.
- If value is front of mind, you can weigh Novartis against companies that combine solid fundamentals with potentially attractive pricing using the 204 high quality undervalued stocks.
- If income matters most, you can line up Novartis next to high yielding payout candidates by reviewing the 221 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com