


EN
Plains GP Holdings (PAGP) Shares Look 8% Above Fair Value After Special Dividend
Plains GP Holdings (PAGP) has declared a special dividend of US$0.42 per share, with an ex-dividend date of October 30, 2026, and payment scheduled for November 13, which is putting fresh attention on its income profile.
Recent trading shows that momentum in Plains GP Holdings has cooled in the very short term, with the share price slipping 1.49% on the day and 0.75% over the past week. However, the 30 day and 90 day share price returns of 8.94% and 9.19% keep the trend constructive. The current share price of US$28.39 sits against a much stronger backdrop, with a 46.26% year to date share price return and a 1 year total shareholder return of 75.94%. Those income heavy payouts mean longer term investors have seen total shareholder returns of 117.25% over three years and 256.15% over five years, suggesting the special dividend is landing after a period of already robust reward for holders.
Scan other income ideas with midstream-style cash flows by reviewing our hand picked 5 dividend fortresses alongside Plains GP Holdings’ special payout story.
After a multi year run and a fresh special payout, Plains GP Holdings now trades above the average analyst target and at a steep discount to some intrinsic estimates. This raises the question of where fair value really stands.
Most Popular Narrative: 8% Overvalued
Plains GP Holdings closed at $28.39, while the most followed narrative pegs fair value closer to $26.38. As a result, the special dividend is landing against a market price already a bit ahead of that modelled estimate.
The current valuation suggests Plains GP Holdings is fairly valued, with the market already accounting for a stable crude-focused portfolio, targeted $0.15 per unit annual distribution increases and a conservative 150% coverage ratio.
See why 11 investors see Plains GP Holdings as 8% overvalued.
Result: Fair Value of $26.38 (OVERVALUED)
Still, the Plains GP Holdings story leans heavily on crude volumes and investor appetite for a 10.7x P/E in 2029, both of which could break the script.
Find out about the key risks to this Plains GP Holdings narrative.
Another View: Plains GP Holdings On Sales-Based Valuation
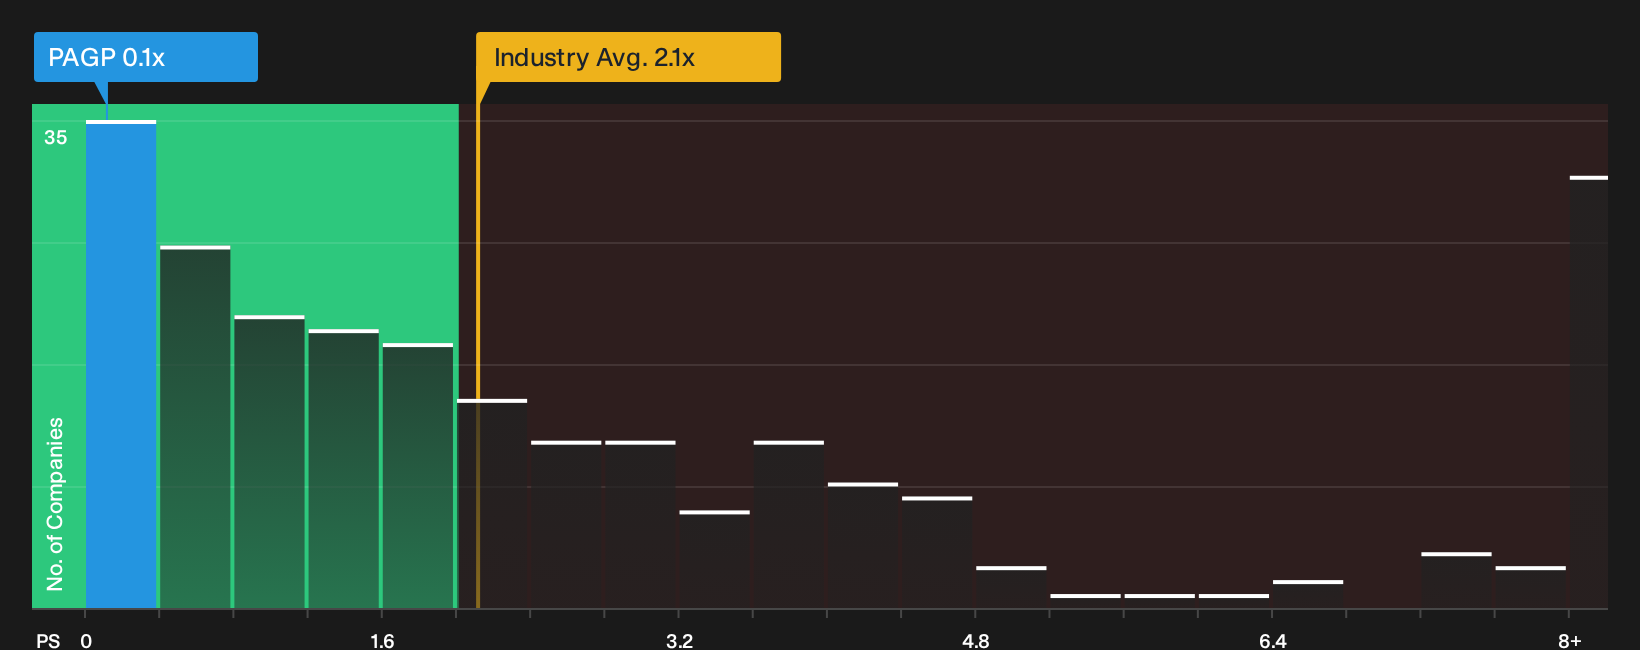
The first fair value estimate for Plains GP Holdings leans on earnings and a 10.7x P/E in 2029. A very different picture appears when you look at the current P/S of 0.1x versus peers at 3.8x and a fair ratio of 0.6x, which points to a wide valuation gap that investors need to judge as either a cushion or a signal that the market is pricing in real risk.
If you want to see how this sales based view stacks up against a fuller set of valuation checks, take a closer look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on Plains GP Holdings valuation and income story today. If you want to move beyond headlines and sentiment, consider both the risks and rewards in the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Plains GP Holdings?
Plains GP Holdings might be your starting point, but you do not want to stop there when other opportunities could fit your portfolio even better.
- Target potential bargains with solid quality by scanning a curated set of undervalued opportunities through the 33 high quality undervalued stocks.
- Focus on resilience by checking companies that pair sturdy finances with dependable metrics in the list of solid balance sheet and fundamentals (24 results).
- Get ahead of the crowd by reviewing financially strong businesses that receive less attention through the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com