


EN
Why Lindsay (LNN) Is Back In The Spotlight
Lindsay (LNN) has just reported full year sales of US$635.86 million and net income of US$55.65 million, both lower than the prior year.
The headline drop in annual sales and profit has come alongside a share price that has slipped, with a 30 day share price return of down 5.9% and a year to date share price return of down 11.2%. The 5 year total shareholder return of down 28.8% points to fading longer term momentum despite the recent 1 day gain following the earnings and dividend update.
Scan the irrigation and infrastructure space beyond Lindsay by reviewing a hand picked list of list of solid balance sheet and fundamentals (24 results) that have already cleared a basic financial strength hurdle.
Lindsay’s results, the softer share price and an intrinsic value estimate that still sits higher than the market all point to the same fork in the road: Is most of the upside already used up, or still ahead?
Most Popular Narrative: 12.5% Undervalued
Against Lindsay’s last close of $107.63, the most followed narrative pegs fair value at $123, leaving a valuation gap that hinges on execution in irrigation technology, infrastructure projects and cost actions over the next few years.
The growing contribution from digital and AI-enabled irrigation technology, including FieldNET, FieldNET Advisor, FieldWise and SmartPivot with new features such as TowerWatch and predictive maintenance, is expected to lift technology revenue and support higher margin mix within Lindsay irrigation earnings.
See why 2 investors see Lindsay as 12% undervalued.
Result: Fair Value of $123 (UNDERVALUED)
Still, the Lindsay narrative could be shaken if North American irrigation softness lingers longer than analysts expect, or if Project Fortify spending weighs on margins without clear payback.
Find out about the key risks to this Lindsay narrative.
Another View: What Lindsay’s P/E Is Really Saying
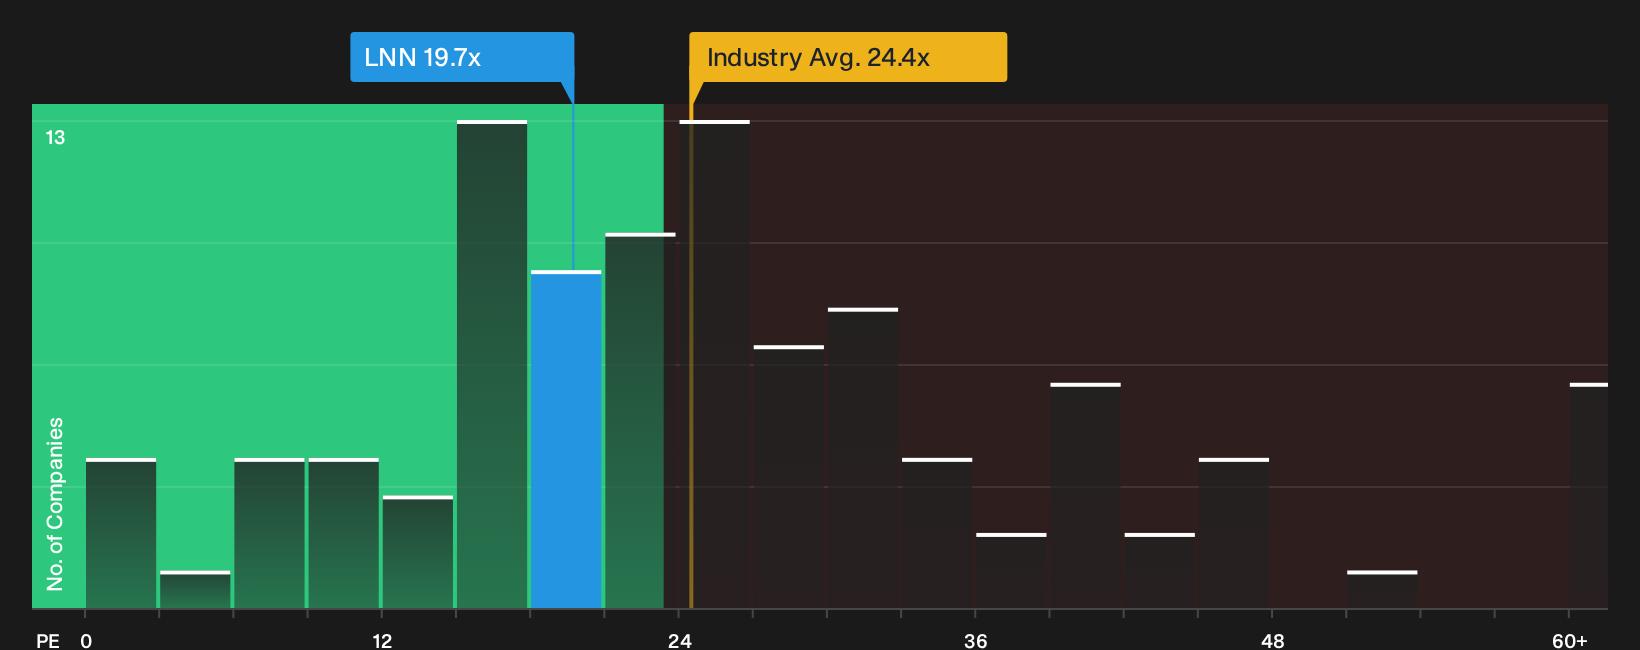
Lindsay might look attractive against intrinsic value, but the current P/E of 19.7x paints a more complicated picture. It is lower than the US Machinery industry average of 24.2x and below a 30x peer average, yet still above the 14.6x fair ratio that the market could move toward over time.
That mix of relative cheapness versus peers and a premium to the fair ratio leaves you with a simple question: Is this pricing a reasonable entry for steady expectations, or extra valuation risk if earnings slip from here?
To stress test that view against hard numbers, take a closer look at how the current price stacks up against earnings using our valuation breakdown, including the fair ratio and peer comparisons, in See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Lindsay can be hard to weigh, so move quickly from headline reactions to your own evidence based view by checking the 3 key rewards.
Looking for more investment ideas beyond Lindsay?
If Lindsay has you thinking differently about valuation and timing, do not stop here. Fresh ideas in other corners of the market could help you prepare your next move.
- Target durable balance sheets that can handle tougher conditions by scanning our 29 resilient stocks with low risk scores to focus on businesses with more resilient profiles.
- Pursue potential mispriced opportunities by reviewing the 19 high quality undiscovered gems that pair solid fundamentals with limited market attention.
- Strengthen your watchlist with quality at a discount by checking the 33 high quality undervalued stocks, filtered for financial strength and valuation support.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com