


EN
How Strong Revenue Will Impact Virbac (ENXTPA:VIRP) Investors
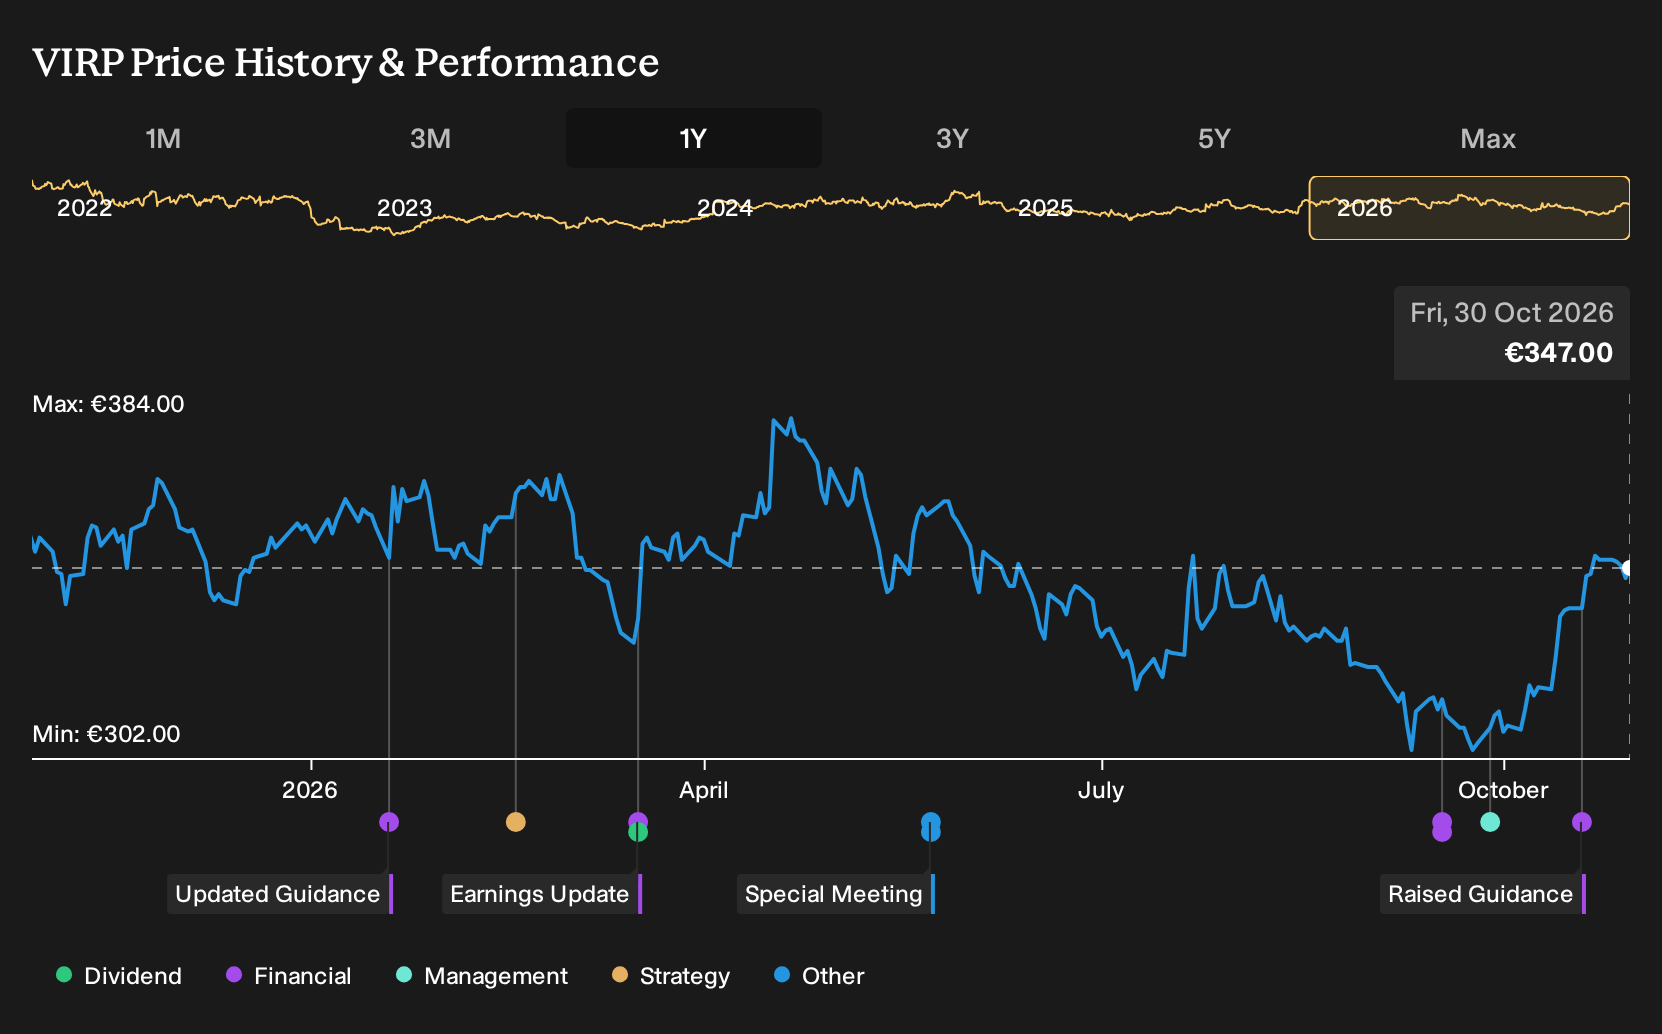
- Virbac SA reported unaudited consolidated revenue of €400 million for the third quarter of 2026 and €1,168 million for the first nine months, compared with €364 million and €1,102 million for the same periods a year earlier, and confirmed 2026 earnings guidance at the upper end of its initial range.
- The combination of higher reported sales over both the quarter and year to date and guidance anchored at the top of management’s target band indicates that Virbac’s operations are currently tracking close to its own internal ambitions on demand and profitability.
- We will now look at how Virbac's stronger reported revenue run rate shapes the broader investment narrative investors have been using.
Spot opportunities riding similar earnings momentum to Virbac by scanning our hand picked 204 high quality undervalued stocks that combine resilient demand with disciplined balance sheets.
Virbac Investment Narrative Recap
To own Virbac, an investor needs to believe the heavy spending on vaccines, petfood and logistics will translate into stronger, higher margin product lines over time, supported by its R&D and omnichannel push. The latest trading statement, with revenue at €400 million for the quarter and €1,168 million year to date, points to demand that appears consistent with that thesis.
The key short term swing factor is whether these higher volumes support profitability as new capacity ramps. Management keeping 2026 guidance at the upper end of the revenue growth range suggests no major change to that near term catalyst. The main immediate risk remains prolonged currency pressure and elevated CapEx weighing on reported margins and free cash flow.
The confirmation that 2026 earnings guidance is anchored at the upper end of the initial revenue growth range of 5.5% to 7.5% at constant exchange and scope is the clearest recent signal to focus on. It ties directly into Virbac’s effort to push more Supercharge platforms, vaccines and petfood through a larger industrial base.
For you as a shareholder or potential buyer, that guidance puts execution on large CapEx projects under the spotlight. The extent to which these facilities support a shift in mix towards higher margin products and omnichannel petfood volumes may help determine how far they offset the currency headwinds and future depreciation charges that currently sit as the main operational overhang.
What The Virbac Analyst Framework Is Really Assuming
Sell side forecasts around Virbac give you a clear checklist of what has to line up for today’s narrative to hold together. Rather than treating the €410.75 consensus target as a black box, it helps to unpack the simple building blocks behind it.
Revenue in these models is set to compound at 6.2% a year over the next few years. That pace effectively ties Virbac’s heavier spending on vaccines, petfood and distribution to a steady expansion of the top line, not a hockey stick. Profitability is assumed to step up as well, with profit margins moving from 10.4% today to 12.5% in three years. This means analysts are baking in a cleaner conversion from sales into earnings as new facilities and Supercharge platforms bed in.
Earnings today sit at €155.9 million and the same group expects that figure to reach €223.9 million by 2029, with earnings per share projected at €26.59. That is a value increase of about €68 million, so the story embedded in the spreadsheets is not just that Virbac grows, but that it grows while lifting margins and holding the share count broadly flat.
Valuation assumptions are relatively modest. The consensus work implies the stock would trade on a P/E of 18.6x in 2029 versus 18.7x now and against 18.7x for the wider GB Pharmaceuticals peer group. In practice, that means the bulk of the analysts’ upside case comes from the earnings line doing the heavy lifting, not from investors paying a dramatically higher multiple for each euro of profit.
Forecasts always carry risk, so treat them as reference points, not certainties. If Virbac struggles to push higher margin franchises through the enlarged industrial base or if foreign exchange and depreciation from its CapEx cycle bite harder than expected, the path to those mid teens margins and 2029 earnings numbers becomes tougher.
Virbac's narrative projects €1.8 billion revenue and €223.9 million earnings by 2029. This setup requires 6.2% yearly revenue growth and an earnings increase of about €68 million from €155.9 million today.
Uncover why Virbac's fair value indicates an 18% potential upside to its current price before the gap starts to close.
Exploring Other Perspectives
Fair value views on Virbac from three Simply Wall St Community members span from €410.75 to about €798.25, so some private investors see almost double the upside of others. Those gaps sit beside real execution questions on heavy CapEx, currency swings and future product launches, which you should weigh before siding with any camp.
Explore 2 other Virbac fair value estimates, including one that suggests as much as 130% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Virbac research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Virbac. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Virbac's overall financial health at a glance.
Looking for more investment ideas beyond Virbac?
Once you have a handle on Virbac, it often helps to compare it with a wider watchlist of businesses that share similar qualities or offer something completely different for your portfolio.
- If you care most about resilient balance sheets and steady fundamentals, start with our list of solid balance sheet and fundamentals (199 results) to see which companies fit that profile.
- For investors who want lower volatility and fewer red flags, filter potential opportunities through our 218 resilient stocks with low risk scores to focus on stocks with more measured risk profiles.
- If you are hunting for underfollowed stories with solid financials, scan our 614 high quality undiscovered gems and widen your opportunity set beyond the usual large caps.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com