


EN
Caledonia Mining (CMCL) Pullback Revives The Debate Over Whether The Stock Is Undervalued
Caledonia Mining (CMCL) has come under pressure recently, with the share price closing at US$20.25 after declines of about 5% over both the past week and the past month.
That recent slide comes after a mixed run for Caledonia Mining, with the share price return down about 16% over the past month but still up around 8% over the last 90 days, while the 1-year total shareholder return is down roughly 26% despite strong 3 and 5-year total shareholder returns of about 88% and 91% respectively. Short term momentum has faded even as long term holders still show a solid gain.
Look beyond Caledonia Mining's recent pullback and evaluate other gold producers that combine resilient balance sheets with earnings power using our curated 34 elite gold producer stocks
For Caledonia Mining, that pullback could hint at deeper worries about its Zimbabwe focused gold assets, or it could simply reflect investors rotating away after strong multi year gains. The valuation numbers will show which story fits.
Most Popular Narrative: 59% Undervalued
Caledonia Mining last closed at $20.25, while the most followed narrative pegs fair value closer to $49.43. This is a wide gap for any gold producer and frames the debate around whether the market is discounting risk or misreading the underlying assets.
Caledonia Mining Corporation (NYSE: CMCL) currently trades near $24.00 with a market capitalization of roughly $480 million, presenting a stark divergence between its robust cash generation and its politically discounted equity valuation. With FY 2025 revenue surging 46% to $267.7 million, EBITDA reaching $125.3 million, and a transition to a net cash position of $23.8 million, the fundamental baseline is mispriced relative to global peers.
See why 5 investors see Caledonia Mining as 59% undervalued.
Result: Fair Value of $49.43 (UNDERVALUED)
Still, the Caledonia Mining narrative could unravel if Zimbabwe specific regulatory or currency pressures intensify, or if outcomes from the Bilboes development fall short of expectations.
Find out about the key risks to this Caledonia Mining narrative.
Another View: SWS DCF Model Challenges The Narrative
The crowd story on Caledonia Mining leans on a $49.43 fair value, yet the SWS DCF model points in a very different direction. On that cash flow view, the stock at $20.25 trades above an estimated $13.07 value, which frames it as overvalued rather than discounted. Which lens do you trust when the signals conflict this sharply?
Look into how the SWS DCF model arrives at its fair value.
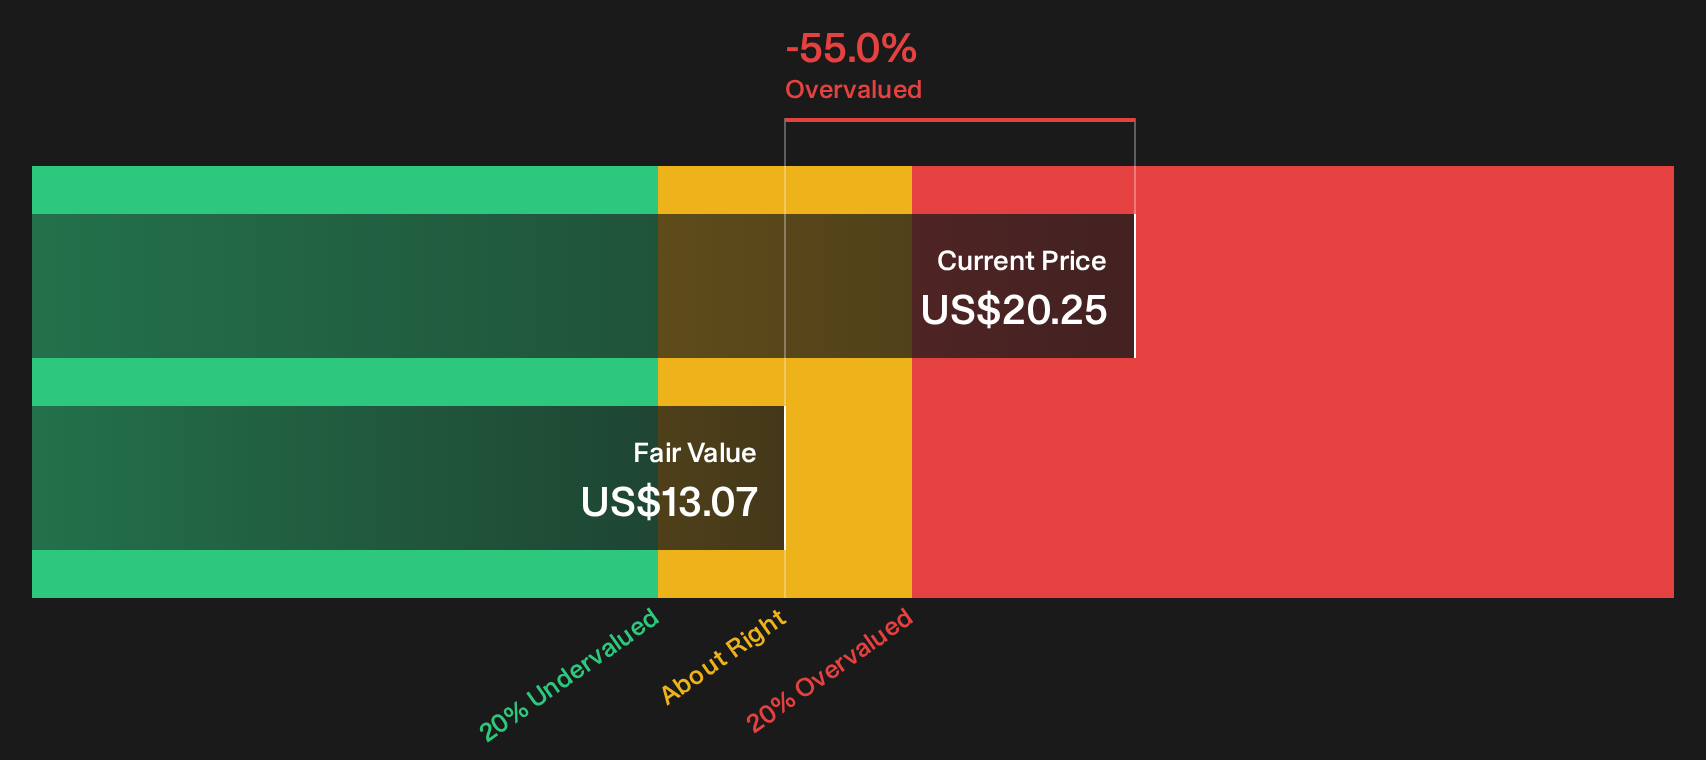
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Caledonia Mining for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
The split between the crowd narrative and the SWS model leaves the sentiment around Caledonia Mining wide open. Act quickly, review the underlying numbers for yourself, and weigh those potential bright spots using the 6 key rewards.
Looking for more investment ideas beyond Caledonia Mining?
If Caledonia Mining has your attention, do not stop there. Use focused screeners to spot other opportunities that fit your risk, income, and quality preferences.
- Target resilient compounders by scanning companies with strong cash generation and disciplined valuations through the 33 high quality undervalued stocks.
- Build a steadier income stream by focusing on businesses that offer higher yields and consistent payouts using the 5 dividend fortresses.
- Guard against blowups by filtering for financially robust operations with low-risk profiles via the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com