


EN
How Investors May Respond To MGM Resorts International (MGM) Profit Miss
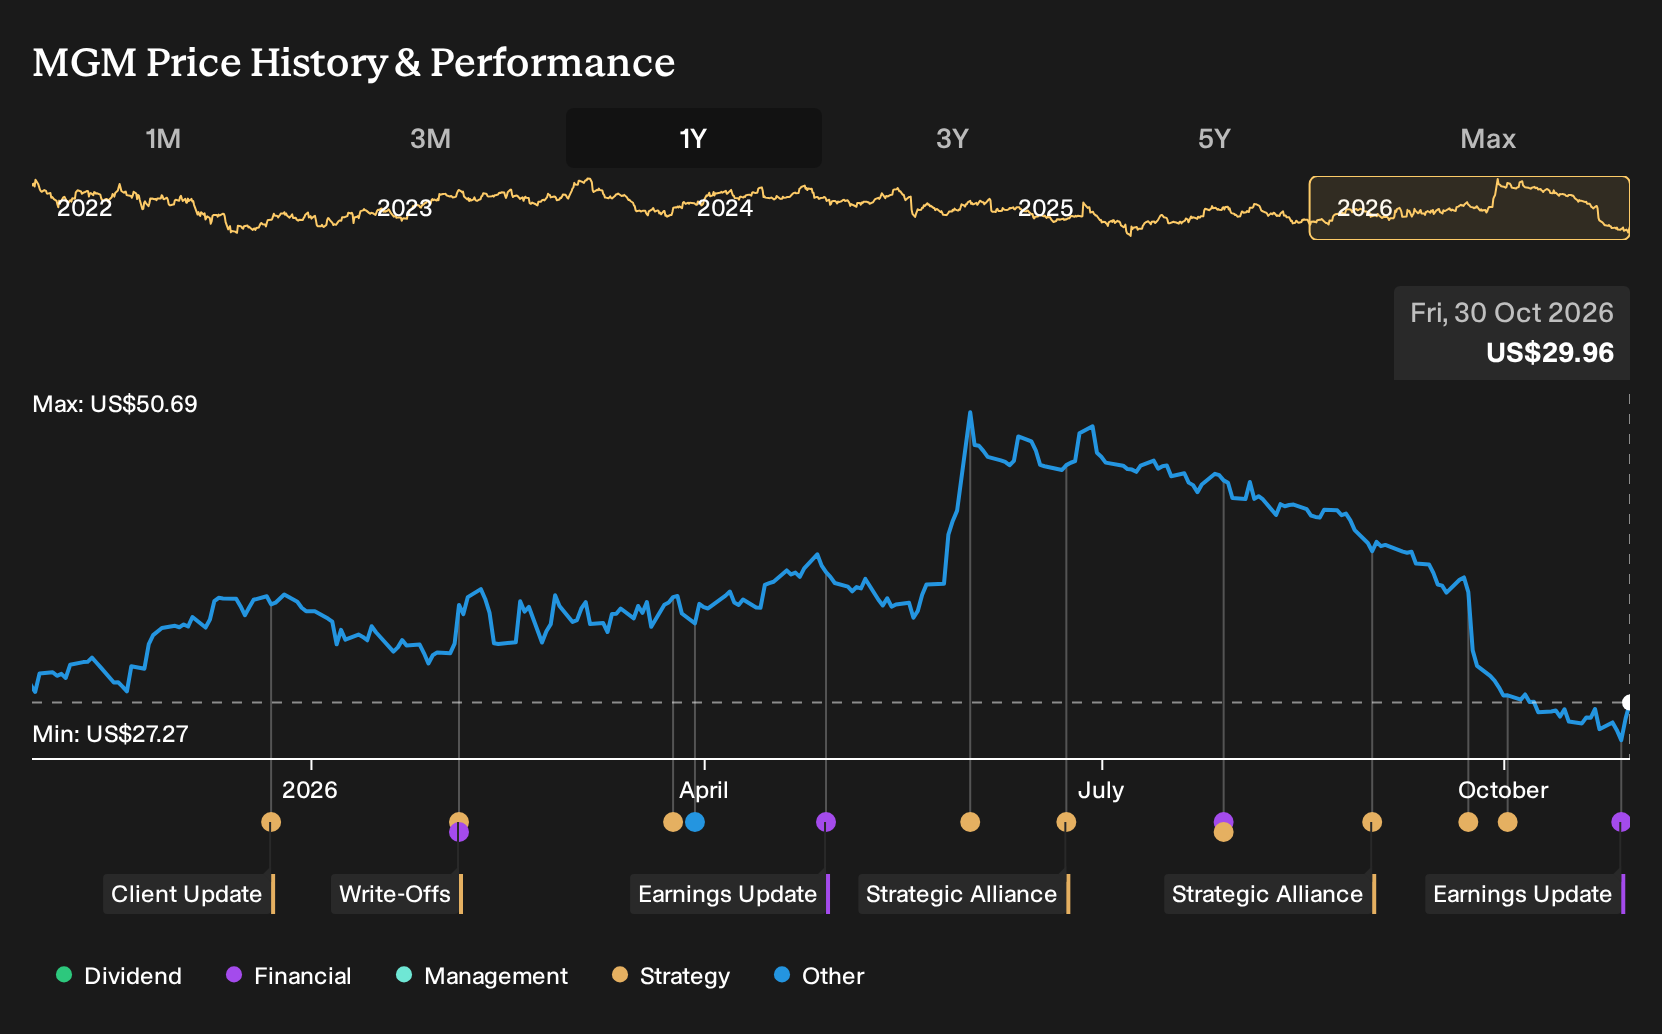
- MGM Resorts International reported third quarter 2026 revenue of US$4.21b and a net loss of US$17.11 million, with earnings for the first nine months of 2026 at US$400.46 million.
- The swing from a net loss in the prior nine month period to positive earnings, alongside pressure on adjusted profitability, highlights how MGM Resorts International is balancing casino performance with rising costs and travel related headwinds.
- The focus now turns to how MGM Resorts International's weaker adjusted profitability in this quarter could influence the existing investment narrative.
Scan how MGM Resorts International stacks up against a hand picked group of companies balancing earnings swings with resilient demand using the 33 high quality undervalued stocks.
MGM Resorts International Investment Narrative Recap
For an investor to stay with MGM Resorts International, the core belief is that steady demand in Las Vegas, regional casinos, Macau and digital betting can offset cost pressure and debt service. The latest quarter shows that story is intact on activity, with revenue broadly stable, but weaker adjusted profitability keeps the focus firmly on expenses and insurance related drag.
The key near term swing factor is how quickly MGM Resorts International can rebuild margin quality after this softer quarter, while still funding projects such as Osaka and premium upgrades in Macau. The biggest risk remains high leverage, with interest coverage already flagged as tight if earnings lose momentum.
The most relevant disclosure for this earnings update is the nine month 2026 income statement. MGM Resorts International moved from a net loss of US$87.75 million a year earlier to net income of US$400.46 million, on revenue of US$13.12b. That turn to profitability gives management more room to keep investing across Vegas, Macau and digital initiatives.
For catalysts, that improved year to date profit base matters because projects like the Osaka resort and MGM Digital expansion require meaningful capital while self insurance costs and legal exposures sit in the background. Investors tracking MGM Resorts International will likely weigh that higher earnings run rate against ongoing debt of about US$30.02b and interest payments that are not yet comfortably covered.
MGM Resorts International's analyst narrative points to forecast revenue of US$19.3b and earnings of US$340.0 million by 2029, based on an assumed 2.8% yearly revenue growth rate and a projected earnings decline of US$359.3 million from US$699.3 million today.
Uncover why MGM Resorts International's fair value indicates a 32% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view focuses less on Osaka or Macau and more on MGM Resorts International’s legal and self insurance burden. The most cautious analysts were already assuming fairly flat revenue at about US$17.9b by 2029 and earnings of roughly US$540.8 million. After this earnings miss on profitability, those already tough assumptions may shift again. Explore the full range of scenarios before deciding how this update fits your own thesis.
Explore 6 other MGM Resorts International fair value estimates, including one that suggests there may be as much as 7% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your MGM Resorts International research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for MGM Resorts International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MGM Resorts International's overall financial health at a glance.
Looking for more MGM Resorts International sized investment ideas?
Once you have formed a view on MGM Resorts International, it can help to compare it with other stocks that fit clear financial themes using the Simply Wall St Screener.
- For investors who care most about financial resilience and low leverage, start with a list of solid balance sheet and fundamentals (24 results) that can help you focus on sturdier businesses.
- If your priority is limiting downside risk, filter the market by stability and consistency using a 29 resilient stocks with low risk scores that keeps volatility in check.
- When you want to expand your watchlist beyond well known tickers, widen the search with a 19 high quality undiscovered gems that surfaces under followed companies with strong fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com