


EN
Will Raised 2027 Guidance Change Agilysys Stock Narrative
- Agilysys reported second quarter revenue of US$93.36 million and net income of US$13.18 million, and then raised full year 2027 revenue and subscription growth guidance after the period ended September 30, 2026.
- The business also highlighted that 8 of the 10 casino resorts on AAA’s new Diamond Top 10 Casino Hotel List already run on the Agilysys ecosystem, which underscores how deeply its software is embedded in complex hospitality operations.
- We will now look at how Agilysys' investment narrative could be affected by stronger earnings and higher full year subscription growth guidance.
Scan how Agilysys' hospitality footprint compares with other potential breakout opportunities by reviewing our hand picked list of 19 high quality undiscovered gems.
Agilysys Investment Narrative Recap
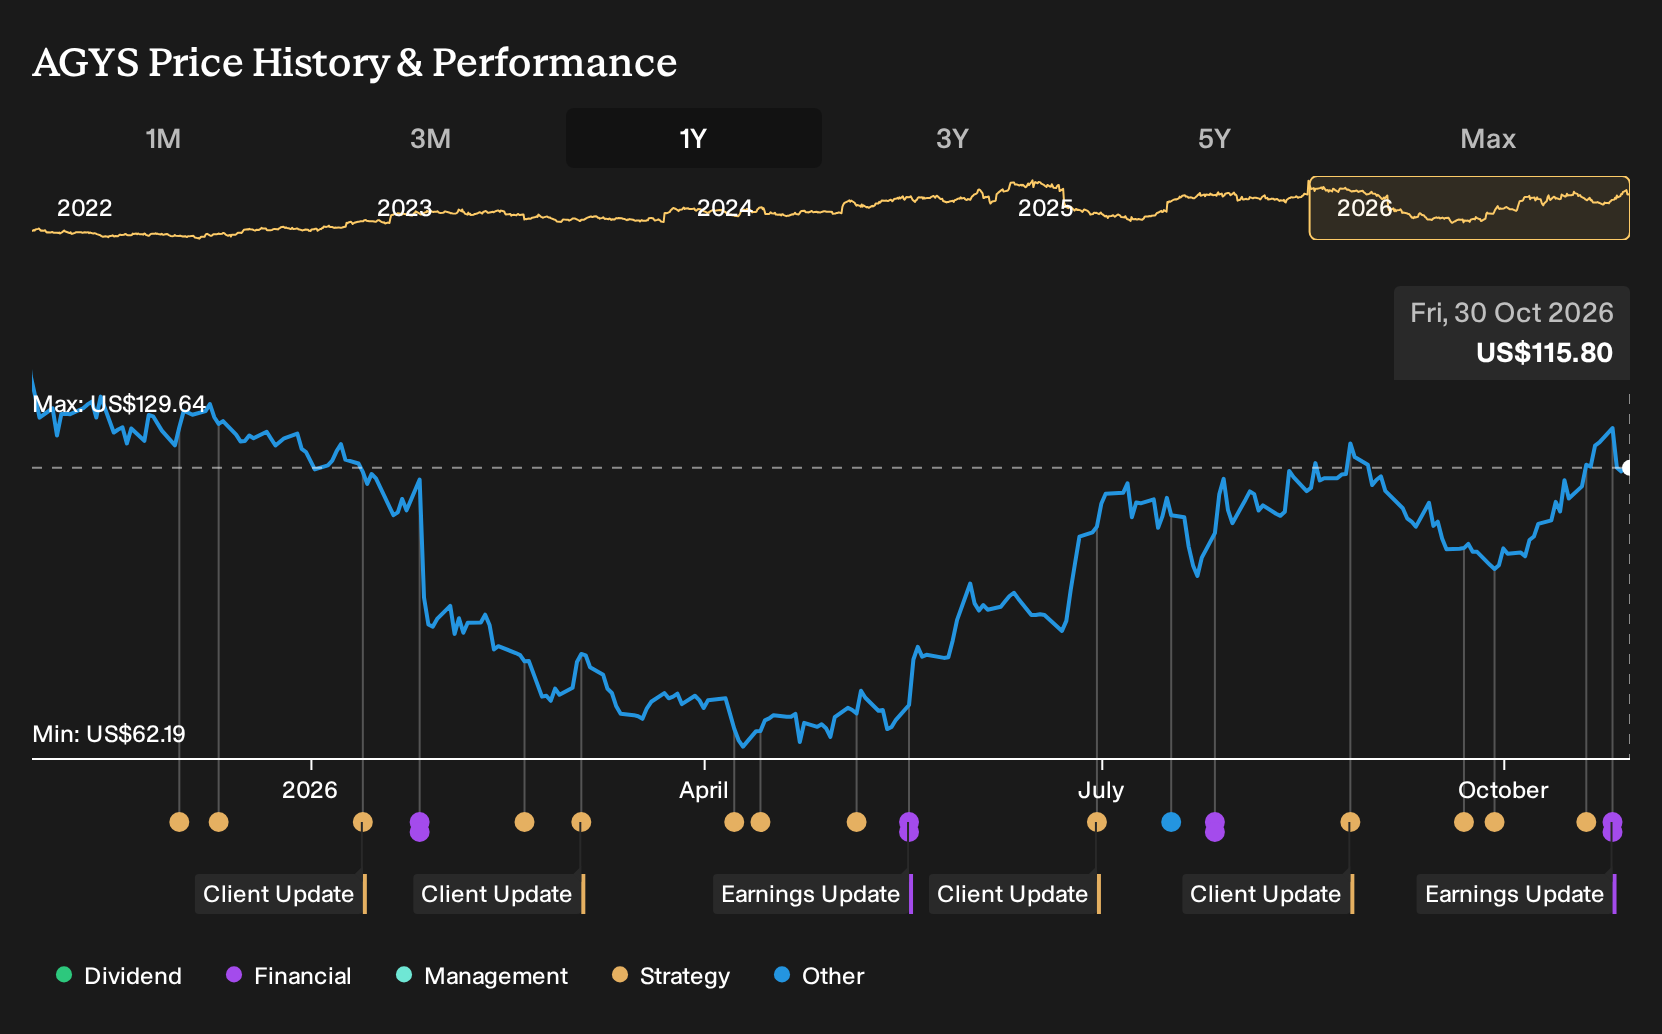
To stay a shareholder in Agilysys you need to believe that hospitality operators will keep standardising on its software stack and keep adopting its subscription contracts. The raised full year 2027 guidance, with revenue now guided to US$374 million to US$378 million and subscription growth expected at least 34%, supports that subscription shift as the key near term catalyst.
The biggest operational risk is still concentration in hospitality and especially casinos and resorts. Any slowdown in openings, refurbishments or tech refresh cycles could hit bookings and make quarterly results bumpier again. The latest earnings do not remove that exposure; they just show the firm executing well against current demand.
The guidance increase on October 26 is the clearest operational signal to focus on. Management moved full year revenue expectations up for a second time this fiscal year and lifted subscription growth guidance from at least 30% to at least 34%. That ties directly to the recurring revenue story many Agilysys investors are watching.
Higher subscription growth, if delivered, could help smooth earnings and give the business more room to work on margin issues that some analysts flag versus software peers. It also raises the bar. If hospitality demand softens or large rollouts slip, the risk of disappointment against that higher guidance becomes an important near term factor.
Agilysys' current analyst storyline points to revenue of US$557.0 million and earnings of US$104.5 million by 2029, based on an assumed 17.4% yearly revenue growth rate and a move in profit from US$44.4 million today to that 2029 consensus. This implies an earnings increase of about US$60.1 million over the period.
Uncover why Agilysys' fair value indicates a 23% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view on Agilysys focuses less on hospitality concentration risk and more on margin pressure. The most cautious analysts were pencilling in revenue of about US$532.5 million and earnings of US$106.3 million by 2029, yet still only saw a US$135.0 target. That gap shows how far opinions can differ. It therefore helps to explore several competing narratives that may shift after this latest guidance and earnings update.
Explore 4 other Agilysys fair value estimates, including one that suggests as much as 83% downside from the current price!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Agilysys research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Agilysys. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Agilysys' overall financial health at a glance.
Looking For More Investment Ideas Beyond Agilysys?
If Agilysys has sharpened your appetite for quality research, it can help to benchmark it against a broader watchlist built from clear financial filters. The Simply Wall St Screener lets you move from one story stock to a full pipeline of candidates that match your preferred mix of strength, resilience and income.
- For investors who want financial resilience and less balance sheet strain, start with companies that qualify for our 29 resilient stocks with low risk scores and see which ones fit your comfort level.
- If you are hunting for strong fundamentals and clean financing, build a shortlist from the list of solid balance sheet and fundamentals (24 results) to compare against Agilysys' profile.
- For readers who focus on finding quality that the market may have overlooked, scan the 19 high quality undiscovered gems to spot other potential candidates before they are widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com