


EN
Japan Hotel REIT Investment (TSE:8985) Has A Fresh Update, So What Is Drawing Attention?
Japan Hotel REIT Investment (TSE:8985) has put income on the table by announcing an annual dividend of ¥5,811 per unit, together with new operating and revenue figures for the period to September 2026.
Against this backdrop, Japan Hotel REIT Investment’s 1 month share price return of 3.95% and 3 month gain of 3.44% suggest momentum has been picking up recently. This comes even though the 1 year total shareholder return slipped 0.39%, while the 5 year total shareholder return reached 47.97%.
Scan income-focused real estate opportunities by lining up Japan Hotel REIT Investment against 28 dividend fortresses, which is built to highlight steady cash generation and balance sheet strength.
Bulls point to Japan Hotel REIT Investment’s fresh dividend and steady hotel metrics. Bears focus on softer net income growth. Which story does the current unit price reflect as the valuation numbers line up next?
Price-to-Earnings of 19x: Is it justified?
On valuation, Japan Hotel REIT Investment changes hands at a P/E of 19x, while the last close price sits at ¥84,200 and peers and the wider hotel REIT group trade on lower earnings multiples.
The P/E ratio compares the current unit price to earnings per unit. For hotel focused real estate investment trusts like Japan Hotel REIT Investment, it is often used as a quick shorthand for how much investors are prepared to pay for each unit of profit from the portfolio.
Here, the trust is described as expensive on three fronts. The 19x P/E is above the global Hotel and Resort REITs average of 11.6x, it is above the peer group average of 15.5x, and it also sits slightly above an estimated fair P/E of 18.7x that the market could move towards if pricing adjusts.
Explore the SWS fair ratio for Japan Hotel REIT Investment.
Result: Price-to-Earnings of 19x (OVERVALUED)
Still, softer annual net income growth of 4.0% and a recent 1 year total return that slipped 0.39% leave room for sentiment on Japan Hotel REIT Investment to cool.
Find out about the key risks to this Japan Hotel REIT Investment narrative.
Another View: Cash Flow Points To Undervaluation
The earlier P/E check portrayed Japan Hotel REIT Investment as expensive. The SWS DCF model presents a different view. On that framework, units trading at ¥84,200 are described as being below an estimated future cash flow value of ¥103,396.37, which presents the trust as undervalued instead. That split in signals raises a simple question: which lens do you rely on more when cash flows indicate cheap but earnings multiples indicate rich?
Look into how the SWS DCF model arrives at its fair value.
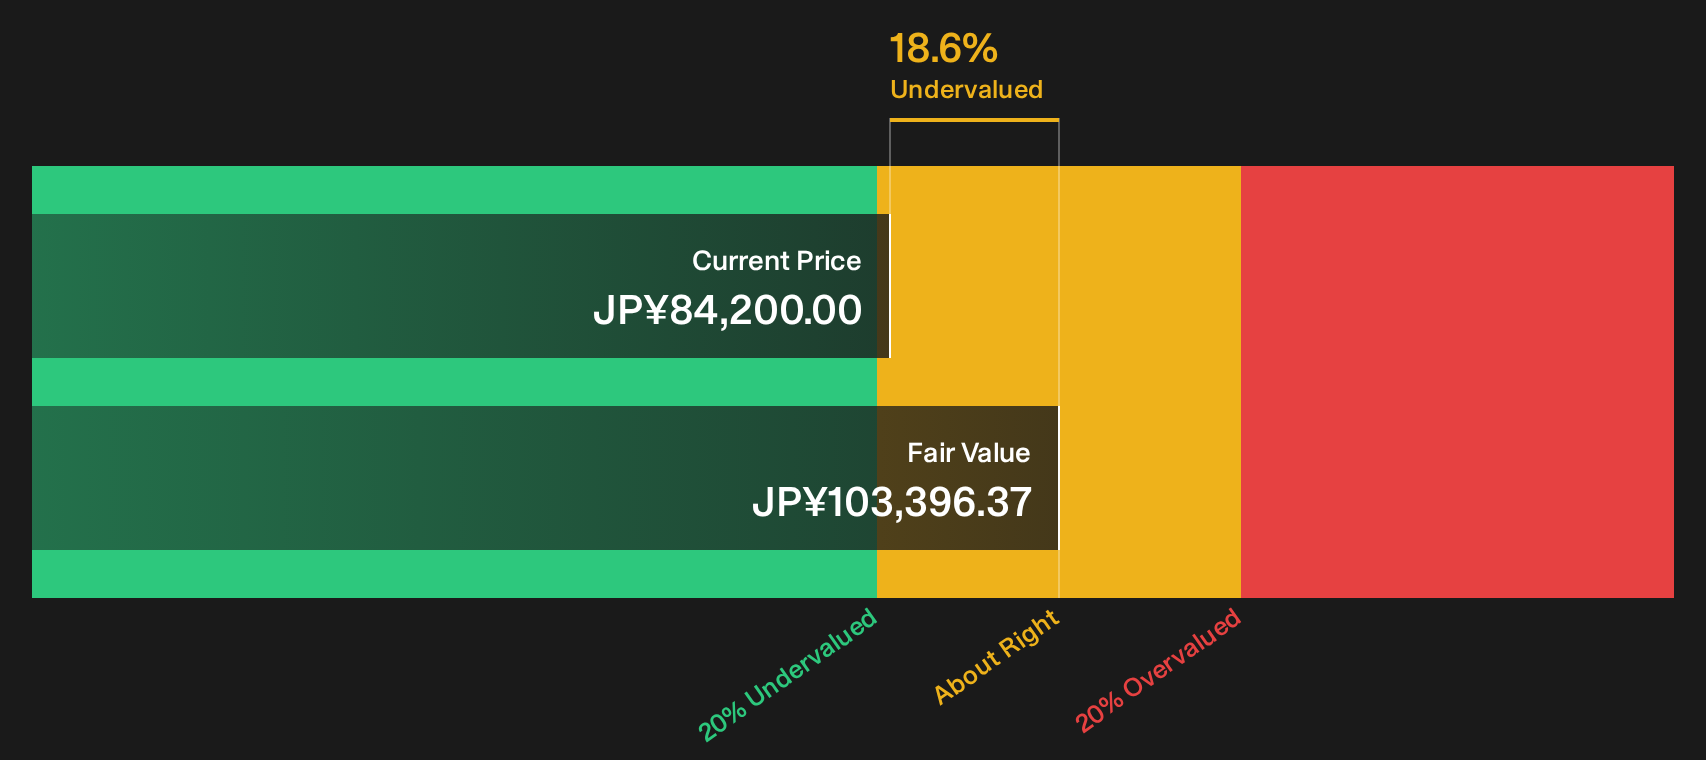
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Japan Hotel REIT Investment for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 16 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Japan Hotel REIT Investment are clear, so now is the moment to check the details yourself and decide what matters most. To weigh both sides properly, take a closer look at the 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Japan Hotel REIT Investment?
Do not stop with one trust. Broaden your watchlist with other stocks that fit your income, quality, and risk profile using focused screeners on Simply Wall St.
- Target reliable payouts by lining up yield opportunities through the 28 dividend fortresses that highlights companies with stronger income profiles.
- Hunt for pricing gaps by scanning the 16 high quality undervalued stocks that focuses on businesses trading below their assessed fundamental strength.
- Prioritise resilience by filtering candidates using the 23 resilient stocks with low risk scores so capital is focused where volatility appears more controlled.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com