


EN
Learn Why The Bull Case For Stoke Therapeutics Stock Could Change Following Phase III Trial Progress
- Stoke Therapeutics reported Q3 2026 sales of US$11.26 million with a significantly larger net loss of US$73.64 million, while reiterating long timelines to pivotal data and a potential filing for zorevunersen in Dravet syndrome.
- The combination of modest current revenue and heavier losses against multi year development plans keeps attention squarely on Stoke Therapeutics' funding needs and execution in late stage trials.
- Now the focus shifts to how Stoke Therapeutics' widening losses, alongside Phase III Dravet progress, could reshape the longer term investment narrative.
Stoke Therapeutics Investment Narrative Recap
To own Stoke Therapeutics, you have to buy into a high risk, high effort path toward a first commercial drug in Dravet syndrome and possibly a platform around haploinsufficiency diseases. The latest quarter reinforces that this is an operating story focused on cash burn and execution, not profitability. Widening Q3 and year to date losses highlight the cost of late stage neurology trials and early pipeline build out.
The key near term catalyst is clear. Investors are watching the Phase III EMPEROR readout for zorevunersen and the planned U.S. filing in 2027. The bigger risk is that extended losses and development spend, without near term revenue support, could lead to tougher funding decisions if trial timelines or regulatory reviews extend beyond current plans.
The most relevant update tied to this earnings season is management reiterating progress and timing for the EMPEROR Phase III trial in Dravet syndrome. Data are still expected in the third quarter of 2027, followed by a potential U.S. submission later that year, with Stoke Therapeutics also emphasizing strong patient retention and regulatory alignment on cognition and behavior measurement using Vineland 3.
That clarity matters because it frames how long investors may be funding losses before any Dravet therapy can be evaluated commercially. With Q3 2026 results showing modest sales against a much larger net loss, the operational question becomes whether Stoke can keep EMPEROR and the STK 002 OSPREY study on schedule while managing cash needs, possible dilution, and execution risk across two high complexity neurology and ophthalmology programs.
Stoke Therapeutics' consensus narrative points to revenues of US$177.8 million and earnings of US$33.6 million by 2029, based on analyst assumptions of 77.0% yearly revenue growth and an earnings swing of roughly US$203.4 million from a loss of US$169.8 million today to projected profit.
Uncover why Stoke Therapeutics' fair value indicates a 72% potential upside to its current price before that gap closes.
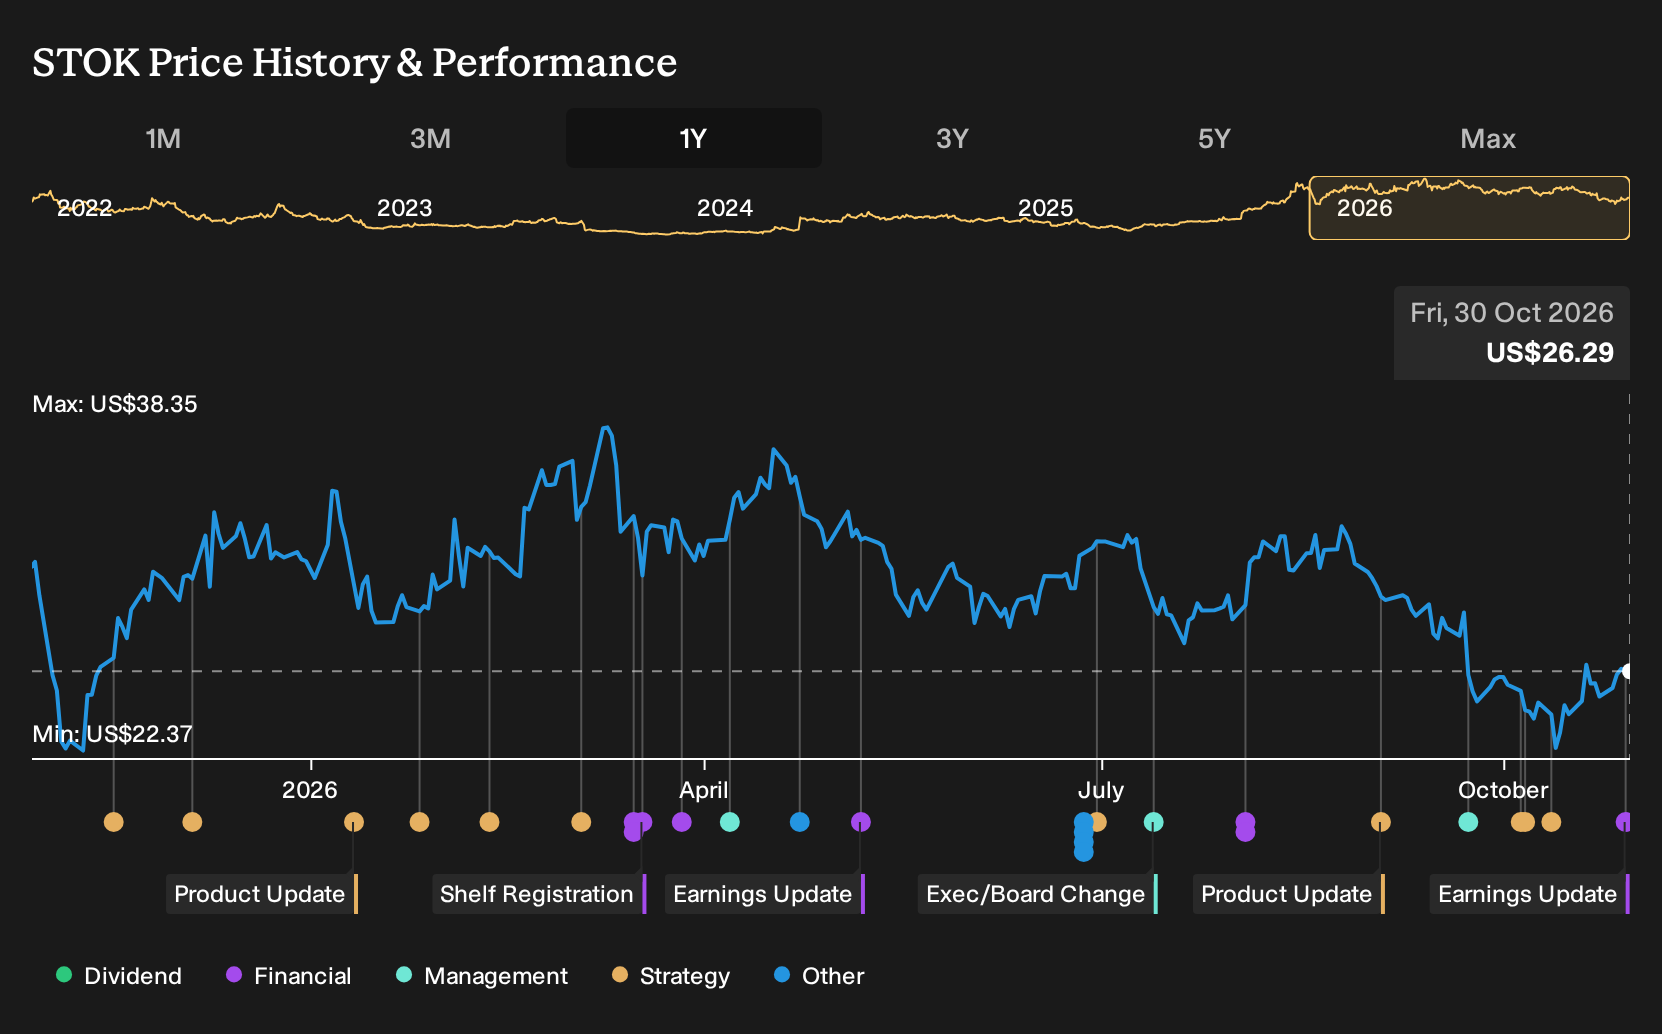
Exploring Other Perspectives
One contrasting angle you might explore is how bullish analysts lean hard into the long term revenue story. Before this Q3 2026 report, the most optimistic forecasts were looking for about US$331.2 million of revenue and US$52.7 million of earnings by 2029. That is a far more upbeat Stoke Therapeutics narrative, and fresh results could lead those views to evolve.
Explore 3 other Stoke Therapeutics fair value estimates, including one that suggests potential upside of up to 1151% from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Stoke Therapeutics research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Stoke Therapeutics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Stoke Therapeutics' overall financial health at a glance.
Looking for more Stoke Therapeutics sized investment ideas?
If the Stoke Therapeutics story has you thinking about position sizing, risk and timing, it can help to widen the lens and compare it with other companies that fit very different profiles. Use the Simply Wall St Screener to scan a broader universe, then pressure test your own thesis against alternatives that may better match your risk tolerance and time horizon.
- For investors hunting for under-appreciated quality, start with companies that pair solid balance sheets with decent fundamentals through the list of solid balance sheet and fundamentals (24 results).
- If income is a priority, look at businesses offering higher yields and steadier cash returns using the 5 dividend fortresses.
- When you want potential upside but prefer a more resilient profile than early stage biotech, filter for companies with lower overall risk scores via the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com