


EN
What Waters Doubters Got Wrong
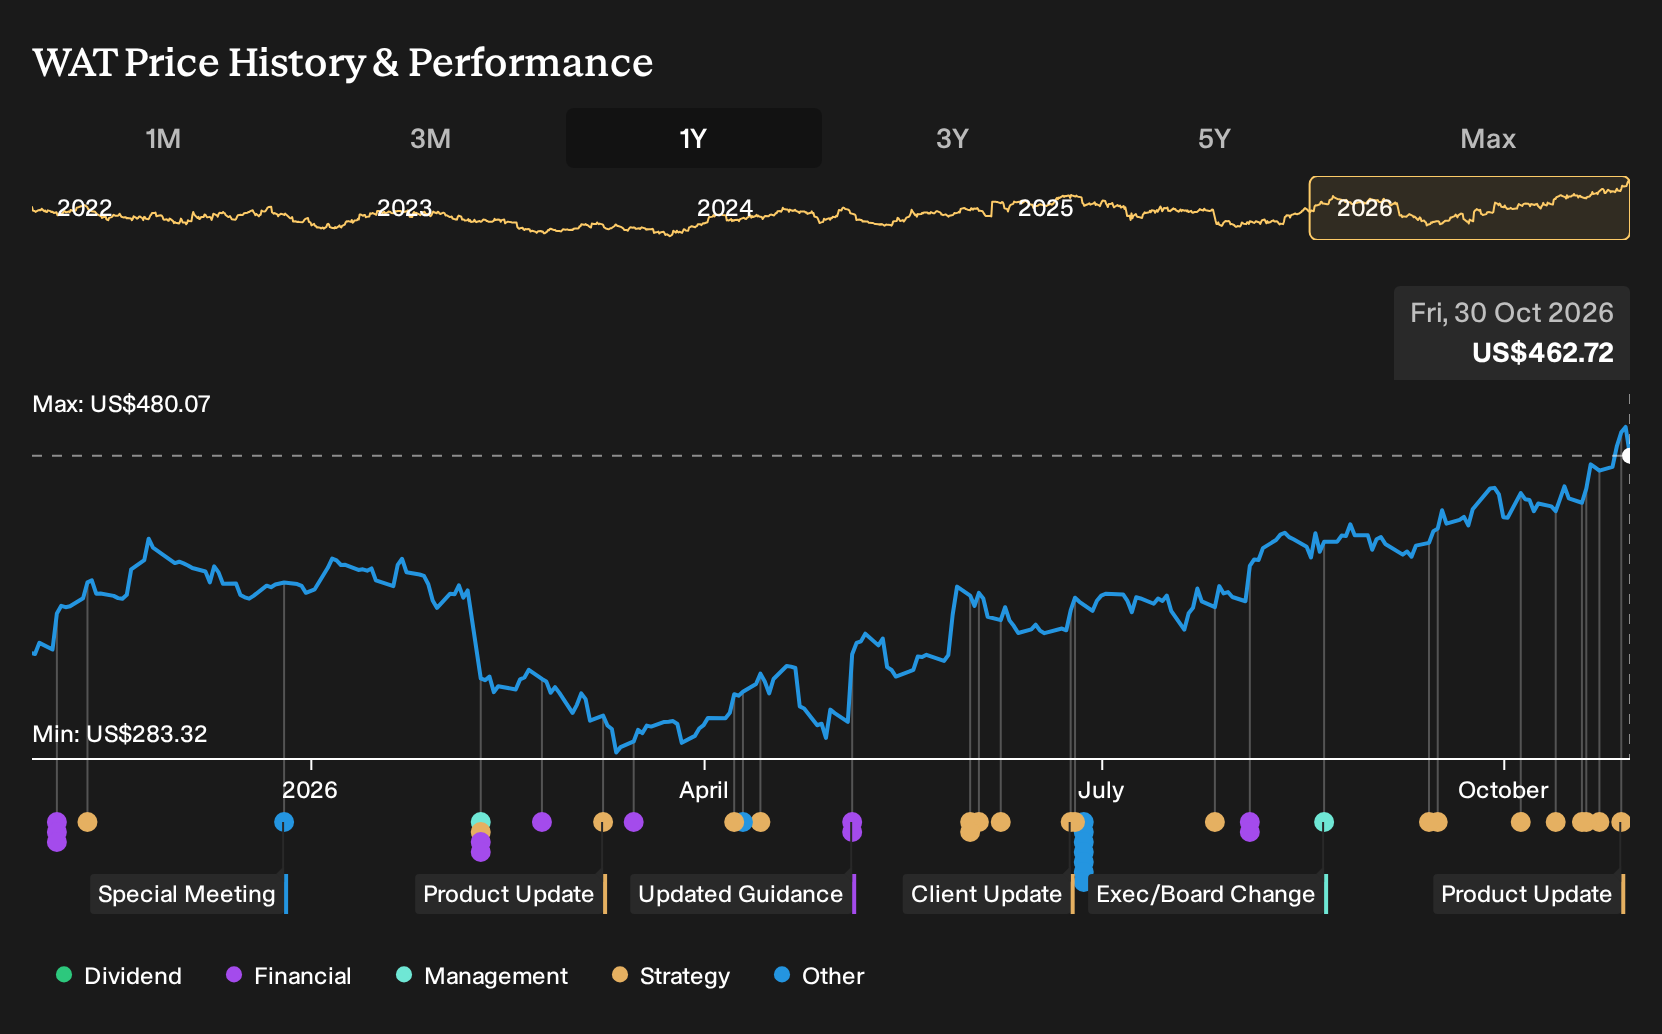
If Waters had been on your watchlist instead of in your portfolio, the outcome over the past year may feel like a missed shot. Holding Waters over the past year would have returned 32.4%, including dividends. That kind of payoff raises a simple question. Back on 30 October 2025, when bulls talked up LC-MS upgrades and biotech expansion as a secular healthcare play, what clues suggested that assumption might actually be right?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
Waters has already moved. Pinpoint other ways to investigate the theme among 34 healthcare AI stocks.
The Two Waters Narratives Investors Were Weighing
The shares cost US$343 at the start of the period, and anyone looking at Waters then had to decide which story felt more plausible.
The bullish narrative put fair value at US$424, based on the idea that LC-MS upgrades and biotech demand could support 7.0% annual revenue growth and a future P/E of 33.1x.
The bearish view set fair value at US$300, reflecting concerns that pharma cost controls and acquisition integration risks might hold growth nearer 5.9% with a future P/E of 23.4x.
What The Results Changed For The Waters Argument
Waters closed Q2 2026 with revenue of US$1.645b versus US$771m a year earlier, helped by the BD Biosciences and Diagnostic Solutions acquisition, which leans toward the bullish demand story. Profit told a different tale. The business swung from US$147m earnings to a loss of US$136m and net margin moved from 19.1% to a loss of 8.3%. The evidence cut both ways.
The key assumption under the microscope was that acquisitions and product launches would lift both scale and profitability. When you assess another stock with a similar pitch, track whether revenue, absolute profit and net margin move in the same direction after big deals or product cycles, rather than treating higher sales alone as confirmation.
What Waters' Current Price Already Assumes
Waters now trades at US$463 after a 32.4% gain over the past year. The selected Narrative judges its Fair Value to be below that level, mainly because it sees execution and integration hurdles rather than broad demand as the key swing factors.
At this price, a buyer is effectively assuming smooth integration of the BD carve outs, durable high single digit organic growth and strong AI software uptake. The question is how that assumption holds up against the Narrative's concerns about integration strain, legacy product reliance and China exposure.
"The current valuation implies that Waters' multi-year LC/LC-MS replacement and reshoring cycle, Empower and AI software adoption, and the turnaround in acquired BD businesses will translate into durable high single digit growth, expanding margins from synergy capture, and a premium multiple that already prices in these outcomes."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Looking Beyond Waters' Instruments
Waters points you toward laboratories, complex workflows and growing data streams. You can also look one step sideways.
All that testing power still relies on heavy computing, storage and secure connectivity. Those needs stay important long after experiments finish.
Another large specialist focuses directly on that digital plumbing. It builds hardware and software that help customers move, process and manage information at scale.
Think of it as the infrastructure behind your infrastructure. As demand for careful data handling broadens, its role may quietly feel more central.
One Narrative has put that dependency into a written case. → See the AI infrastructure company one Narrative values 100% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com