


EN
Is Quarterly Earnings Altering The Investment Case For Burke & Herbert Financial Services Stock?
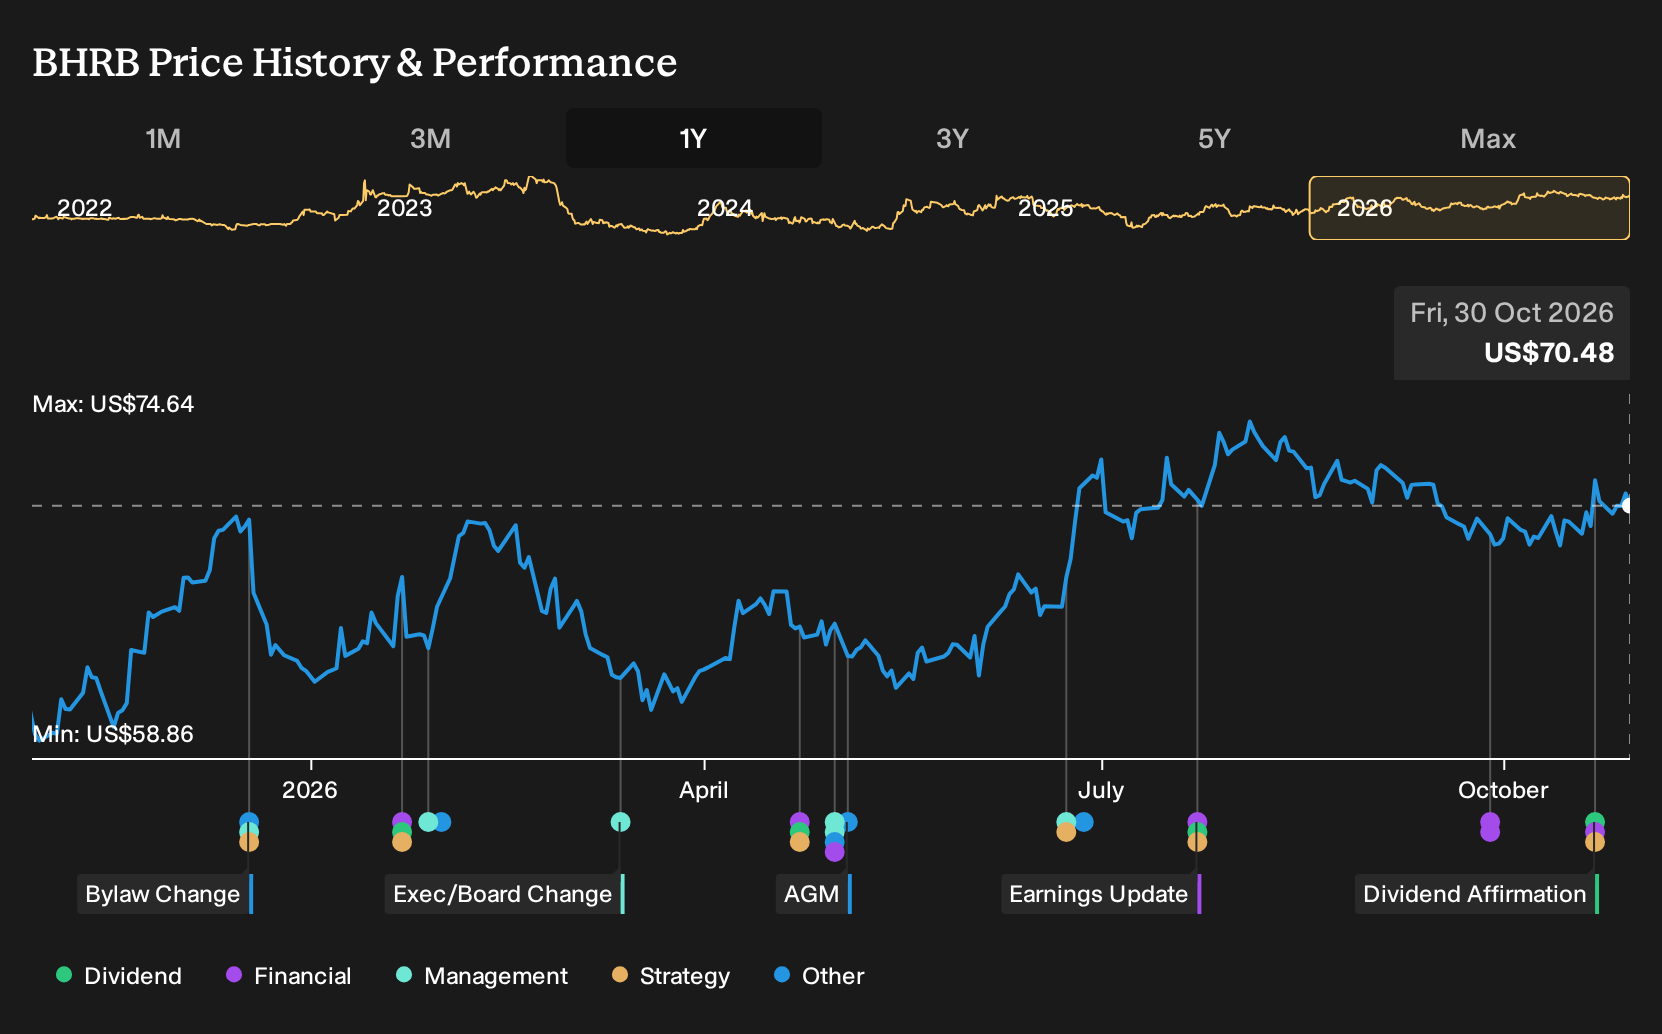
- Burke & Herbert Financial Services reported third quarter 2026 results with net interest income of US$105.02 million and net income of US$36.39 million, and the Board declared a regular quarterly dividend of US$0.55 per share payable on December 1, 2026.
- The bank recorded net loan charge offs of US$2.87 million in the third quarter compared with US$226,000 a year earlier, highlighting rising credit costs despite higher net interest income and net income.
- Now the focus turns to how Burke & Herbert Financial Services' higher net interest income, alongside steeper loan charge offs, could shape its investment narrative.
What Is Burke & Herbert Financial Services' Investment Narrative?
To own Burke & Herbert Financial Services, you need to be comfortable with a straightforward community banking story that leans on spread income, disciplined expense control and a dividend that is intended to be consistent rather than flashy. The third quarter print reinforces that setup. Net interest income of US$105.02 million and net income of US$36.39 million indicate that the engine is still credit and deposits, even as basic EPS from continuing operations of US$1.79 trails last year. In effect, you are relying on management to convert forecast revenue and earnings growth into steady returns without needing constant reinvention.
The fresh US$0.55 dividend declaration keeps the income angle intact in the near term and signals the board’s comfort with current capital and earnings power. The catch is on the risk side. Net loan charge offs climbed to US$2.87 million in the quarter while the allowance for bad loans sits at 86%, and there has been substantial shareholder dilution over the past year. Those trends can matter more to the equity story than a 1.4% discount to estimated fair value if credit quality or funding costs change.
Even so, there is a less obvious pressure point in Burke & Herbert Financial Services' setup that only really shows up when you look at ...
There's only one way to know the right time to buy, sell or hold Burke & Herbert Financial Services. Head to Simply Wall St's company report for the latest analysis of Burke & Herbert Financial Services's Fair Value.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Burke & Herbert Financial Services research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Burke & Herbert Financial Services. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Burke & Herbert Financial Services' overall financial health at a glance.
Looking For More Investment Ideas Beyond Burke & Herbert Financial Services?
If you want to cross check Burke & Herbert Financial Services against a wider opportunity set, the Simply Wall St Screener can help you quickly narrow the field to stocks that better fit your risk, income, or value preferences.
- If capital preservation sits near the top of your checklist, start with a curated group of companies that show resilient balance sheets and low risk scores through the 29 resilient stocks with low risk scores.
- If you prefer to let the numbers point you toward potential value, use the screener to zero in on 33 high quality undervalued stocks that combine stronger cash flows with sturdier financial footing.
- If income is a key part of your plan, aim your search at businesses that pair higher yields with an emphasis on sustainability by scanning through 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com