


EN
Carvana (CVNA) Earnings And Guidance Put Its Valuation Narrative Back In Focus
Carvana (CVNA) is in focus after reporting record third quarter revenue of US$8.04b and higher net income of US$289m, alongside upbeat guidance that pointed to further gains in retail units sold.
Carvana's share price has moved sharply over shorter periods, with a 7 day share price return of 18.1% and a 30 day gain of 7.1%. However, the year to date share price return is down 14.7%, while the 3 year total shareholder return is close to 10x, indicating strong longer term momentum despite recent volatility.
Scan how Carvana stacks up against other high momentum retailers by checking our curated list of 19 high quality undiscovered gems that have strong fundamentals backing their recent moves.Bulls point to Carvana's record revenue, stronger earnings, and upbeat guidance. Bears focus on a sharp multi-year run in the share price and a rich implied valuation. The key question is which side the current numbers support next.
Most Popular Narrative: 16% Undervalued
Carvana's most followed narrative anchors fair value at $80.86, a touch above the recent $68.29 close. This places the current move inside a valuation story driven by execution on growth and profitability rather than short term trading alone.
The continued move toward buying cars online, with auto e-commerce still in the low single digits compared with roughly 20% for retail overall, gives Carvana room to keep taking digital share, which can support unit growth and revenue expansion.
See why 56 investors see Carvana as 16% undervalued.
Result: Fair Value of $80.86 (UNDERVALUED)
Still, Carvana’s narrative can be knocked off course if inventory expansion continues to lag sales or if pressure on gross profit per unit persists.
Find out about the key risks to this Carvana narrative.
Another View: Carvana Looks Expensive On Earnings
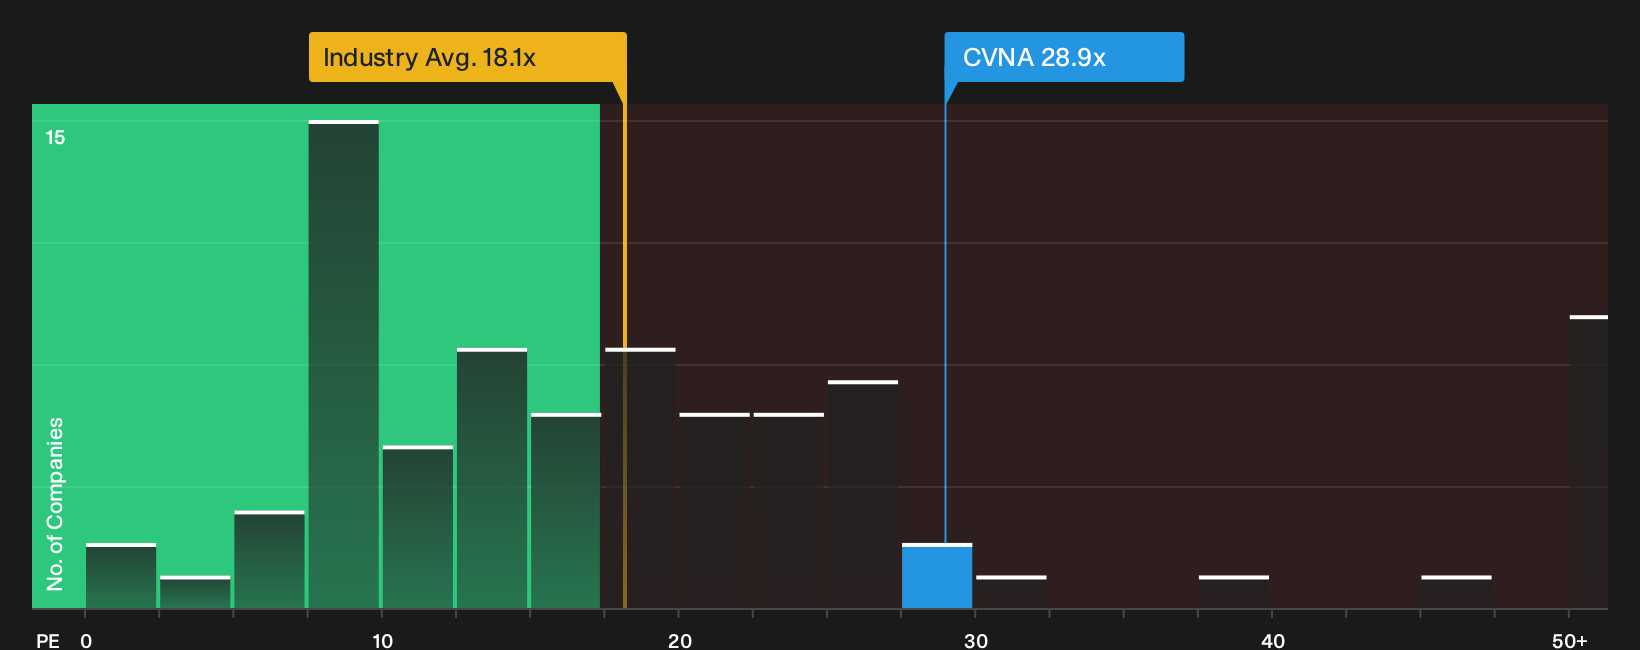
The fair value story at $80.86 leans on growth and profitability holding together. On a simple earnings yardstick, Carvana trades on a P/E of 28.9x, which is above the US Specialty Retail industry at 18.1x, the peer average at 19x, and the fair ratio of 26.2x.
That gap points to valuation risk if expectations ease or sector multiples cool off. It leaves a practical question for you to answer: Is current pricing a reasonable premium for Carvana’s growth profile, or are you paying too far ahead of the numbers?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty of strong opinions surround Carvana right now, but your money needs your own conviction, not someone else's headline. Move quickly from headline noise to hard numbers by weighing the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Carvana?
If Carvana has your attention, do not stop there. Cast a wider net and let data driven screens surface opportunities you might otherwise miss.
- Target stability first by reviewing companies that qualify as a 29 resilient stocks with low risk scores so potential downside does not catch you off guard.
- Chase quality at a sensible entry point by scanning a 33 high quality undervalued stocks where solid fundamentals and pricing line up more cleanly.
- Build reliable income streams by focusing on a 5 dividend fortresses that can support regular cash payouts alongside your capital exposure.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com