


EN
Flywire (FLYW) Lands Liquidity Services Deal As Its Valuation Case Gets Harder To Ignore
Why Liquidity Services Picked Flywire
Flywire (FLYW) just secured a high profile role powering domestic and cross border B2B payments for Liquidity Services Inc., operator of a global surplus assets marketplace.
The partnership centers on Flywire’s payment platform handling transactions across more than 240 countries and 140 currencies, automating reconciliation and integrating directly with Liquidity Services’ e-commerce portal through API integration.
Flywire’s latest contract arrives as momentum has been building in the ticker, with a 30 day share price return of 12% and a year to date share price gain of 41.65%. The 1 year total shareholder return of 47.82% contrasts with a 3 year total shareholder return that declined 30.84%, signaling a market that has recently become more positive on its prospects despite earlier weakness.
Spot opportunities around Flywire’s momentum by scanning a curated set of 19 high quality undiscovered gems that are also building real businesses behind their payment and software stories.Flywire is coming off a sharp run, backed by a fresh marquee client win, which raises a blunt timing call for you as an investor. Is it more sensible to pay up now, or wait and risk missing it entirely?
Most Popular Narrative: 7% Undervalued
On the most followed view of Flywire, the fair value sits at $21.07, slightly above the latest close at $19.69. This frames the recent rally as still short of that narrative target.
Project ADAPT and wider digital transformation are expected to peak in investment in 2027, after which management plans to keep operating costs roughly flat while still funding priorities. Recent adjusted EBITDA margin expansion into the low 20% range indicates that further operating leverage could support higher net margins and earnings.
See why 9 investors see Flywire as 7% undervalued.
Result: Fair Value of $21.07 (UNDERVALUED)
Still, Flywire’s story can break if regulatory tightening hits international student flows harder than expected, or if lower margin segments dilute the earnings power analysts are building into their models.
Find out about the key risks to this Flywire narrative.
Another Angle On Flywire’s Valuation
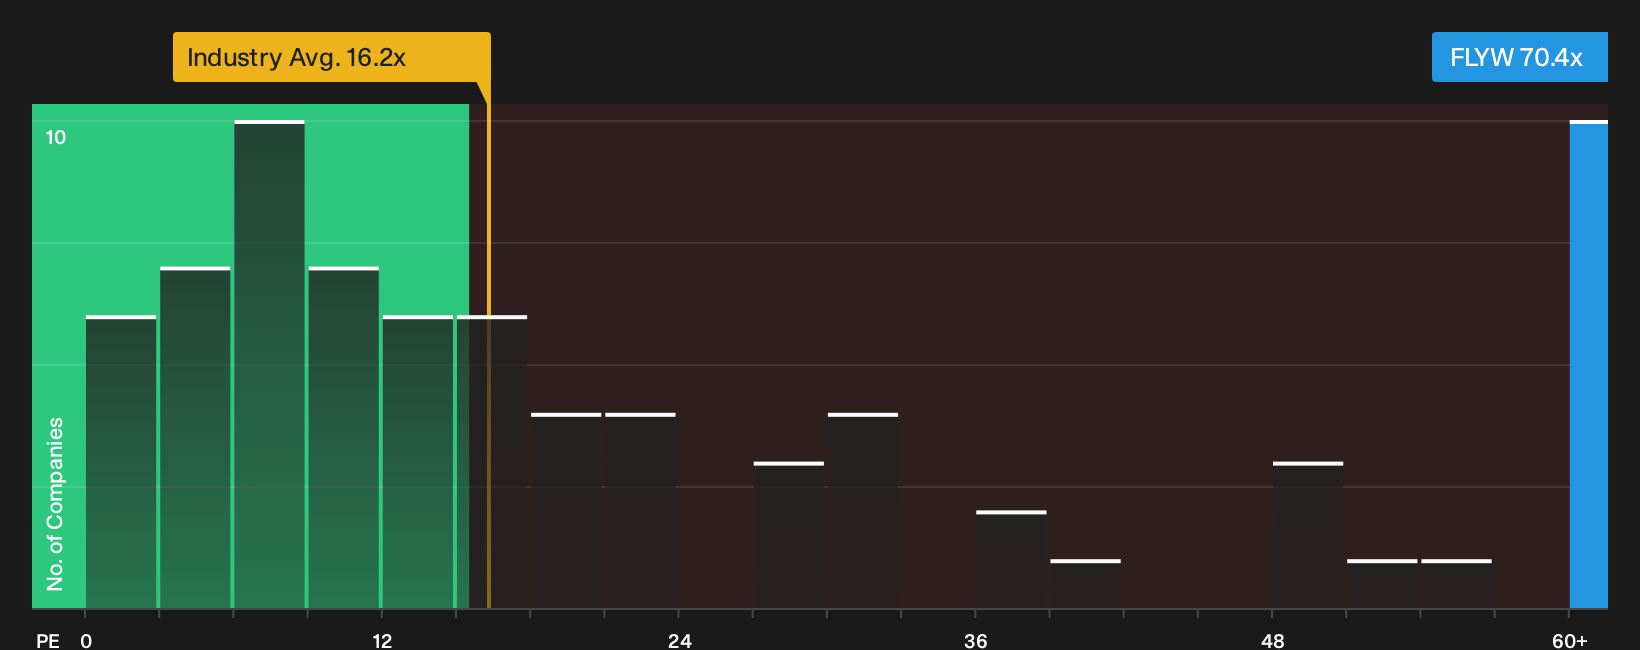
On price alone, Flywire tells a very different story. The shares trade on a P/E of 70.4x, which is almost double the 36.5x peer average and more than four times the US Diversified Financial industry at 16.2x. The fair ratio sits at 21.5x, so today’s multiple leaves little room for disappointment and plenty of scope for a re-rating if expectations cool. Which lens do you trust more when the story and the sticker price pull in opposite directions?
To see how this richer earnings multiple stacks up in detail, including how it compares with peers and that 21.5x fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Flywire create a real judgment call. Move quickly, study the numbers for yourself and weigh both sides of the story with 3 key rewards and 1 important warning sign
Looking for more Flywire sized opportunities?
Do not just stop at Flywire. Broaden your watchlist with focused stock ideas that match your style so you are not chasing the same crowded trade as everyone else.
- Target potential mispricings by reviewing a curated set of companies that appear overlooked on fundamentals through the 33 high quality undervalued stocks.
- Protect your downside first and let upside take care of itself by scanning the 29 resilient stocks with low risk scores for businesses with resilient risk profiles.
- Prioritise financial resilience by running through the list of solid balance sheet and fundamentals (24 results) so you are focusing on companies built to endure tougher cycles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com