


EN
Is Italgas (BIT:IG) Cheap After Q3 Earnings Or Already Fairly Valued?
Why Italgas Stock Is Back In Focus After Q3 Earnings
Italgas (BIT:IG) has moved back onto investor watchlists after reporting third quarter and nine month results to 30 September 2026, updating sales, revenue and net income across its gas and water operations.
Recent trading suggests a mild change in tone around Italgas. The share price has climbed 8.38% over the past month after a softer period earlier in the year, while the 1 year total shareholder return of 2.82% and the very large 3 year total shareholder return of 128.83% indicate that investors who held through volatility have been well compensated.
Scan how Italgas compares with other regulated utilities by reviewing our handpicked list of resilient balance sheet plays in the list of solid balance sheet and fundamentals (199 results).
The recent 8.38% move puts Italgas in an interesting spot. Is the market now reacting to steadier earnings progress, or has sentiment simply swung back in its favour as valuation resets?
Most Popular Narrative: 17% Undervalued
The most followed narrative pegs fair value for Italgas at €10.75, above the recent close of €8.95. This implies investors are pricing the shares below those assumptions and leaving a valuation gap on the table.
The structural role of gas networks in a cost constrained, security focused European energy mix, with electricity prices remaining a multiple of gas and rising AI driven power demand, supports sustained utilization of Italgas grids and underpins long term revenue visibility and RAB growth.
The accelerating need for system flexibility as renewables penetration rises, making molecules essential to balance a rigid, more electrified system, reinforces the value of highly digitized gas networks and justifies the EUR 7.7 billion network investment pipeline.
See why 6 investors see Italgas as 17% undervalued.
Result: Fair Value of €10.75 (UNDERVALUED)
Still, if Italgas delivers its planned €16.5b investment program and fully realises 2i Rete Gas synergies, earnings could outpace today’s fair value narrative.
Find out about the key risks to this Italgas narrative.
Another View On Italgas: Cash Flows Point The Other Way
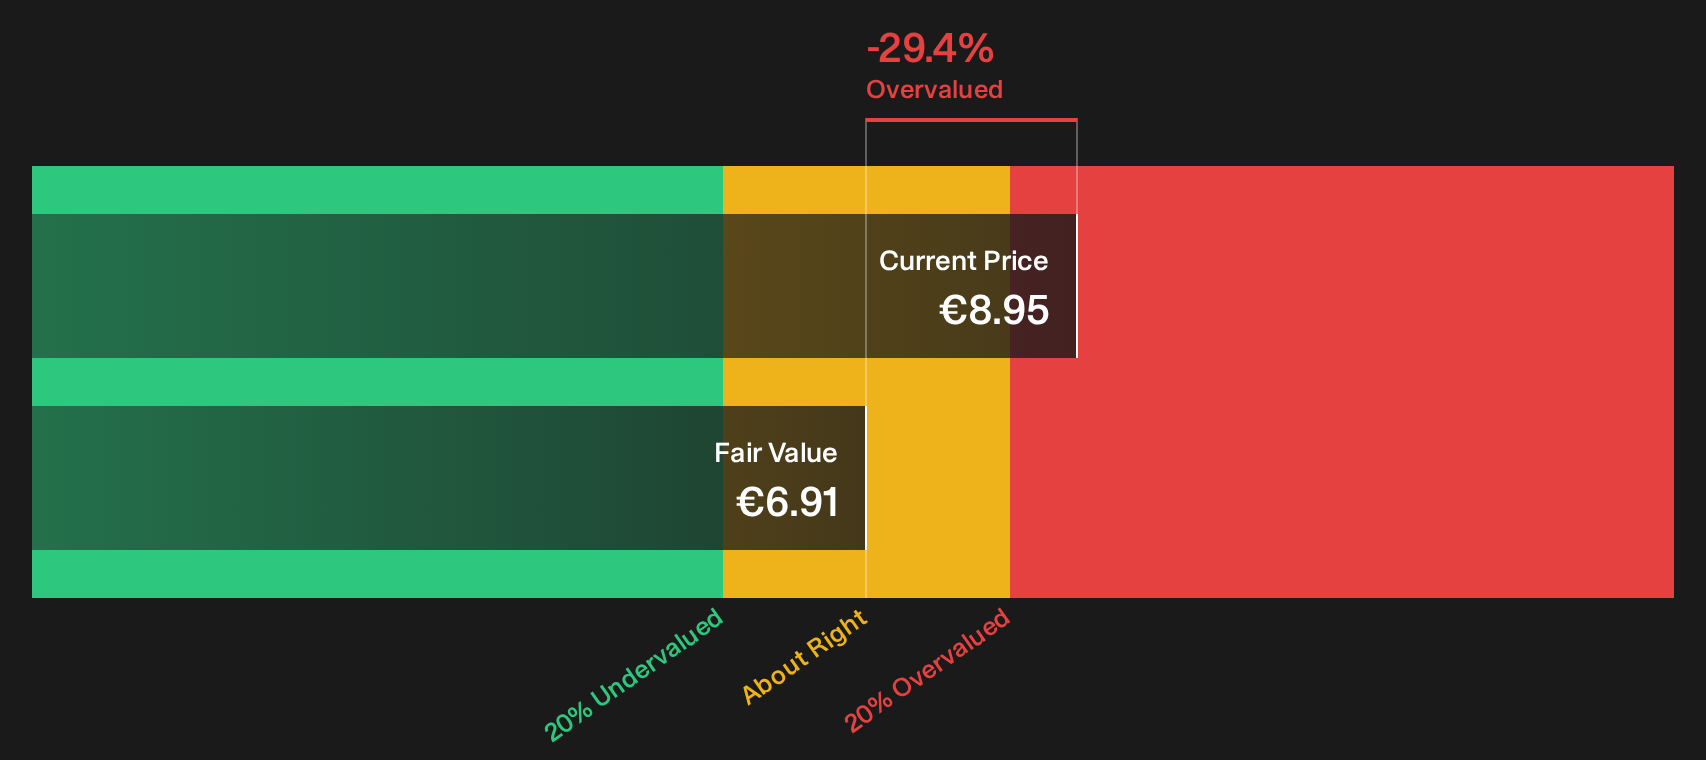
There is a twist once the Simply Wall St DCF model is brought into the picture. On that approach, Italgas at €8.95 is trading above an estimated future cash flow value of €6.91, which frames the stock as overvalued rather than cheap.
This gap matters because it asks a simple question: Are earnings based measures underplaying cash flow pressure, or is the DCF model being too harsh on a regulated utility with long life assets?
To understand how this cash flow view is built, and why it differs from the earnings based fair value, Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Italgas for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 204 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Italgas so far. If that feels incomplete, you can quickly weigh the upside and downside yourself by reviewing the 5 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Italgas?
If Italgas has sharpened your focus on quality, do not stop here. A few minutes with the right screeners can reshape your opportunity set completely.
- Target fresh upside potential by reviewing the 614 high quality undiscovered gems that combine solid fundamentals with the kind of under-the-radar profile many investors overlook.
- Prioritise resilience first and check the 218 resilient stocks with low risk scores to see businesses with steadier balance sheets and lower overall risk scores.
- Hunt for stronger income streams and compare Italgas with the 221 dividend fortresses that may align better with long term payout goals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com