


EN
Is Hanover Insurance Group (THG) Fully Priced As Record Q3 Earnings Beat Guidance?
What triggered fresh interest in Hanover Insurance Group?
Hanover Insurance Group (THG) just posted record third quarter operating EPS of $5.15, supported by underwriting results that management highlighted as stronger across business segments and an outlook for a better than originally guided full year combined ratio.
That earnings beat has landed in a market that already had momentum behind Hanover Insurance Group, with a 10.33% 1 month share price return and a 35.20% year to date share price gain. Alongside the record operating EPS, buybacks completed since May and a 44.49% 1 year total shareholder return point to investors rewarding both execution and capital returns over the short and longer run.
Scan beyond Hanover Insurance Group and review a curated set of insurers and financials with strong fundamentals and recent momentum using the 29 resilient stocks with low risk scores as a starting point.
Bulls see Hanover Insurance Group’s record Q3 earnings, stronger underwriting and active buybacks as the foundation of a higher valuation. Bears point to the recent rally and question how much of that strength is already reflected in the price.
Most Popular Narrative: 1.6% Overvalued
Hanover Insurance Group closed at $242.09, modestly above the most followed fair value estimate of $238.25 that is based on a 7.24% discount rate and detailed cash flow assumptions.
The main factor that has to go right is that Hanover successfully scales its Specialty and Small Commercial growth plans while keeping combined ratios and loss adjustment expenses in line with its long-term targets.
The current view that Hanover Insurance Group is fairly valued and bearish implies that the share price already reflects management’s long-term targets for ROE, earnings growth, and capital returns, leaving limited room for a higher valuation if execution simply tracks those plans.
See why 8 investors see Hanover Insurance Group as 2% overvalued.
Result: Fair Value of $238.25 (OVERVALUED)
Still, the Hanover Insurance Group story could shift quickly if Specialty growth underwhelms, or if catastrophe losses move higher again and pressure underwriting results.
Find out about the key risks to this Hanover Insurance Group narrative.
Another View: SWS DCF Puts A Much Higher Tag On Hanover Insurance Group
The fair value from the most followed narrative sits at $238.25 and frames Hanover Insurance Group as 1.6% overvalued. The SWS DCF model tells a very different story. On that approach, THG screens as undervalued, with our future cash flow estimate at $505.23 per share versus the current $242.09 price.
This gap is large enough that it raises a practical question for investors. Is the cash flow outlook too optimistic, or are near term earnings based tools missing part of Hanover Insurance Group’s longer term earnings power, especially given its use of AI and capital returns.
For a closer look at how those assumptions stack up against the cash flow math, Look into how the SWS DCF model arrives at its fair value..
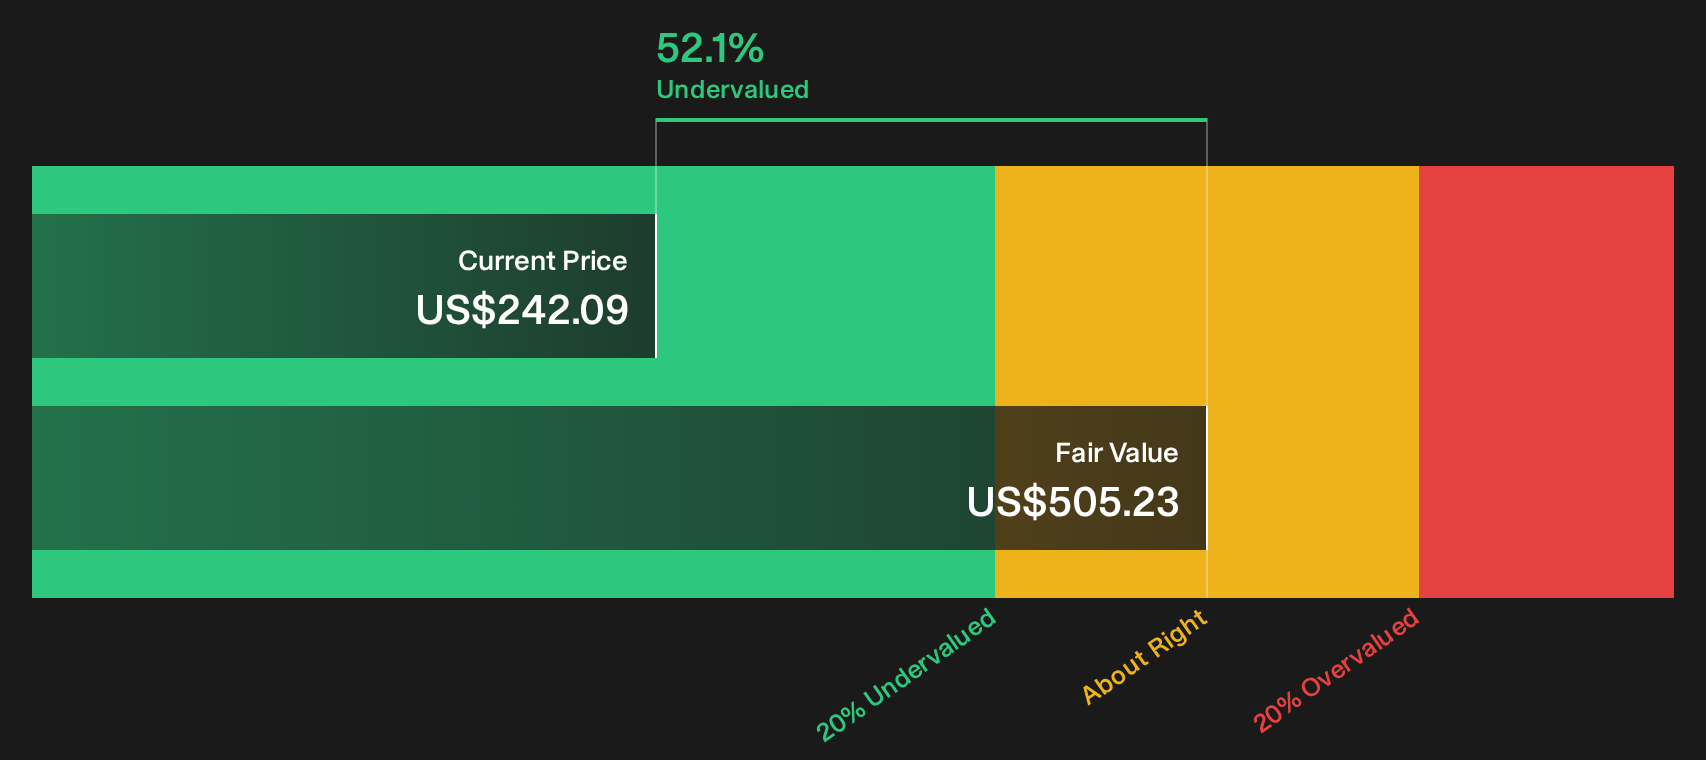
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hanover Insurance Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Hanover Insurance Group’s valuation and risk reward profile make this a stock that invites closer inspection rather than quick conclusions. If you want to stress test the upside against the potential downside using the same dataset, start with the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Hanover Insurance Group?
If Hanover Insurance Group has your attention, do not stop here. Broaden your watchlist with a few targeted screens that can surface fresh opportunities fast.
- Target resilient balance sheets and steady fundamentals by reviewing our curated list of solid balance sheet and fundamentals (24 results) that can help you cut through weaker prospects quickly.
- Spot potential mispricings by scanning the 33 high quality undervalued stocks and compare quality businesses trading at valuations that may not match their fundamentals.
- Lock in cash flow ideas by reviewing the 5 dividend fortresses that focuses on higher yielding companies built around more durable payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com