


EN
Dividend Utility Stocks Built For Higher Rates
Higher for longer is no longer a theory; it is the backdrop for every decision you make in the market. With the October US CPI print on Nov 10 likely to steer the Fed’s December call, income investors face a rare mix of risk and potential opportunity in quality dividend stocks that could benefit from firm yields. This article unpacks three US large cap dividend stocks exposed to that inflation story.
The stocks discussed below are a small sample to illustrate the theme, and the full screen surfaced 13 more large cap dividend payers with equally compelling income stories that are not covered here. To go straight to the source and identify your own highest conviction ideas, analyze the US large‑cap quality dividend stocks (beneficiaries of higher‑for‑longer interest rates) screener.
ONE Gas (OGS)
ONE Gas fits this higher for longer dividend theme as a regulated utility whose core service is keeping gas flowing for homes and businesses while paying out steady income.
ONE Gas operates a regulated natural gas distribution network serving 2.3 million customers across Oklahoma, Kansas, and Texas, generating about US$2.3b from regulated public utilities and carrying a market value near US$4.9b.
"Favorable regulatory frameworks in Texas, Kansas, and Oklahoma, including mechanisms that defer depreciation, allow carrying costs on capital, and expand surcharge eligibility, are expected to support more predictable revenue recovery and help ONE Gas translate its multi year capital program into steadier earnings."
What matters next is how one persistent cost pressure shapes the path for margins and dividend comfort over the coming years.
That margin story is only half of it, since the full narrative for ONE Gas maps how regulation, capital spend and inflation risk could be quietly reshaping ONE Gas as an income vehicle.

California Water Service Group (CWT)
California Water Service Group is a regulated water utility built around essential household and business demand, which fits the screener’s focus on large, dividend-paying defensives that can hold up when rates stay higher for longer, backed by a market value of about US$3.0b.
Accelerating capital investment in water infrastructure and modernization is now supported by a roughly 11% 10-year growth capital CAGR, along with management expectations for nearly 12% rate base CAGR to around US$3.5b by 2028.
The real swing factor is how one regulatory outcome ultimately flows through to what matters most: dividend comfort and earnings quality.
That hinge point on dividend comfort is exactly what full narrative for California Water Service Group unpacks, separating short term rate noise from how California Water Service Group’s story could be quietly accelerating.
Sempra (SRE)
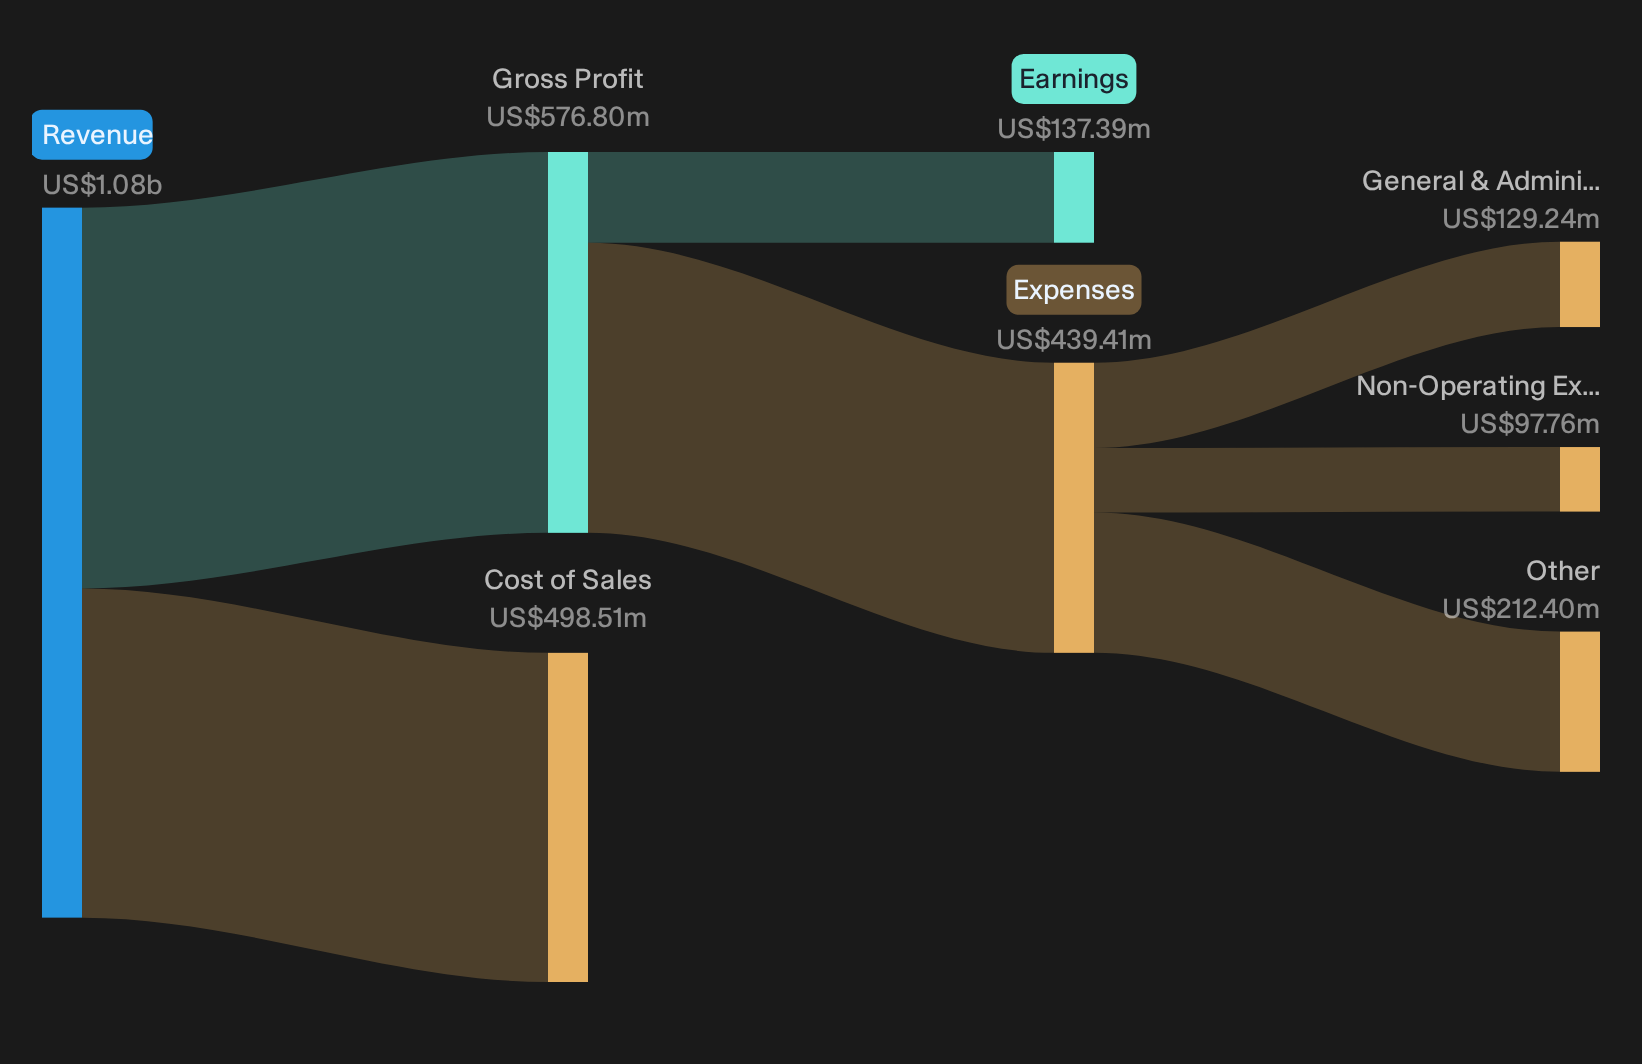
Sempra is a regulated utility group that fits this quality dividend screen through its large scale gas and power networks in California and Texas, plus an energy infrastructure arm. Most of its US$13.6b top line comes from Sempra California at about US$11.7b, with roughly US$2.0b from Sempra Infrastructure and a small intersegment adjustment, supporting a market value near US$56.3b.
Sempra runs electric and gas utilities in the US and Mexico, with Sempra California serving millions of households and businesses, Sempra Texas Utilities handling transmission and distribution, and Sempra Infrastructure investing in long lived energy assets that support a defensive income profile in a higher for longer rate environment.
"Strong demand growth in Texas, including large load requests under the Batch Zero process that equate to about 140% of Oncor's current peak load and are backed by over US$2b of customer collateral, supports the view that Sempra's multi decade grid buildout plan can continue to expand regulated rate base and future revenues."
The key issue is how one long running regulatory and funding pressure ultimately shapes the balance between steady demand, earnings quality, and dividend comfort.
That turning point is exactly what the full narrative for Sempra unpacks. It reveals how Sempra’s demand story, regulatory pressure, and capital plans could be quietly decoupling from the headline risk.

Curious About Fresh Alternatives?
Some of the most interesting breakout stories often fly under the radar for now, and the best entry points get caught quickly. Do not delay, get in early.
- Target resilient cash generators before momentum takes off by scanning the curated list of solid balance sheet and fundamentals (24 results) while that list still reflects today’s prices and not tomorrow’s rerating.
- Track fast moving automation tailwinds and spot potential beneficiaries of robotics demand shifts using the focused 95 robotics and automation stocks before that theme stops looking early and starts looking crowded.
- Position ahead of possible energy grid upgrades and electrification momentum by reviewing the hand picked 41 power grid technology and infrastructure stocks while these infrastructure stories are still priced as under the radar for now.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com