


EN
Did Raised Earnings Guidance Just Shift Hilton Stock's Investment Narrative?
- Hilton Worldwide Holdings reported third quarter 2026 basic EPS from continuing operations of US$2.39 and diluted EPS of US$2.37, issued fourth quarter and full year earnings guidance, and affirmed a regular quarterly dividend of US$0.15 per share payable on December 29, 2026.
- Management highlighted strong business and group travel demand alongside Hilton's largest quarter for organic hotel openings. The company also advanced digital tools such as the new Pay with Points loyalty feature and expanded its Nordic development footprint through a multi year agreement with Scandic Hotels Group.
- Now the focus shifts to how Hilton Worldwide Holdings' stronger earnings guidance could reshape the longer term investment narrative around the business.
Look beyond Hilton Worldwide Holdings and evaluate other travel and experience companies with resilient earnings profiles using our hand picked 19 high quality undiscovered gems list.
Hilton Worldwide Holdings Investment Narrative Recap
For Hilton Worldwide Holdings, the core belief is that its fee based model, large room pipeline and brand breadth can keep translating travel demand into higher earnings over time. The raised full year 2026 diluted EPS guidance range of US$8.38 to US$8.44 leans into that story, with business and group travel currently doing a lot of the heavy lifting.
The near term swing factor is whether that demand holds up enough to support the upper end of guidance while weaker regions, renovation disruption and debt coverage do not erode profitability. Regional RevPAR pressure in areas like the Middle East and China, plus execution on major hotel refurbishments, still feels like the biggest operational risk.
The launch of Pay with Points inside the Hilton Honors app is the announcement that connects most clearly to Hilton Worldwide Holdings' current earnings story. Management is pushing more activity into its own digital channels and tying spend more tightly to loyalty. That approach can help keep occupancy and rate mix resilient when conditions are uneven by encouraging members to concentrate their trips with Hilton.
On the risk side, the payoff from Pay with Points depends on clean execution and owner economics. If digital tools reduce distribution costs and help owners maintain margins, they can reinforce pipeline conversion and fee growth. If uptake is weaker than hoped, or if softer leisure and regional demand trends persist, this loyalty upgrade may matter more as defense than as a near term catalyst.
Hilton Worldwide Holdings' current earnings are about US$1.7b, with analysts expecting earnings of US$2.7b by 2029. This implies an increase of roughly US$1.0b, supported by forecast revenue growth of 46.0% per year and projected 2029 revenues of US$16.1b.
Uncover why Hilton Worldwide Holdings' fair value is assessed as roughly consistent with its current price.
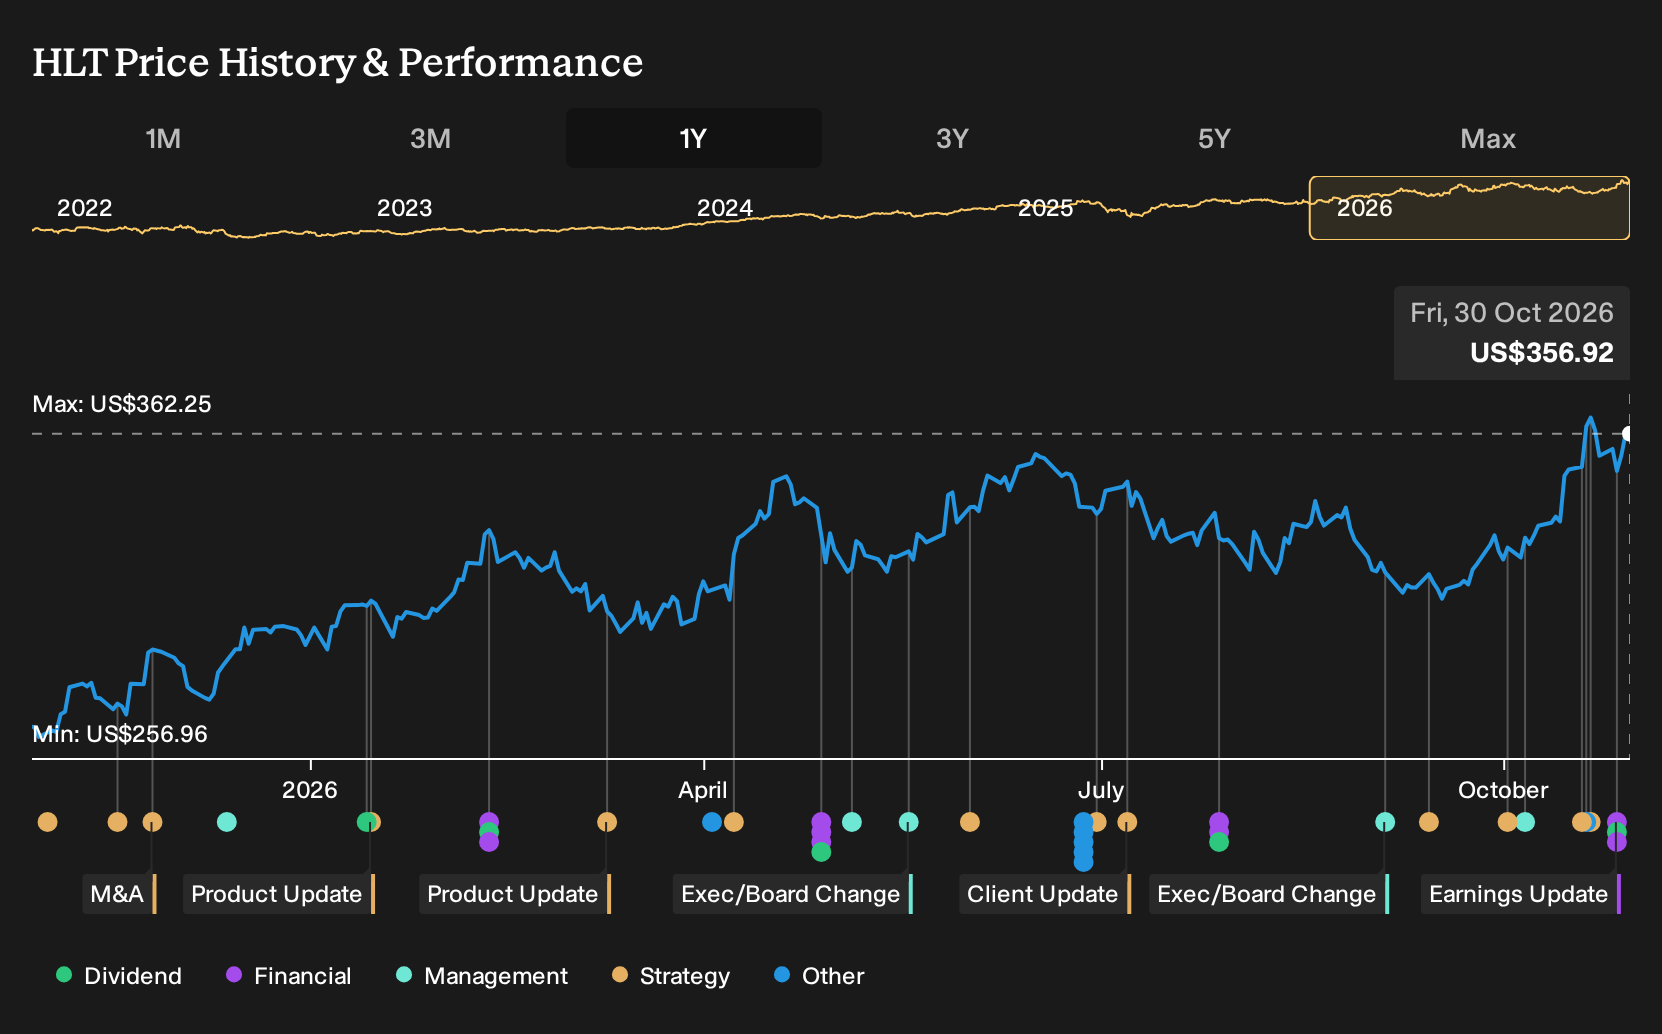
Exploring Other Perspectives
The two fair value estimates from the Simply Wall St Community span a wide range, from about US$249 to US$362, which already shows how far opinions on Hilton Worldwide Holdings can stretch. Those views pre date the stronger earnings guidance, dividend affirmation and new tech and Nordic agreements, so use them as starting points and compare several Community perspectives before deciding how you see the risk and reward trade off.
Explore another Hilton Worldwide Holdings fair value estimate, including one that suggests it could be worth as much as $362.11.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Hilton Worldwide Holdings research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Hilton Worldwide Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hilton Worldwide Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Hilton Worldwide Holdings?
Once you have formed a view on Hilton Worldwide Holdings, broaden your watchlist by scanning for other businesses that match the kind of earnings quality, balance sheet strength or income profile you want to own over the long run.
- For investors hunting for underappreciated opportunities with strong fundamentals, review our 33 high quality undervalued stocks that may be trading below what their cash flows suggest.
- If capital preservation and steadier profiles matter most to you, focus on our 29 resilient stocks with low risk scores that screen for companies with resilient risk scores.
- For readers who care about financial strength first and growth second, start with our list of solid balance sheet and fundamentals (24 results) that highlight businesses carrying sturdier balance sheets and fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com