


EN
Learn Why The Bull Case For Amex Stock Could Change Following Raised Earnings Guidance
- American Express reported higher third quarter 2026 net income of US$3,712 million and raised full year earnings guidance while announcing new partnerships with Airbnb and Albertsons that extend its reach in travel and everyday spending.
- The combination of stronger earnings, increased EPS guidance, and new co branded card relationships indicates that American Express is placing greater emphasis on premium travel benefits and daily spend categories to deepen customer engagement.
- Next, the focus will be on how American Express' upgraded earnings guidance fits into its broader investment narrative for long term investors.
Scan how American Express’ mix of higher earnings, funding moves and new card partnerships compares with other potential breakouts by reviewing the hand picked 33 high quality undervalued stocks.
American Express Investment Narrative Recap
To own American Express, investors need to be comfortable with a premium, rewards-heavy model that depends on cardmember spending, fee income and disciplined control of customer engagement costs. The raised 2026 EPS guidance, alongside higher year-to-date earnings, points to management continuing to lean into this formula rather than pulling back on investment.
The key near-term catalyst is whether revenue growth and fee momentum can offset headwinds from co-brand portfolio sales and high rewards spend that sits around 44% to 45% of revenue. The main operational risk remains margin pressure if customer engagement costs or funding expenses outpace billed business growth.
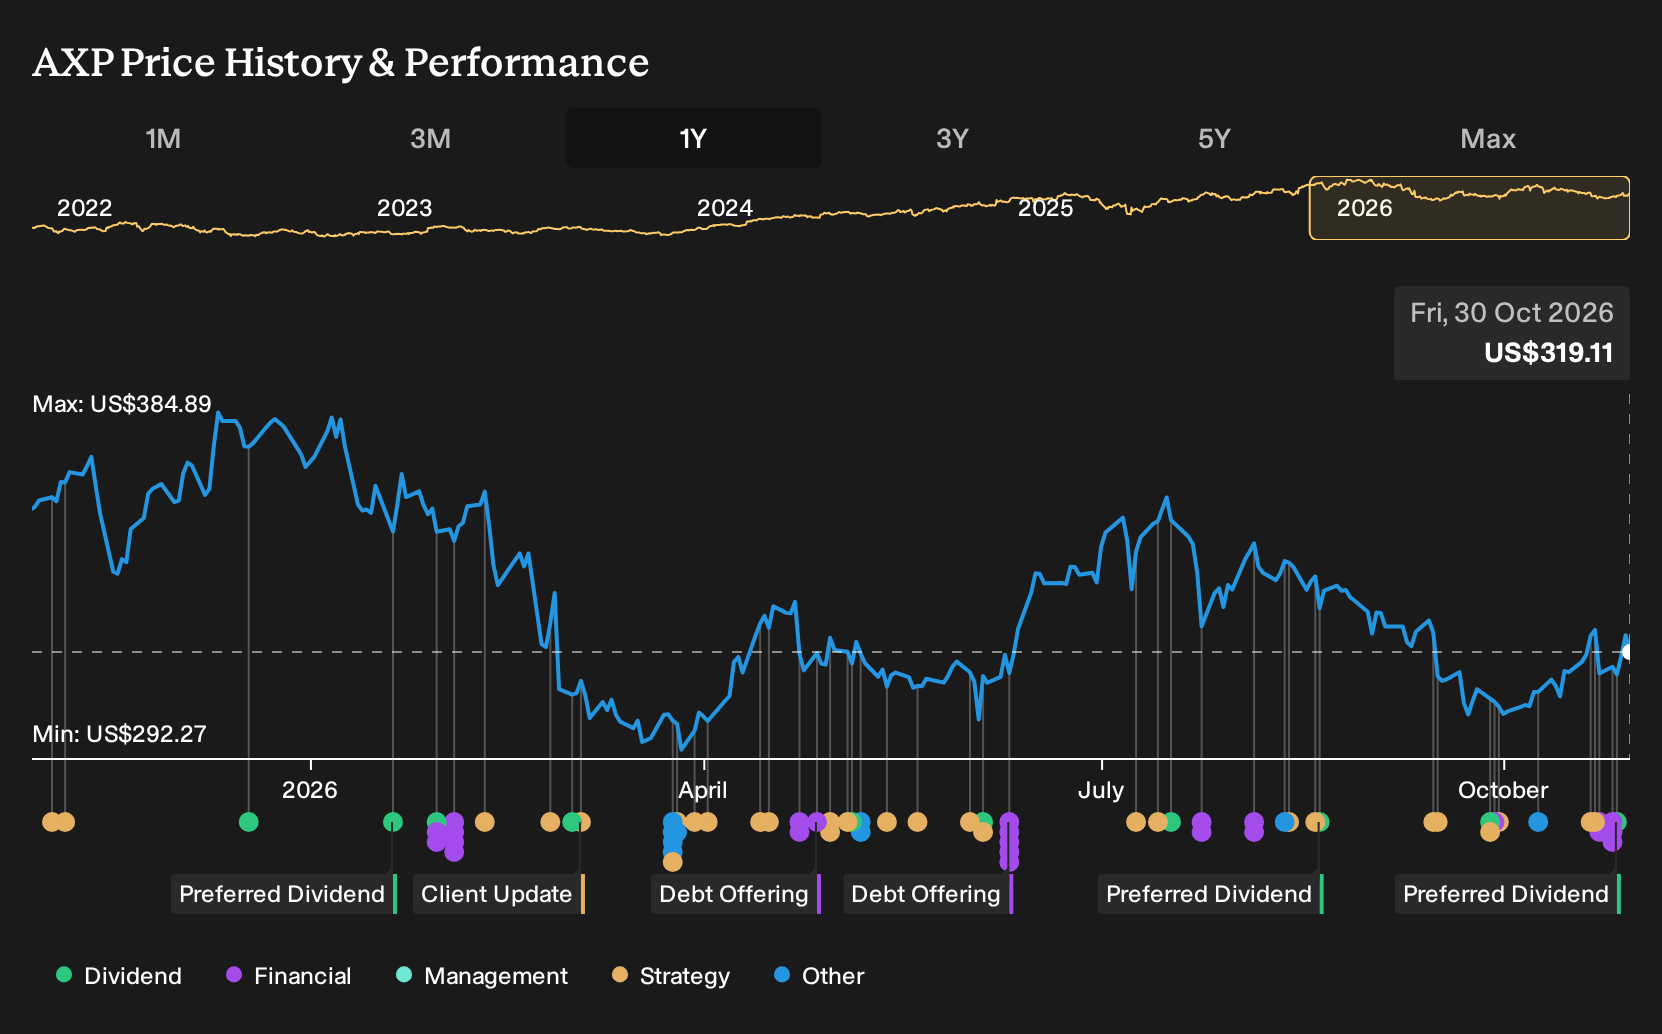
The recent US$3.0b of callable, senior unsecured variable rate notes is central to how American Express funds that premium growth model. New fixed-to-floating and floating-rate issues out to 2030 and 2034 provide the business with fresh funding that will influence net interest expense and flexibility for marketing and rewards spend.
For catalysts, the interaction between this higher-cost external funding base and the company’s rich rewards strategy is important. If engagement costs and interest expense both remain high, execution needs to be tight on card fee growth, international volumes and small business products so earnings fully reflect the capital being raised.
American Express' current analyst narrative points to revenues of US$98.3b and earnings of US$15.4b by 2029, based on revenue growing at 11.5% a year and earnings rising by about US$4.1b from US$11.3b today.
Uncover how American Express' fair value indicates a 16% potential upside to its current price that could close sooner than investors expect.
Exploring Other Perspectives
You might see the recent US$3.0b funding and preferred dividend moves as routine capital management. The most optimistic analysts treat funding capacity itself as a catalyst, since their pre news models already baked in US$102.9b of 2029 revenue and US$16.7b of earnings. Those expectations were set before this update, so their narrative could get even more aggressive or be reined in from here.
Explore 8 other American Express fair value estimates, including one that suggests as much as 39% potential upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your American Express research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for American Express. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate American Express' overall financial health at a glance.
Looking for more American Express sized ideas?
Once you have a handle on American Express, it can help to widen the lens and compare it with other opportunities that match your risk tolerance, income goals, or balance sheet preferences using the Simply Wall St Screener.
- If you want potential mispricings with strong fundamentals, scan a curated 33 high quality undervalued stocks that may sit closer to what you are looking for.
- For investors who care most about steady income, focus on companies in the 5 dividend fortresses that prioritize payouts supported by their financial profiles.
- When capital preservation is the priority, start with our 29 resilient stocks with low risk scores to see businesses screened for resilience and lower risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com