


EN
Walker & Dunlop (WD) Could Be 28% Undervalued As Refinancing Activity Picks Up
Walker & Dunlop (WD) recently arranged US$117.3 million of floating rate, interest only refinancing for three newly built Texas apartment communities, an event that puts its multifamily financing activity in focus for investors.
At a share price of US$34.79, Walker & Dunlop has seen short-term momentum firm up, with the 7-day and 30-day share price returns both positive. However, the 1-year total shareholder return and 5-year total shareholder return show deep declines, signaling that recent refinancing wins are arriving after a prolonged reset in investor expectations.
Spot opportunities beyond Walker & Dunlop by scanning a curated 19 high quality undiscovered gems with solid fundamentals that may not yet be on most investors' radar.Walker & Dunlop shares have bounced in the short term, while multi year returns remain sharply lower. Does that mix of recent momentum and long term pain still skew the risk reward toward buyers at this price?
Most Popular Narrative: 28% Undervalued
With a last close of $34.79, the most followed valuation narrative for Walker & Dunlop indicates a fair value of $48.33. The narrative focuses on whether the refinancing and equity gap themes materialize over time under a 7.3% discount rate.
Ongoing refinancing and construction activity in a higher rate setting, including recent large multifamily, mixed use, office and workforce housing deals in Miami, Manhattan, Jersey City and other markets, keeps Walker & Dunlop well positioned to generate fee income from a sustained recapitalization cycle that can support revenue and earnings.
See why 1 investors see Walker & Dunlop as 28% undervalued.
Result: Fair Value of $48.33 (UNDERVALUED)
Still, high interest costs pressuring commercial real estate and intense competition for specialist originators could weaken Walker & Dunlop’s deal flow and fee economics.
Find out about the key risks to this Walker & Dunlop narrative.
Another View: Walker & Dunlop Looks Expensive On Earnings
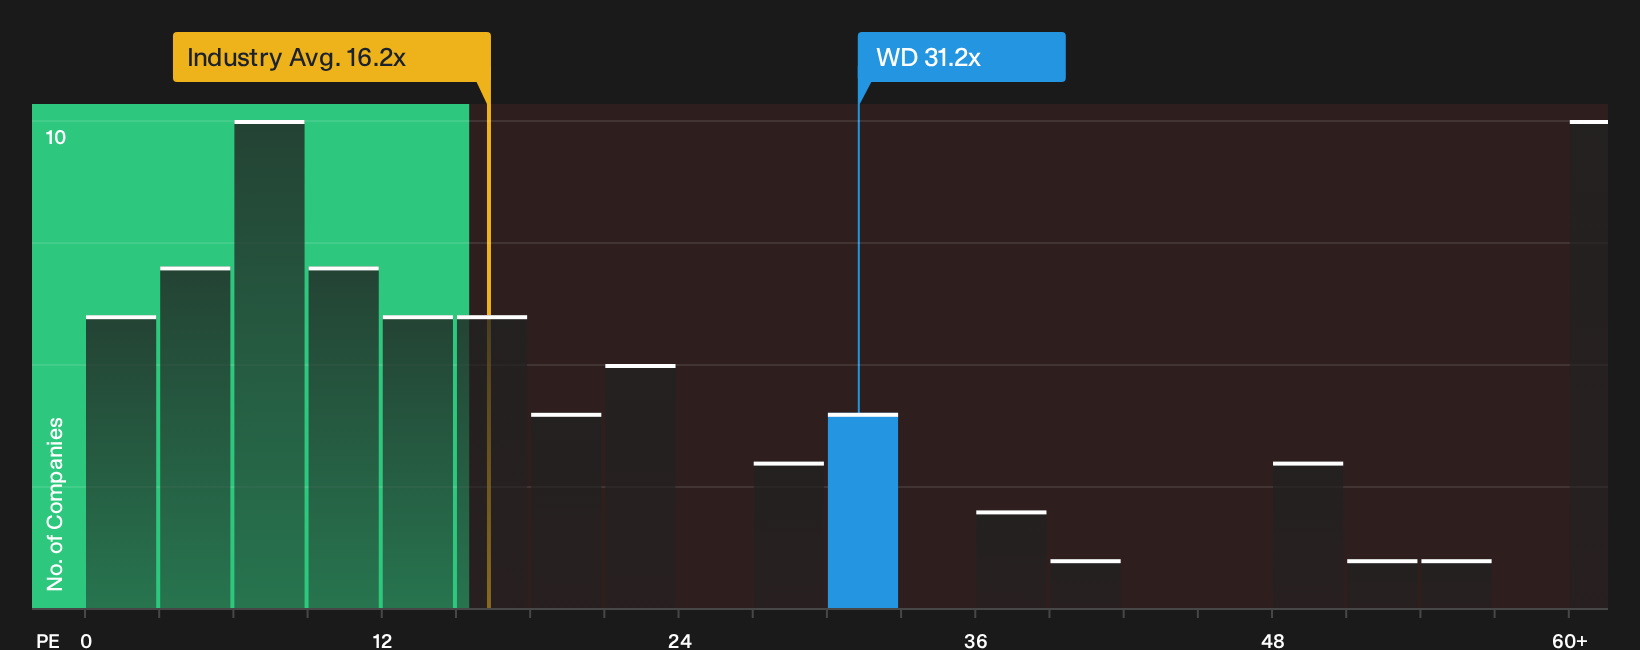
That $48.33 fair value narrative leans on future earnings growth and a lower P/E in 2029. Yet today Walker & Dunlop trades on a P/E of 31.2x, compared with a fair ratio of 19.4x, the US Diversified Financial industry at 16.2x, and peers at 10.3x.
This gap suggests investors are already paying a premium for WD relative to both its sector and similar companies, even though earnings over the past 5 years have declined and return on equity sits at 2.4%. The question is whether you view that rich multiple as justified optimism or valuation risk waiting to reset.
To pressure test that view against detailed ratio work and peer comparisons, have a look at See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on Walker & Dunlop’s valuation and risk profile make this a judgment call. Move fast on the data and weigh the 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Walker & Dunlop?
Do not stop your research at Walker & Dunlop. Use powerful filters to surface fresh opportunities that fit the kind of risk and reward profile you actually want.
- Target resilient performers that focus on capital preservation and steadier returns by running a focused search through 29 resilient stocks with low risk scores.
- Zero in on companies with strong cash positions and cleaner finances by scanning a curated list of solid balance sheet and fundamentals (24 results).
- Hunt for potential bargains trading below their estimated worth by reviewing a hand picked set of 33 high quality undervalued stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com