


EN
Alkermes (ALKS) Could Be 20% Undervalued As ALKS 7290 Trial Starts
Why the ALKS 7290 Trial Matters for Alkermes Stock
Alkermes (ALKS) has pushed its orexin program forward by launching a phase 2 trial of oral OX2R agonist ALKS 7290 as add on therapy to antidepressants in adults with major depressive disorder.
The study focuses on safety and tolerability over six weeks. It also tracks changes in symptom severity on standard depression rating scales versus placebo plus antidepressant therapy in about 180 participants.
Investors have already reacted to the orexin update within a stock that has shown strong momentum this year, with Alkermes posting a year-to-date share price return of 60.44% and a 1-year total shareholder return of 47.69%. However, the 90-day share price return declined 8.46%, which suggests that enthusiasm around the pipeline is being periodically checked by changing views on risk and timing.
Scan how Alkermes fits alongside other potential breakout stories in CNS and healthcare by reviewing our hand picked list of 34 healthcare AI stocks.
Alkermes now trades around US$45 while analyst targets cluster near US$56, and one intrinsic value model points to an even larger gap. Is the recent 90 day pullback enough to close that spread, or still too thin?
Most Popular Narrative: 20% Undervalued
Alkermes last closed at $45.34, while the most followed narrative anchors fair value around $56.56, which places the stock in undervalued territory based on that framework and an 8.47% discount rate.
The main requirement is that Alkermes converts encouraging alixorexton and ALKS 7290 data into successful late stage trials, regulatory approvals and commercial adoption, while managing higher R&D spending and integration of the LUMRYZ business.
The current valuation implies investors are already pricing in meaningful success for the orexin platform and LUMRYZ expansion, even as Alkermes is guiding to a GAAP net loss in 2026 alongside positive EBITDA.
See why 9 investors see Alkermes as 20% undervalued.
Result: Fair Value of $56.56 (UNDERVALUED)
Still, the Alkermes story can change quickly if rising R&D spending weighs on earnings for a longer period or if key orexin and LUMRYZ trials disappoint regulators.
Find out about the key risks to this Alkermes narrative.
Another View on Alkermes Valuation
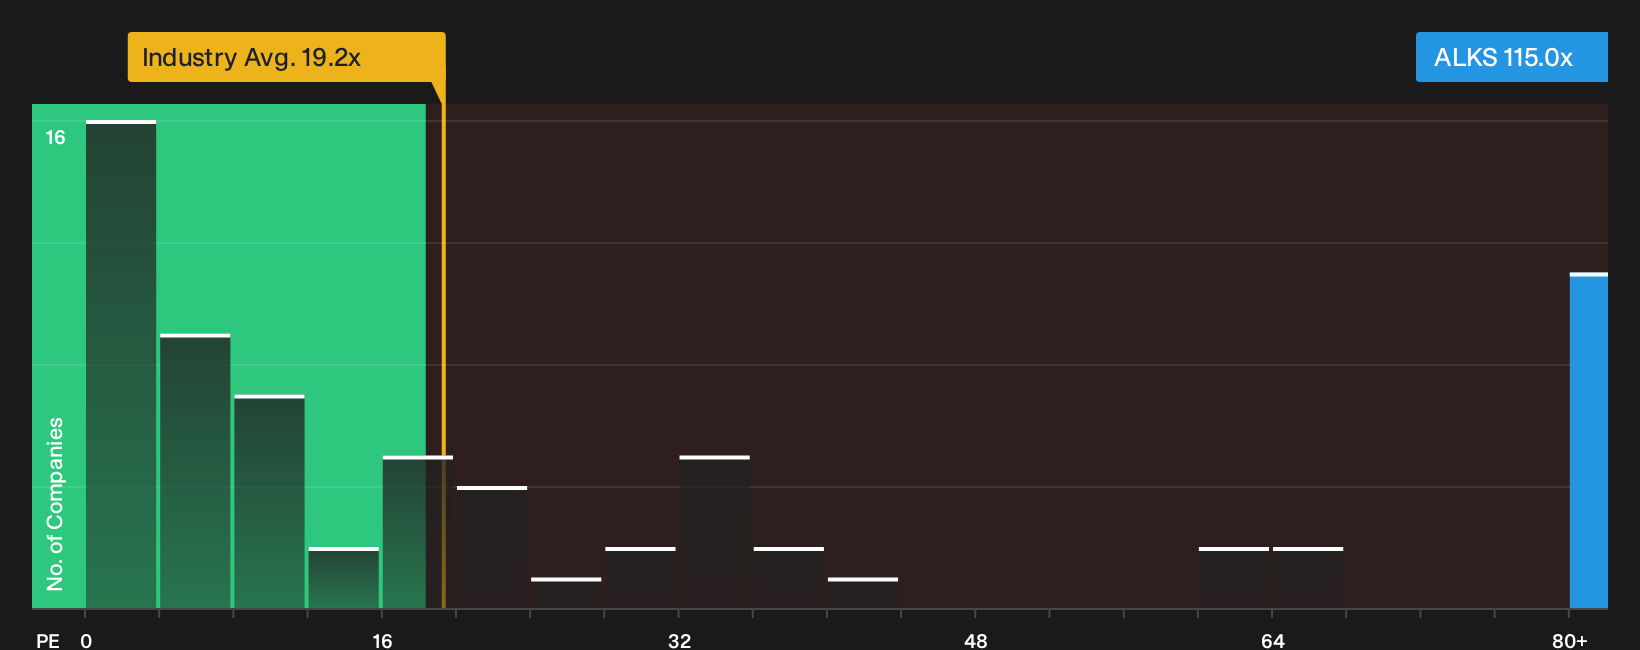
Analyst targets and fair value estimates point to Alkermes trading below intrinsic value, yet the market is putting a very rich price on current earnings. The stock sits on a P/E of 115x versus 98.9x for peers, 19.3x for the wider US Biotechs group, and a fair ratio of 42x.
That gap suggests investors are paying a premium today for earnings that are still relatively small, which can amplify both upside and downside if expectations change. With such a wide spread between the current P/E and the fair ratio the market could move toward, how comfortable are you with that valuation risk?
For a closer look at what the numbers imply, review the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Alkermes valuation and risk can feel messy. Move quickly, pull up the key data, and weigh both sides for yourself with 2 key rewards and 3 important warning signs.
Looking for more Alkermes investment ideas?
If Alkermes has your attention, do not stop here. Use the Simply Wall Street Screener to uncover fresh opportunities that match your risk and return style.
- Target value first and hunt for companies trading below what the numbers suggest they are worth through the 33 high quality undervalued stocks.
- Prioritize resilience and scan for businesses with cleaner balance sheets using the list of solid balance sheet and fundamentals (24 results).
- Reduce volatility shocks and focus on steadier performers by running a search through the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com