


EN
What’s Going On With Nexi (BIT:NEXI)?
Nexi (BIT:NEXI) has become a central player in the digital euro build out after the European Central Bank awarded the group and Deutsche Telekom a joint ten year core connectivity contract.
Nexi’s recent digital euro contract win has landed against a backdrop of improving momentum, with a 9.72% 1 month share price return and a 6.94% year to date gain, even though the 3 year total shareholder return declined 17.24% and the 5 year total shareholder return fell 66.76%.
Spot emerging payment infrastructure trends early by scanning the curated 41 power grid technology and infrastructure stocks. These could benefit from the same push toward digital rails that just put Nexi in the digital euro spotlight.Nexi now has a marquee digital euro contract and a recent share price rebound, but do those headlines leave the stock looking like a solid payments platform at a fair price, or a recovery story already reflected in the valuation?
Most Popular Narrative: 9% Overvalued
Nexi last closed at €4.44, while the most followed narrative puts fair value at about €4.09. The contract win is being weighed against a view that the stock already prices in much of the recovery and cash generation story at an 11.71% discount rate.
The valuation suggests the share price already reflects Nexi as a fairly valued, cash-generative European payments infrastructure provider, with medium-term growth supported by Digital Euro work, excess cash generation and committed dividend growth.
See why 27 investors see Nexi as 9% overvalued.
Result: Fair Value of €4.09 (OVERVALUED)
Still, the Nexi story could shift quickly if bank contract run offs keep dragging reported revenue, or if Germany’s softer backdrop spills further into group earnings.
Find out about the key risks to this Nexi narrative.
Another View: Nexi looks cheaper on revenue multiples
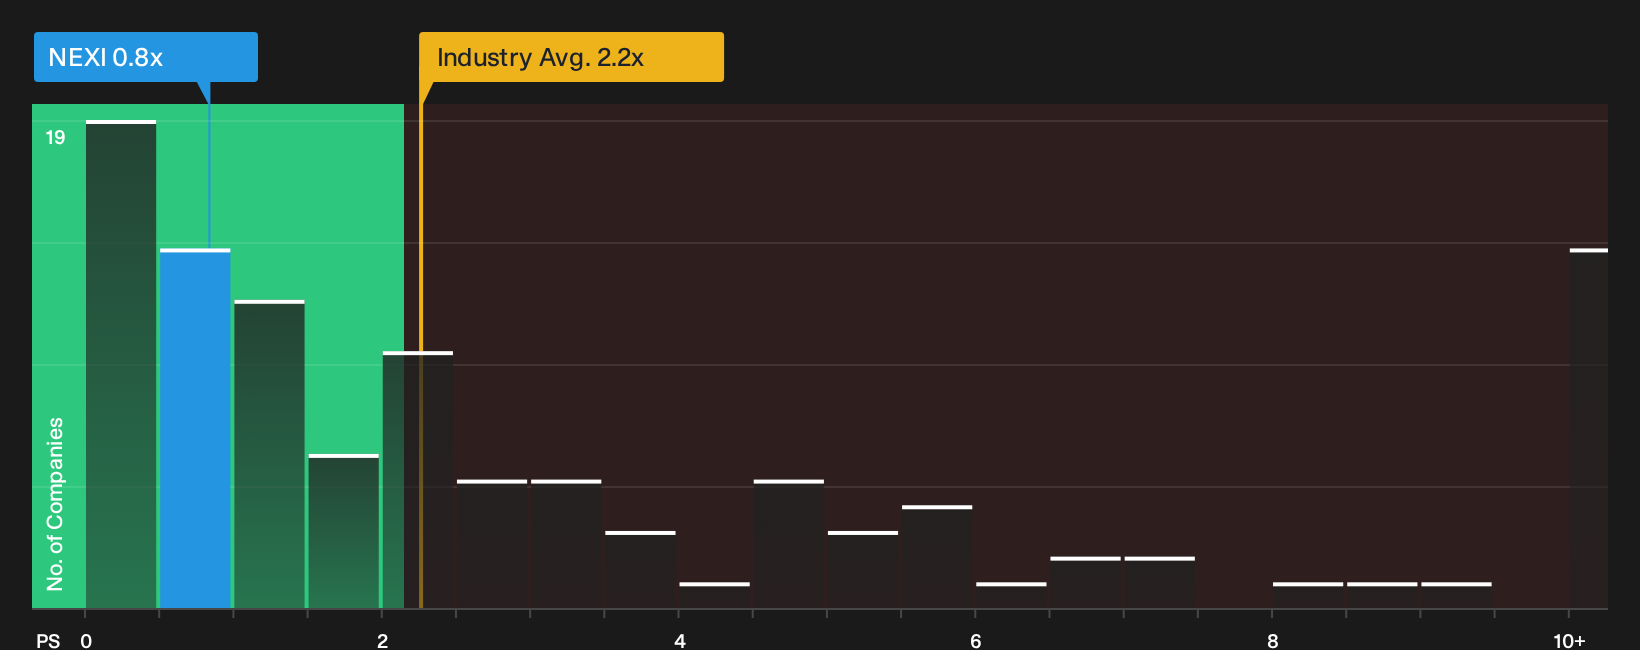
Analyst models and the SWS fair value arrive at roughly €4.09 per Nexi share, close to the recent €4.44 price. Yet the market is valuing the business on a P/S of 0.8x, compared with 2.2x for the European Diversified Financial industry, peers at 4.3x and a fair ratio of 2.7x that the multiple could move toward.
That gap points to meaningful valuation risk if the revenue drag from contracts and losses continue, but it also hints at upside potential if the turnaround and digital euro work proceed more smoothly than expected. The key question is which side of that spread narrows first: the earnings story or the low sales multiple.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views like this are exactly when your own work matters most, especially with Nexi sitting between cautious risk flags and genuine bright spots. Take a closer look through the key trade offs and decide whether the balance suits you by checking the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Nexi?
Do not stop with just one payments player. Broaden your watchlist and let structured stock lists surface opportunities you might otherwise miss.
- Target resilience first by scanning a 218 resilient stocks with low risk scores that can help you focus on businesses with steadier risk profiles.
- Hunt for value by working through a 614 high quality undiscovered gems that filters for quality fundamentals before the crowd catches on.
- Prioritise financial strength by reviewing the list of solid balance sheet and fundamentals (199 results) so potential ideas start with robust balance sheets and underlying stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com