


EN
BancFirst (BANF) Could Be 11% Undervalued Following Stronger Quarterly Earnings
Why BancFirst’s latest quarter is getting attention
BancFirst (BANF) just posted third quarter and nine month results that show higher net income and earnings per share versus last year, while also recording increased net charge offs during the period.
This combination of stronger profitability and higher credit costs gives investors fresh detail on how the regional bank’s lending book and earnings power are holding up as of late 2026.
Recent trading suggests investors are still weighing BancFirst’s higher earnings against rising credit costs. The share price is around US$110 and the 1 month share price return of 2.1% contrasts with a 3 year total shareholder return of 35.7%. This points to momentum that has cooled but not disappeared as the latest results land.
Scan a curated set of regional financial institutions with earnings profiles and balance sheets that rhyme with BancFirst using our list of solid balance sheet and fundamentals (24 results) for potential next ideas.
BancFirst trades below both analyst targets and an estimated intrinsic value, even after the recent pullback on higher charge offs. Is the market being sensibly cautious, or is it leaving too much on the table as earnings hold firm?
Most Popular Narrative: 11% Undervalued
BancFirst’s most followed narrative pegs fair value at $124.33, compared with the recent close around $110. This points to a moderate valuation gap that hinges on how well the bank turns current momentum into durable earnings.
Continued consolidation in the Tulsa market through the completed American Bank of Oklahoma integration and the planned Spirit BankCorp acquisition increases BancFirst’s branch footprint, loans and deposits in a key metropolitan area. This can support higher revenue and earnings if those assets are deployed efficiently.
See why 1 investors see BancFirst as 11% undervalued.
Result: Fair Value of $124.33 (UNDERVALUED)
Still, any slowdown in revenue against peers, or a meaningful deterioration in BancFirst’s efficiency ratio, could quickly challenge that 11% undervalued narrative.
Find out about the key risks to this BancFirst narrative.
Another View on BancFirst’s valuation
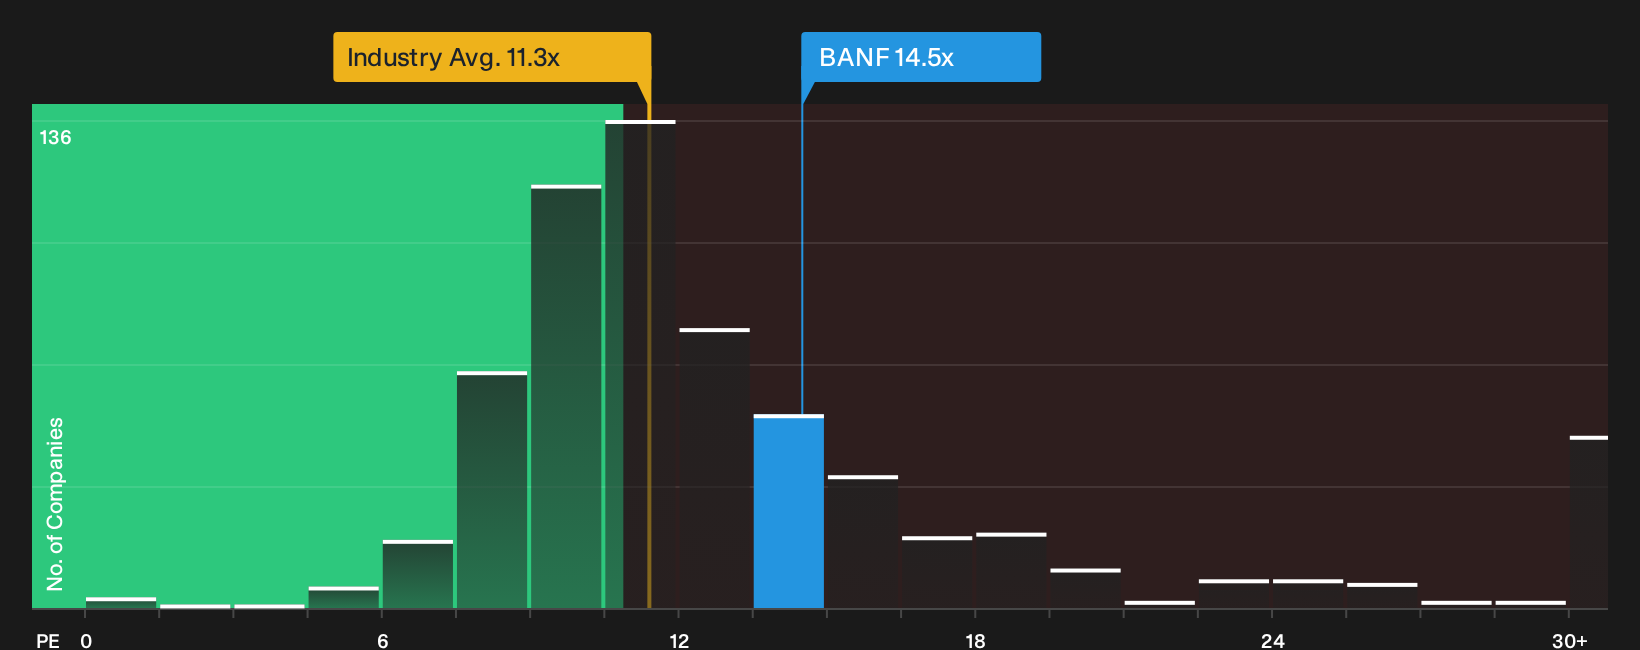
On simple pricing, BancFirst does not look as cheap as the 11% undervalued fair value story suggests. The stock trades on a P/E of 14.5x versus 11.4x for the US Banks industry and an estimated fair ratio of 11.4x, which points to a richer multiple and less room for error.
That richer P/E against both peers and the fair ratio implies investors are already paying up for BancFirst’s quality and consistency, so any slip in earnings or revenue trends could have an outsized impact on the share price. It is worth asking whether that premium still feels comfortable at this stage of the cycle or if you prefer a cleaner discount elsewhere, and the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on BancFirst’s valuation and quality can pull you in either direction, so move quickly, review the underlying data, and weigh both sides of the story by checking the 4 key rewards and 1 important warning sign.
Looking for more BancFirst investment ideas?
If BancFirst has sharpened your focus on quality and valuation, do not stop here. Broaden your watchlist using targeted screeners that surface focused sets of opportunities fast.
- Zero in on value by scanning a curated pool of companies that combine quality fundamentals with discounted pricing through the 33 high quality undervalued stocks.
- Build a steadier core by reviewing income focused stocks with robust payout profiles using the 5 dividend fortresses.
- Strengthen your shortlist by filtering for businesses backed by resilient finances and cleaner balance sheets via the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com