


EN
How Investors May Respond To Matador Resources (MTDR) Dividend Hike
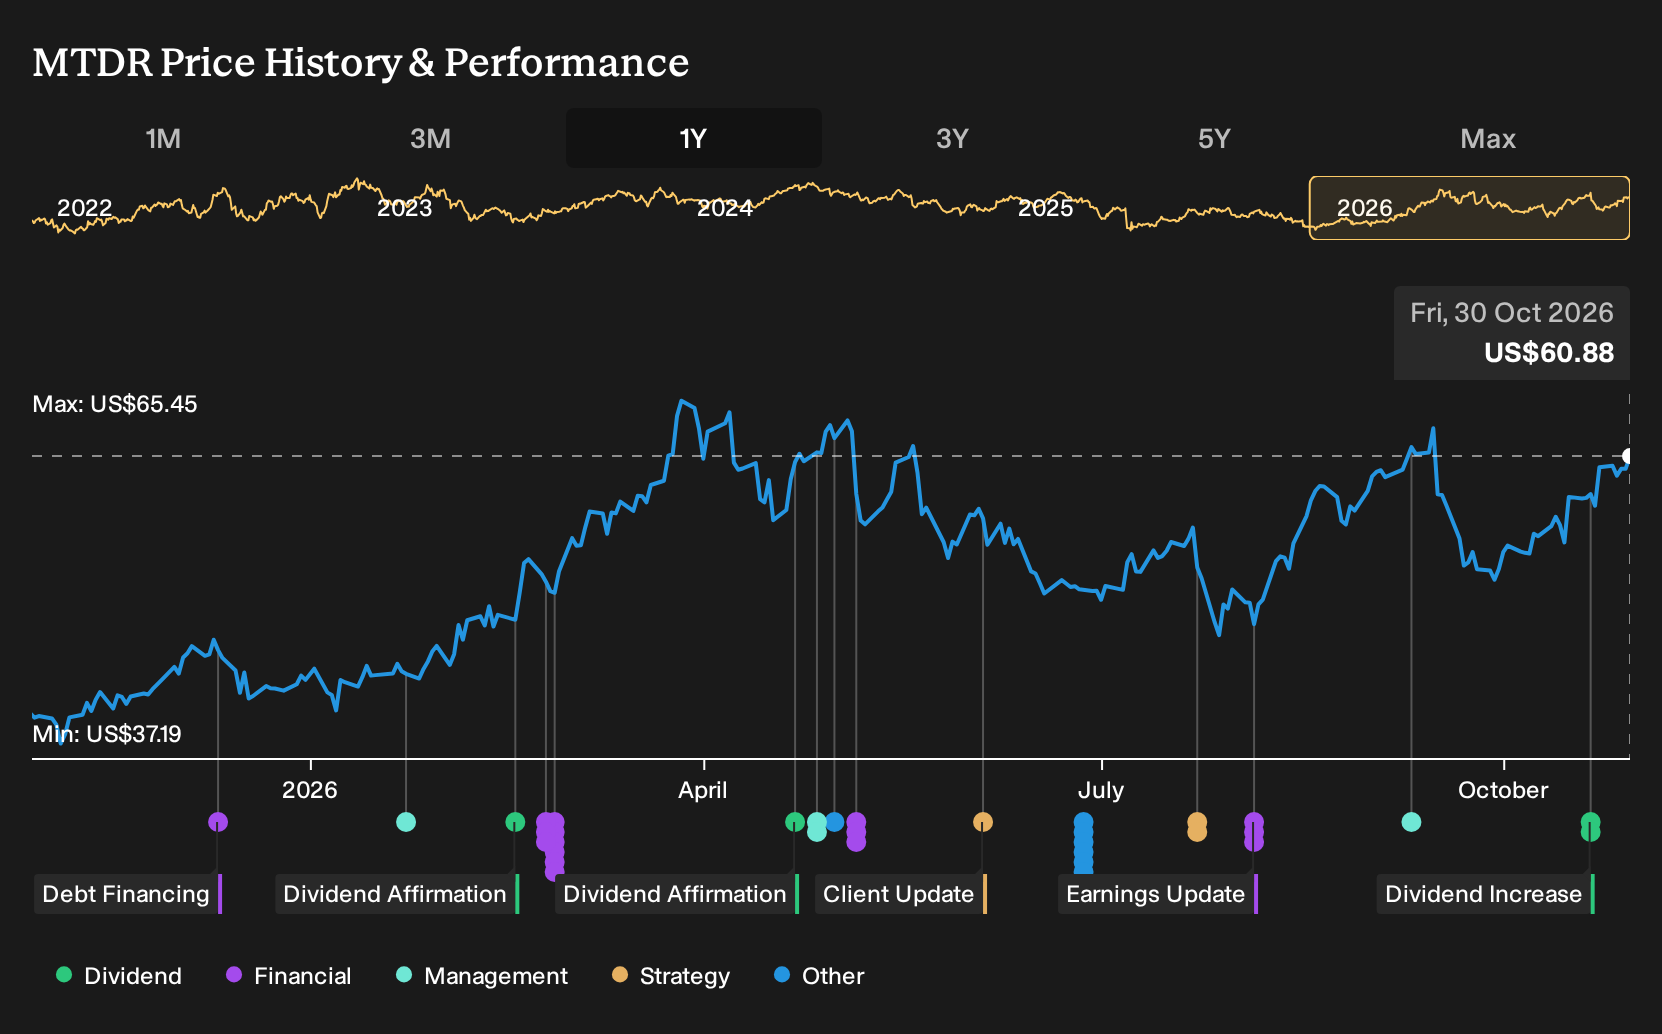
- Matador Resources reported that its board approved a quarterly cash dividend of $0.4375 per share, payable on 4 December 2026 to shareholders of record on 10 November 2026, and updated its policy to target $1.75 per share annually from the fourth quarter of 2026.
- The 17% uplift in the regular payout signals that Matador Resources is prioritising a larger, recurring cash return to equity holders funded by its operating base, rather than relying solely on variable distributions or buybacks.
- This article will examine how Matador Resources' higher base dividend commitment affects the investment narrative built around free cash flow.
Scan beyond Matador Resources and compare this richer payout profile with other dividend focused energy stocks using our hand picked 5 dividend fortresses for income ideas in the same space.
Matador Resources Investment Narrative Recap
To own Matador Resources, you need to be comfortable with a concentrated Delaware Basin footprint that leans on drilling efficiency, midstream expansion and firm transport deals to keep free cash flow healthy. The higher base dividend target does not change that core thesis. The near term swing factor still sits with execution on 2026 development plans and midstream uptime.
The biggest operational risk remains the same. Heavy exposure to one region and ongoing capital needs mean weaker commodity pricing or local disruption could pressure cash generation and slow debt reduction. A richer dividend commitment slightly tightens flexibility if well results, midstream projects or gas realizations underperform expectations.
The most relevant update is the new dividend policy itself, with the Board intending to pay US$0.4375 per share each quarter, or US$1.75 per year, from Q4 2026. That 17% lift from the prior US$1.50 annual level ties shareholder income expectations more directly to Matador Resources’ operating and midstream cash generation.
For you, the key question is whether the business can comfortably support that higher run rate while funding Delaware Basin drilling, midstream investments and debt service. The policy leans on the same catalysts analysts already highlight, such as cost efficient development and fee based midstream earnings, and it makes any misstep in those areas more visible in the payout conversation.
Matador Resources' narrative projects US$4.7b revenue and US$1.1b earnings by 2029. This implies 7.2% yearly revenue growth and an earnings increase of about US$376m from US$723.7m today.
Uncover why Matador Resources' fair value indicates a 15% potential upside to its current price before this discount to Matador Resources closes.
Exploring Other Perspectives
One alternate angle focuses on dividend risk rather than growth. The most cautious analysts, who were only pencilling in about US$4.4b of revenue and US$955.1m of earnings by 2029 before this dividend news, worry that tighter payout commitments could strain Matador Resources if commodity prices or drilling results disappoint. Their forecasts sketch a far more cautious path than the consensus. You can treat this dividend increase as a fresh data point and explore how both narratives might adjust from here.
Explore 3 other Matador Resources fair value estimates, including one that suggests it could be worth just $59.00.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Matador Resources research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Matador Resources. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Matador Resources' overall financial health at a glance.
Looking For More Ideas Beyond Matador Resources?
If you want to put Matador Resources in context, it helps to scan a broader watchlist and see how other businesses line up on income, valuation and balance sheet strength. The Simply Wall St Screener can surface different types of opportunities quickly so you can focus on what fits your own approach.
- If reliable income is your priority, start with companies that combine yield with balance sheet support through our 5 dividend fortresses.
- For investors who care most about quality at a sensible price, filter for resilient operations trading below estimated fair value using the 33 high quality undervalued stocks.
- If you want a shortlist of quieter stories with solid metrics, scan the 19 high quality undiscovered gems and look for businesses that match your risk and return expectations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com