


EN
How Investors May Respond To Sally Beauty Holdings (SBH) Higher Profit Outlook
- Sally Beauty Holdings recently saw its consensus estimate for upcoming quarterly earnings settle at $0.60 per share, which is higher than the earnings the business reported in the same period a year ago, while investors focus on how it manages category softness and expenses.
- The key angle is management’s cost work, with programs such as Fuel for Growth intended to support margins even as core care demand remains pressured.
- We will now look at how this updated profit outlook, anchored by Fuel for Growth cost actions, could shape Sally Beauty Holdings’ investment narrative.
Scan how Sally Beauty Holdings’ cost work compares with other potential opportunities by checking a curated list of 33 high quality undervalued stocks that pair disciplined spending with solid fundamentals.
Sally Beauty Holdings Investment Narrative Recap
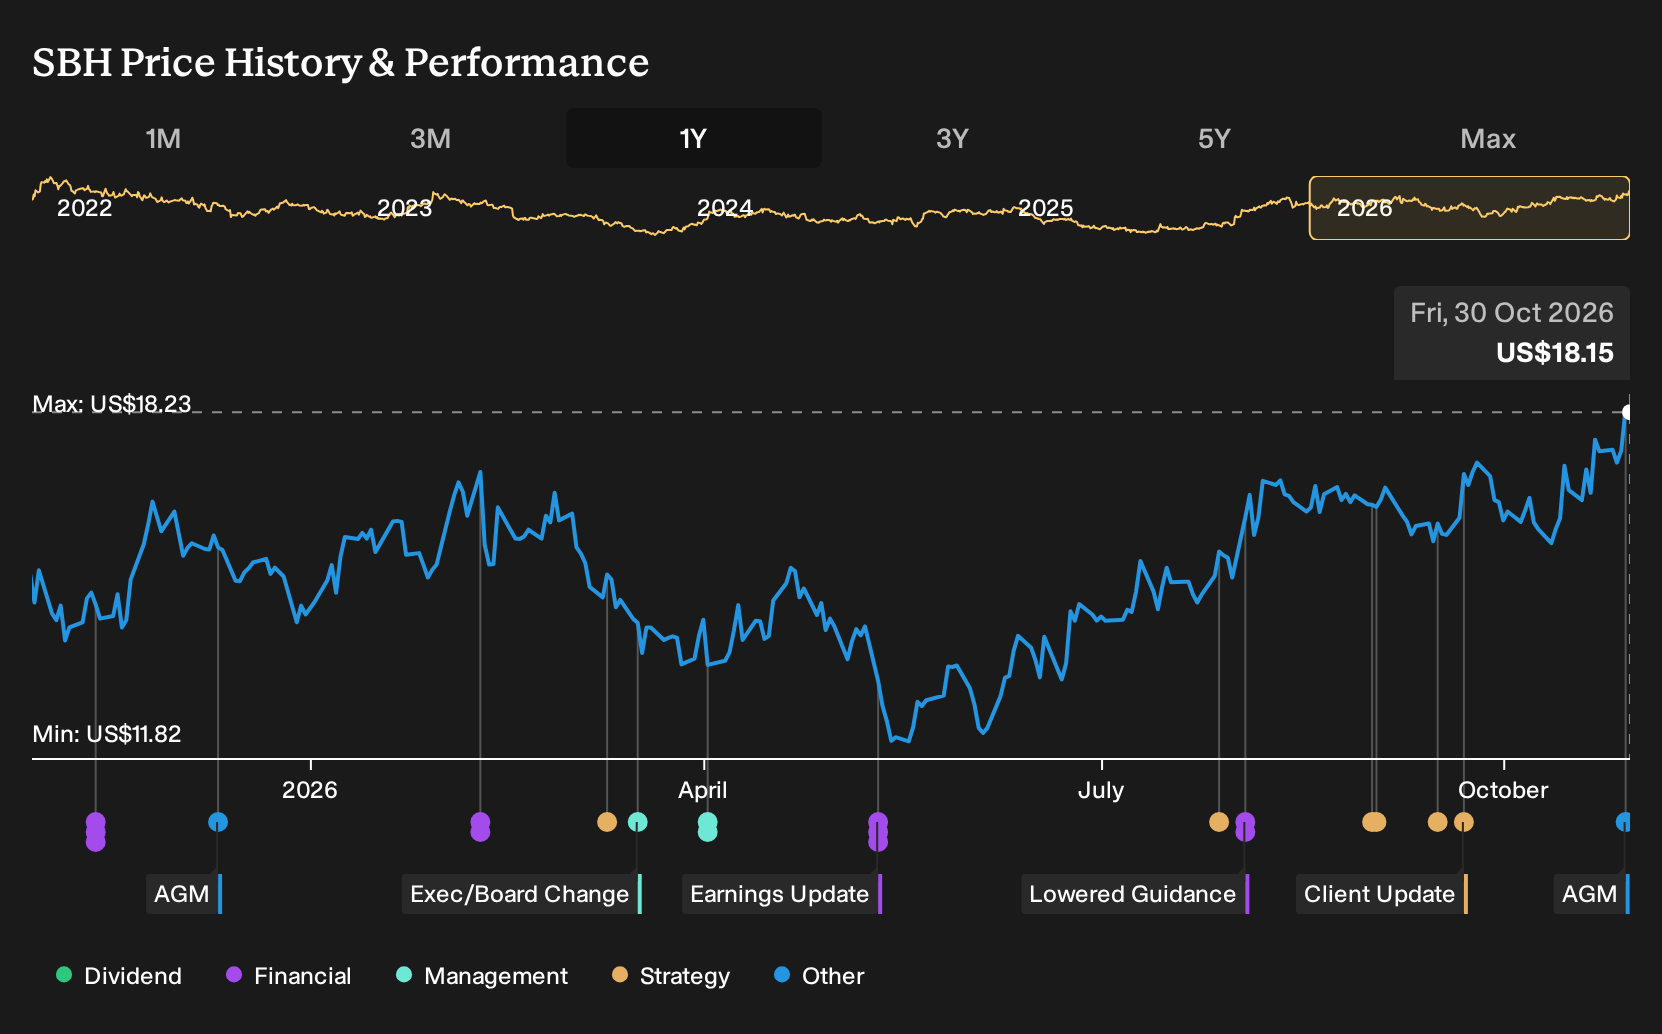
An investor in Sally Beauty Holdings needs to believe the retailer can keep squeezing more profit from a fairly slow growing top line while hair care and ancillary categories stay soft. The recent 4.7% move to US$18.23 and a month long return of 6% point to renewed attention on execution rather than a shift in the underlying story.
The short term catalyst still sits in execution of Fuel for Growth and broader cost work that supports earnings even as stylists lean more value focused. The biggest risk remains prolonged weakness in care, with global care sales recently under pressure and mix shifting away from higher priced products.
The most relevant piece of recent information is the updated consensus EPS estimate of US$0.60 for the upcoming quarter, which reflects expectations for higher earnings than the same period last year. That figure now reflects the market’s view on how Sally Beauty Holdings might handle category softness while keeping costs in check.
Focus turns to whether Fuel for Growth and related savings programs can support margins without hurting the in store experience or slowing investments in e commerce, fragrance and remodels such as Sally Ignited and Happy Beauty. If cost actions are implemented effectively, they can support the existing narrative that profitability can improve even with modest revenue growth.
Sally Beauty Holdings’ current earnings are US$192.3 million, with analysts forecasting US$266.7 million of earnings and US$3.9b of revenue by 2029, based on the provided assumption of 1.4% yearly revenue growth and an earnings increase of about US$74 million from today’s level.
Uncover why Sally Beauty Holdings' fair value indicates a 6% potential downside to its current price, a premium that may not be sustained.
Exploring Other Perspectives
For a very different angle on Sally Beauty Holdings, focus on the bullish view that treats Fuel for Growth as a powerful earnings engine. Those analysts were modelling revenue of about US$3.9b and earnings near US$272.1 million by 2029. That outlook predates the latest EPS reset, and opinions may change as fresh data becomes available.
Explore 2 other Sally Beauty Holdings fair value estimates, including one that suggests up to 295% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Sally Beauty Holdings research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sally Beauty Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sally Beauty Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Sally Beauty Holdings?
If the Sally Beauty Holdings story has sharpened your thinking about costs, earnings and risk, you can use that same lens to scan a wider universe of companies. The Simply Wall St Screener can help you quickly narrow the field to opportunities that better match your return goals and risk comfort.
- For investors hunting for quality at a reasonable entry point, consider a curated 33 high quality undervalued stocks that blend resilient cash flows with disciplined capital allocation.
- If income reliability matters to you, focus on companies in our 5 dividend fortresses that aim to balance yield with balance sheet strength.
- When capital preservation is near the top of your checklist, start with a 29 resilient stocks with low risk scores that score well on financial health and business stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com