


EN
COSCO SHIPPING Ports Stock Faces Margin Pressure After Revenue Growth】【。
- COSCO SHIPPING Ports reported Q3 2026 sales of US$484.33 million and net income of US$82.59 million, with basic EPS from continuing operations at US$0.0206.
- The nine month figures show higher sales and net income year to date, alongside slightly lower quarterly EPS. This points to pressure on profitability and raises questions around the payoff from heavier capital expenditure.
- We will examine how COSCO SHIPPING Ports' investment narrative is shaped by higher revenue, flat quarterly net income, and margin pressure.
COSCO SHIPPING Ports Investment Narrative Recap
For a shareholder in COSCO SHIPPING Ports, the core belief is that a larger global terminal network and more integrated logistics services can support resilient earnings, even when trade routes are under strain. The latest quarter shows higher sales and flat net income, so the near term catalyst is still about converting that wider footprint into better efficiency rather than headline revenue alone.
The biggest near term risk remains execution on the much higher 2026 CapEx budget of about US$756 million. With Q3 earnings per share slightly softer despite heavier spending, the question is whether new terminals and automation projects in places like Peru, Nansha and Spain can support returns without squeezing margins further.
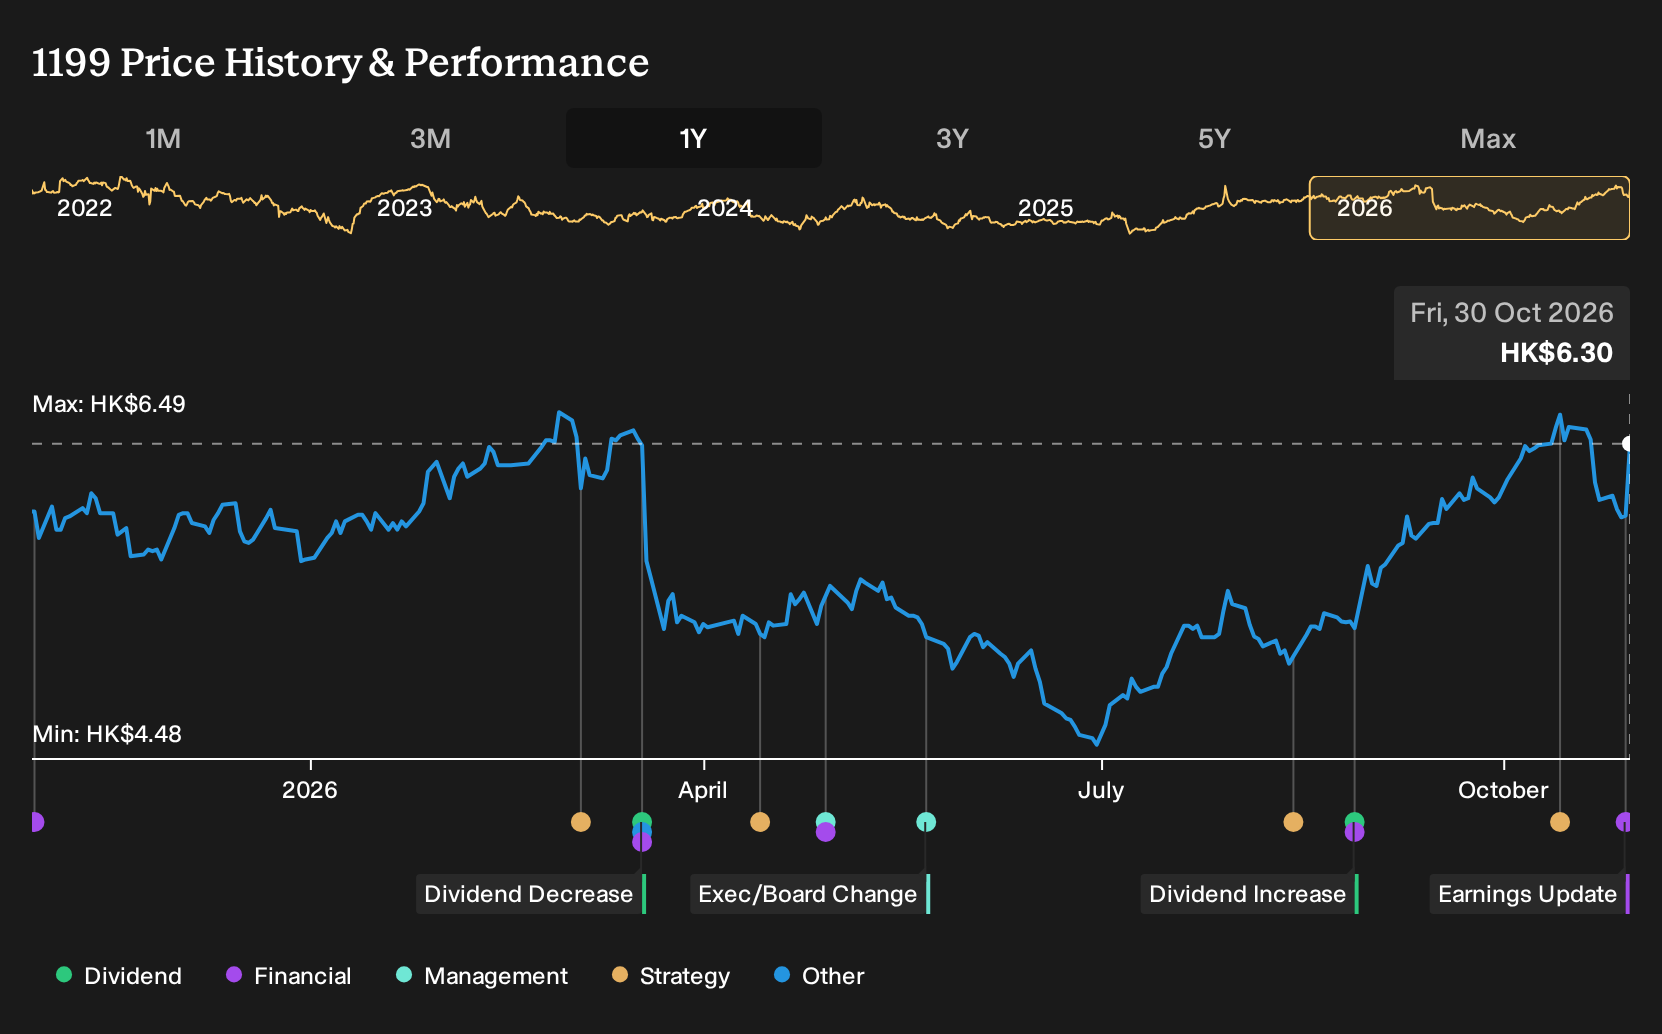
The Q3 2026 earnings release is the key data point here. Revenue for the quarter reached US$484.33 million, with net income of US$82.59 million and basic EPS from continuing operations of US$0.0206. Over nine months, COSCO SHIPPING Ports reported US$1,389.67 million of sales and US$316.26 million of net profit, giving EPS of US$0.0795.
Set against the enlarged CapEx program and the exposure to China linked trade corridors and Middle East routes, those figures keep the focus squarely on throughput growth, cost per TEU and Abu Dhabi volumes as practical catalysts. For investors, the operational story now hinges on whether that combination of global expansion, digital systems and value added logistics can offset margin pressure and the risk of softer earnings forecasts.
COSCO SHIPPING Ports' current earnings are about US$364.0 million, with analysts assuming revenue will grow by 3.2% a year and forecasting revenues of US$1.9b and earnings of US$362.6 million by 2029, which implies an earnings decline of about US$1.4 million from today.
Uncover why COSCO SHIPPING Ports' fair value indicates a 5% potential downside to its current price, suggesting that this premium may not hold.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$5.99 to US$9.70, so private investors are clearly not aligned on where COSCO SHIPPING Ports should trade. Use that spread as a prompt to test your own view against risks around Belt and Road exposure, heavier CapEx and potential route disruption.
Explore another COSCO SHIPPING Ports fair value estimate, including one that suggests it could be worth just HK$5.99.
The Verdict Is Yours
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your COSCO SHIPPING Ports research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for COSCO SHIPPING Ports. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate COSCO SHIPPING Ports' overall financial health at a glance.
Looking For More Investment Ideas Beyond COSCO SHIPPING Ports?
If COSCO SHIPPING Ports is already on your radar, use this earnings update as a springboard to widen your opportunity set. A few minutes with the Simply Wall St Screener can surface other businesses with balance sheets, cash flows and income profiles that better match your risk tolerance and income goals.
- If you want potential value combined with quality fundamentals, start by scanning 204 high quality undervalued stocks that meet strict cash flow and balance sheet checks.
- For investors who prefer getting paid while they wait, consider income focused opportunities by reviewing 222 dividend fortresses offering yields above 5% with an emphasis on stability.
- If capital preservation is front of mind, concentrate on resilience by filtering for 218 resilient stocks with low risk scores that score well on financial strength and volatility measures.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com