


EN
KomeriLtd (TSE:8218) Is Getting Attention Again, But What Is Behind It?
Komeri Ltd (TSE:8218) has just reported higher half-year sales and earnings, along with a new decision to pay an interim dividend of ¥29 per share, funded from retained earnings.
Against that backdrop, KomeriLtd’s share price has risen over the year, with a 1 month share price return of 4.55% and a year to date share price return of 13.99%. The 1 year total shareholder return of 23.70% reflects both price gains and dividends, suggesting momentum has been building around the latest earnings and the interim dividend decision.
Position KomeriLtd in context by scanning a curated 28 dividend fortresses that also focuses on stable income and consistent payout policies.The recent rally in KomeriLtd reflects fresh earnings and a higher interim dividend, but the share price now sits close to the latest target. How much upside is still on the table from here?
Price-to-Earnings of 11.6x: Is it justified?
On current numbers, KomeriLtd trades on a P/E of 11.6x, which screens as inexpensive compared to both its own estimated fair level and peers at recent prices around ¥3,910.
The P/E ratio compares the share price with annual earnings per share. For a retailer like KomeriLtd, it gives a quick read on how much investors are paying for each unit of profit, which matters when earnings are positive and relatively steady.
In this case, the stock changes hands at 11.6x earnings, below the estimated fair P/E of 12.8x and also below the JP Specialty Retail industry average of 13.4x. That points to the market applying a discount to KomeriLtd relative to both a modelled fair level and sector peers. This gap could potentially close if profit delivery and dividend consistency remain aligned with current expectations.
Against direct peers, the comparison is even starker. The P/E of 11.6x sits below both the 13.4x industry average and the peer group at 14.2x. This suggests that the market is pricing KomeriLtd more conservatively than similar retailers and below the 12.8x level that quantitative fair value work indicates as a possible reference point.
Explore the SWS fair ratio for KomeriLtd.
Result: Price-to-Earnings of 11.6x (UNDERVALUED)
Still, the KomeriLtd story can change quickly if earnings growth slows from current levels or if the share price moves above the recent target of ¥3,950.
Find out about the key risks to this KomeriLtd narrative.
Another View on KomeriLtd’s Value
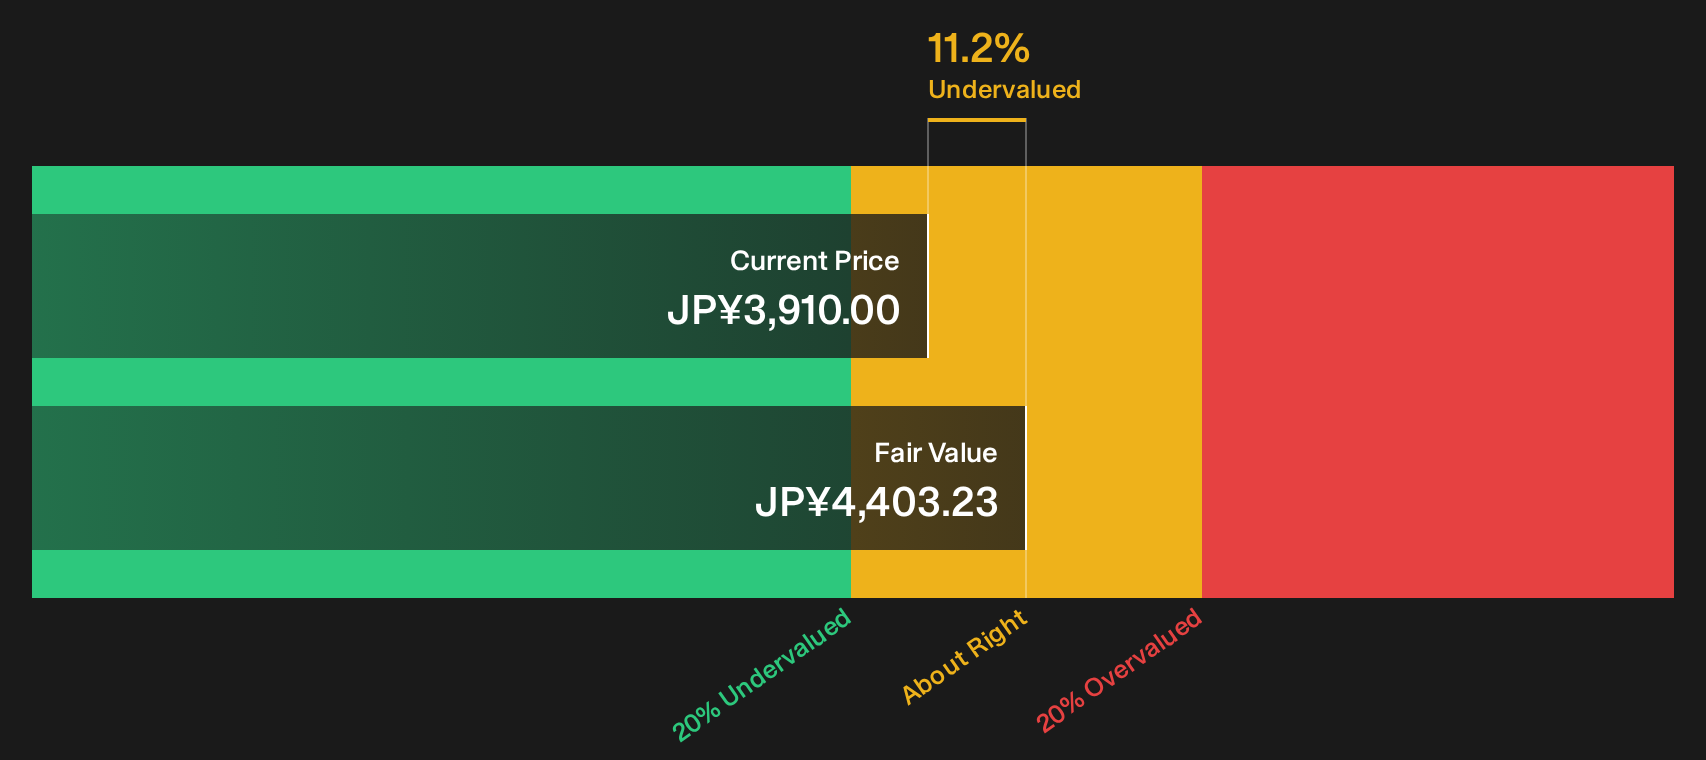
A different lens comes from the SWS DCF model, which values KomeriLtd’s future cash flows at about ¥4,403 per share versus the current ¥3,910 price. That points to roughly 11.2% upside on this method, so the stock screens as undervalued here too. Is this a cushion or a value trap in the making?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out KomeriLtd for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 16 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Optimistic about KomeriLtd after these numbers and valuation checks, or still unconvinced? Act while the data is fresh and weigh the balance of potential benefits using the 3 key rewards.
Looking for more investment ideas beyond KomeriLtd?
If KomeriLtd has sharpened your focus on value and income, extend that momentum and scan a few focused shortlists before the next move passes you by.
- Target resilient cash generators by reviewing a list of solid balance sheet and fundamentals (21 results) that highlights companies with balance sheets designed to handle tougher conditions.
- Hunt for mispriced quality by using the 16 high quality undervalued stocks to spot businesses where fundamentals and current prices are out of sync.
- Stack potential income streams by scanning a 69 high quality undiscovered gems that focuses on underfollowed opportunities with strong underlying financials.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com