


EN
Is RH (RH) Fully Priced After Earnings Concerns Hit Its Premium P/E?
RH (RH) is back in focus after fresh earnings expectations triggered a pullback, with projected earnings per share of $0.67 and a forward P/E that sits at a premium to peers.
Recent trading in RH has been choppy. The share price has climbed over the past week and delivered a strong 30-day share price return of 21.75%. However, it remains materially lower year to date with a share price return of 24.17% and a 1-year total shareholder return decline of 14.97% as investors reassess earnings risk against a premium P/E multiple.
Compare RH's premium P/E and earnings pressure with a curated group of retailers by scanning our 33 high quality undervalued stocks that already combine stronger fundamentals with more modest valuations.
RH has just delivered a sharp short-term rebound while earnings expectations and a premium P/E still hang over the story. Does that recent squeeze leave more upside for buyers, or does it reload the risk instead of the reward?
Most Popular Narrative: 12% Undervalued
RH last closed at $146.66, which sits below a most-followed fair value estimate of $165.82 that uses a 12.42% discount rate and incorporates detailed long-term assumptions on margins, capital spending, and new concepts.
The main thing that has to go right is that RH converts its heavy recent spend on European flagships, large-scale galleries, and new concepts like compounds into higher margin gallery productivity and sustained free cash flow as capital expenditures and international drag moderate.
The current valuation implies RH is undervalued relative to a setup in which RH Estates roughly doubles the addressable market, international galleries mature, and management’s long-term free cash flow and margin targets are met.
See why 14 investors see RH as 12% undervalued.
Result: Fair Value of $165.82 (UNDERVALUED)
Still, RH faces real pressure if the housing market stays weak, or if elevated short interest and cost headwinds push earnings away from the current narrative.
Find out about the key risks to this RH narrative.
Another View On RH Using Market Multiples
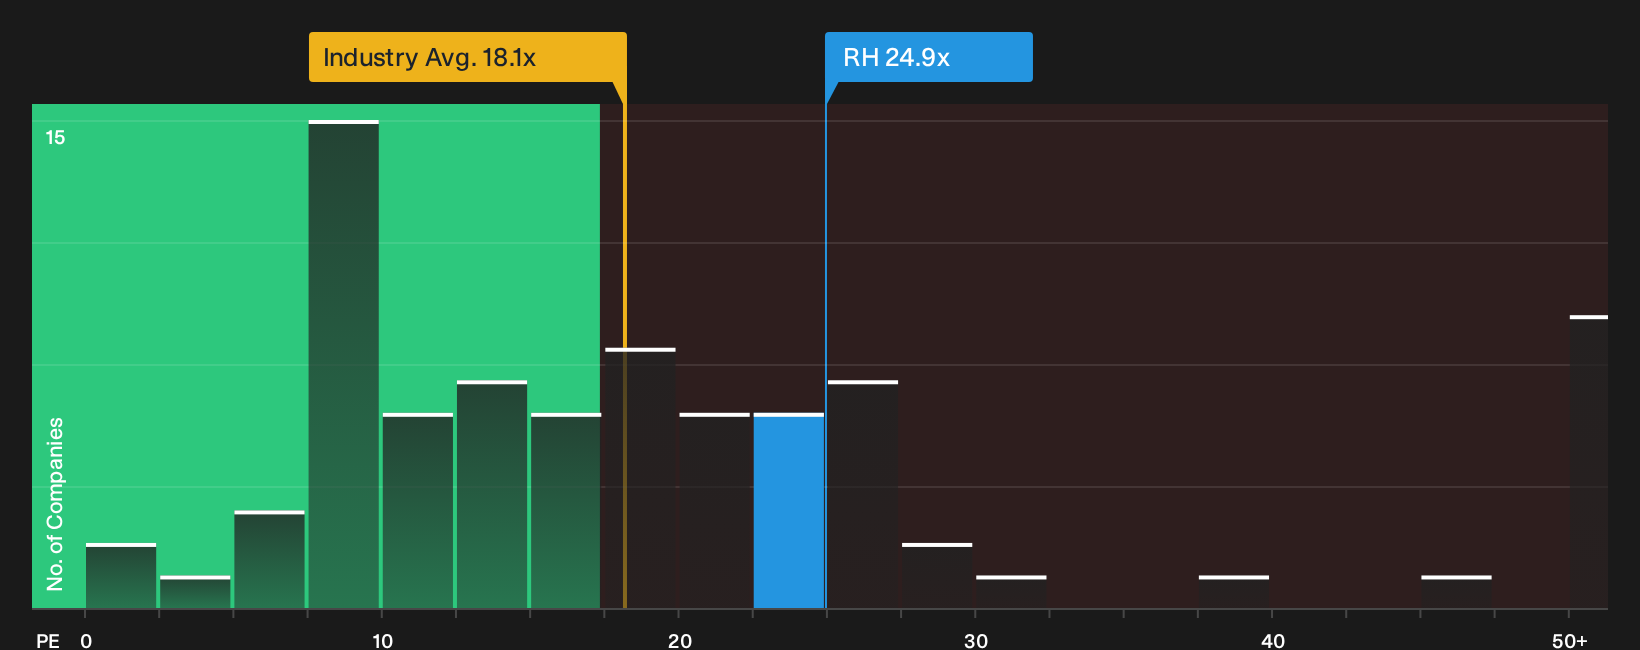
The fair value narrative paints RH as 12% undervalued at $165.82, yet the market’s own yardstick tells a different story. The current P/E sits at 24.9x compared with a fair ratio of 23.5x, a peer average of 21.7x, and a US Specialty Retail group at 18.1x.
That premium means investors are already paying up for RH versus both its direct rivals and the broader industry. This raises the bar on execution. If earnings or margins fall short of current expectations, there is less room for error before the share price adjusts. The key question is whether this multiple gap reflects durable quality or primarily indicates additional valuation risk at a challenging point in the cycle.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around RH can be confusing. Move quickly, check the numbers yourself, and decide what matters most for your portfolio with 1 key reward and 2 important warning signs
Looking for more investment ideas beyond RH?
If RH has your attention, do not stop there. Broaden your watchlist with other opportunities that line up better with your risk tolerance and income goals.
- Target resilient balance sheets and steady fundamentals by scanning a list of solid balance sheet and fundamentals (24 results) that can handle tougher conditions without breaking stride.
- Hunt for mispriced quality by reviewing a 33 high quality undervalued stocks that couples stronger financial profiles with valuations that still look reasonable.
- Amplify your income toolkit by zeroing in on a 5 dividend fortresses that focuses on higher yields backed by robust fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com