


EN
Becton Dickinson (BDX) Launches Liverty TIPS Stent Graft, Is The Stock Fully Priced?
Becton Dickinson (BDX) has drawn fresh attention to its interventional franchise with the U.S. launch of its Liverty TIPS Stent Graft for portal hypertension, supported by interim clinical data.
Becton Dickinson shares trade at US$197.88, with a 30-day share price return of 11.92% and a 90-day gain of 16.26%. The 1-year total shareholder return of 44.42% points to building momentum despite a modest year-to-date move of 1.51%.
Sprint ahead of the Liverty launch story by lining up other interventional and medical device opportunities through our hand picked 29 resilient stocks with low risk scores.Becton Dickinson has already rewarded anyone in early with a strong 1 year run, so the real tension now is simple. Do you pay up for that momentum, or do you wait for a cheaper shot at it?
Most Popular Narrative: 1% Overvalued
Becton Dickinson trades at $197.88 against a widely followed fair value estimate of about $195.67, so the narrative now leans slightly ahead of the current price and puts execution risk under a brighter spotlight.
The BD Excellence operating system continues to drive roughly 8% plant productivity and is being extended into commercial, R&D and AI enabled supply chain. This is intended to sustain margin expansion, support the roughly 25% adjusted operating margin and contribute to free cash flow and earnings over time.
What's behind 28 investors see Becton Dickinson as 1% overvalued.
Result: Fair Value of $195.67 (OVERVALUED)
Still, two pressure points could unsettle the current Becton Dickinson narrative: extended weakness in China and any further product quality or regulatory setbacks.
Find out about the key risks to this Becton Dickinson narrative.
Another Look At Becton Dickinson’s Valuation
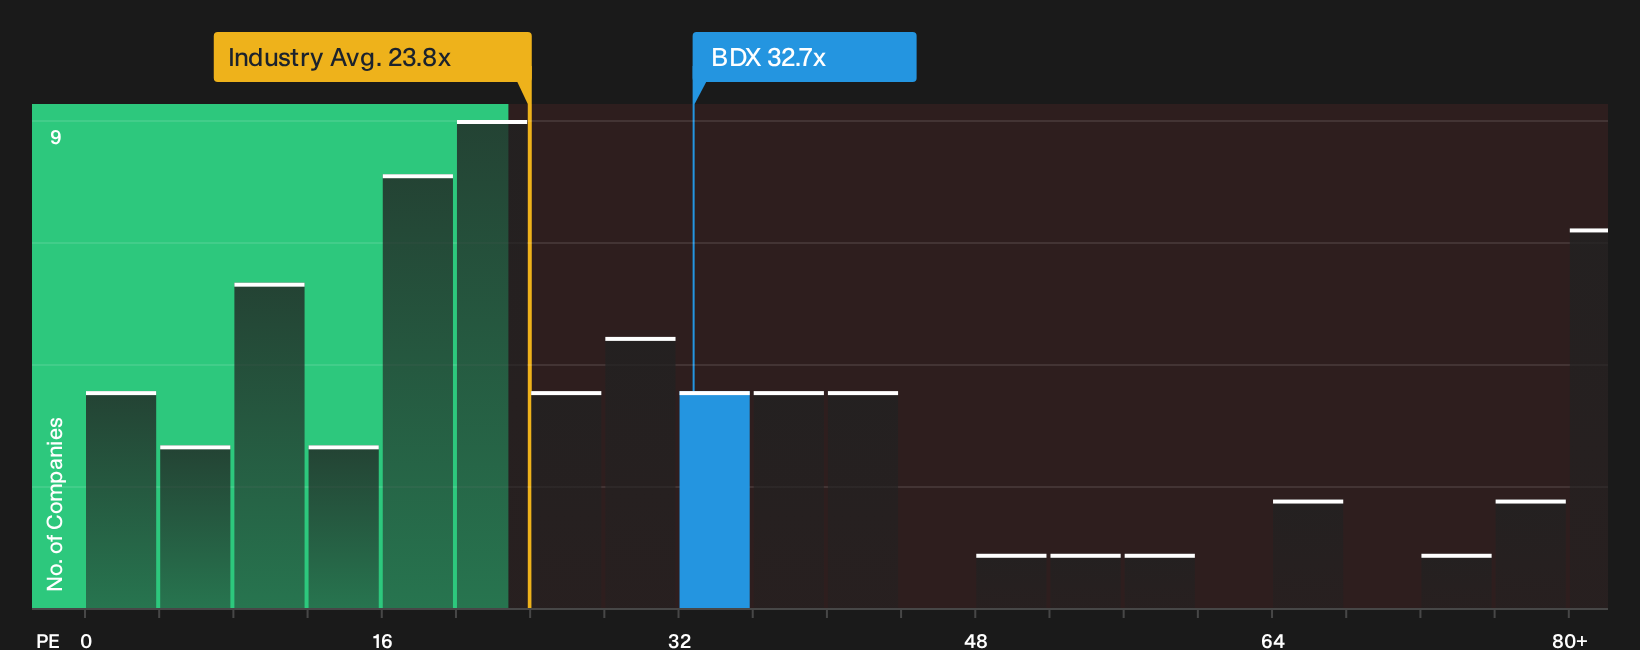
While the narrative fair value pegs Becton Dickinson at about $195.67 and labels the stock as slightly overvalued at $197.88, the ratio picture pulls in the other direction. The current P/E of 32.7x sits above both the US Medical Equipment sector on 23.8x and the peer group on 31.4x. Yet it still comes in below the 37.8x fair ratio, which means the market already bakes in a premium but has not fully closed the gap that regression work suggests it could move toward. For anyone weighing fresh capital, the question is whether that premium is a comfort or a margin of error waiting to be tested.
To see how those earnings multiples line up with the underlying drivers and where valuation pressure could build next, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed message or clear signal? Either way, if you want your view to be grounded in the numbers rather than the narrative, take a few minutes to weigh both the concerns and the potential upside through the 4 key rewards and 2 important warning signs.
Ready For More Ideas Beyond Becton Dickinson?
If you stop with Becton Dickinson, you only see part of the opportunity set. Use the Simply Wall Street Screener to surface fresh, data driven ideas before others move.
- Target quality at a discount and let the Screener highlight 33 high quality undervalued stocks that combine solid fundamentals with room for sentiment to catch up.
- Strengthen your foundation by focusing on balance sheet resilience using a curated list of solid balance sheet and fundamentals (24 results) that can handle tougher conditions.
- Get ahead of the crowd by scanning a focused pool of 19 high quality undiscovered gems that many investors are not watching yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com