


EN
Pinterest (PINS) Could Be 69% Below Fair Value Following Soft Q3 Guidance
Why Pinterest’s Q3 2026 Earnings Moved the Stock
Pinterest (PINS) triggered fresh attention after its Q3 2026 report combined double digit revenue growth with sharply lower profitability and softer guidance, as European advertising headwinds and new EU rules weighed on expectations.
Investors are weighing that mixed backdrop against strong user momentum and Pinterest’s push into AI powered recommendations and shopping tools, trying to judge how durable the current revenue pressures might be.
The mixed Q3 update landed on a stock that was already under pressure, with Pinterest’s 7 day share price return falling 13.26% and the year to date share price return down 27.11%. The 1 year total shareholder return declined 41.51% as softer guidance and European regulatory headwinds weighed on sentiment despite ongoing user and product progress.
Spot potential rebounds and under-the-radar peers reacting to similar ad and regulation pressures by scanning our hand picked 19 high quality undiscovered gems alongside Pinterest.After Pinterest’s sharp reset and softer guidance, the question is simple: does a US$19 share price still offer enough compensation for those European and profitability risks, as the valuation section spells out?
Price-to-Earnings of 62.3x: Is It Justified for Pinterest?
Pinterest closed at $19.36 while carrying a P/E of 62.3x, which is high next to both its peers at 19.9x and the wider US Interactive Media and Services group at 10.2x. That gap shows the market is attaching a much richer tag to each dollar of Pinterest’s earnings than to competitors with similar business models.
The P/E ratio compares the share price to earnings per share and is a quick way to see how much investors are willing to pay for current profits. For a digital advertising platform such as Pinterest, a higher multiple often reflects expectations that profit growth will be strong as the user base is monetised more effectively over time.
Here, the market is pricing Pinterest as a premium story. The current P/E of 62.3x is more than three times the peer average of 19.9x. It is also well above the estimated fair P/E of 32.9x that our fair ratio model suggests the stock could move toward over time. That difference indicates investors are accepting a heavy earnings premium relative to both similar companies and what the fair ratio model implies is justified.
Relative to the broader US Interactive Media and Services industry average of 10.2x, Pinterest’s 62.3x P/E is extremely rich. This points to a market view that its future earnings path would need to outpace typical sector outcomes in order to support this pricing.
Explore the SWS fair ratio for Pinterest.
Result: Price-to-Earnings of 62.3x (OVERVALUED)
Still, Pinterest’s heavy P/E premium could come under pressure if European regulatory costs bite harder than expected or if ad buyers pull back further on the platform.
Find out about the key risks to this Pinterest narrative.
Another View on Pinterest’s Valuation
The rich P/E story is only one lens. Our DCF model paints a very different picture, with Pinterest at $19.36 compared to an estimated future cash flow value of $62.65. That gap suggests the current earnings multiple might be missing part of the broader cash flow story.
DCF models rely on long term cash assumptions, so they can look very different from snapshot metrics like the P/E multiple. The question for you is simple: Which risk feels bigger, overpaying for near term earnings or underestimating Pinterest’s long term cash generation potential as the business matures?
Look into how the SWS DCF model arrives at its fair value.
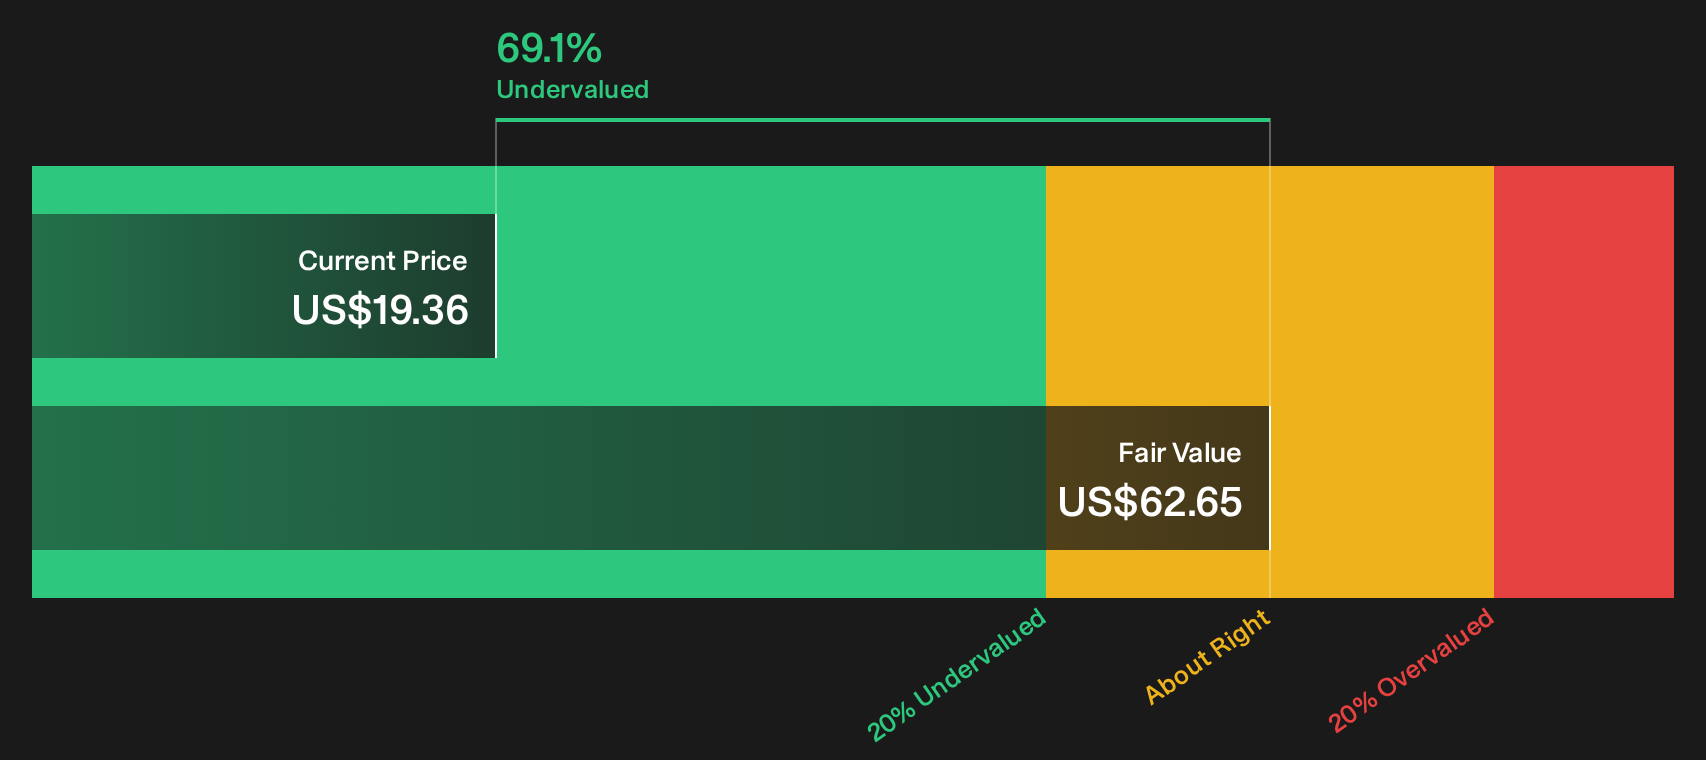
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Pinterest for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Pinterest’s valuation and guidance only matter if you use them. Act while the information is fresh and weigh both sides of the story with 2 key rewards and 3 important warning signs
Looking for more investment ideas beyond Pinterest?
Do not stop your research with Pinterest. Fresh opportunities often sit where fewer people are looking, and a few minutes with the right tools can change your watchlist.
- Target potential value opportunities by scanning companies that screen well on quality and pricing with 33 high quality undervalued stocks.
- Build a sturdier core for your portfolio by focusing on balance sheets that look resilient through the list of solid balance sheet and fundamentals (24 results).
- Hunt for under followed opportunities with healthy fundamentals using the 19 high quality undiscovered gems before everyone else catches on.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com