


EN
Callaway Golf (CALY) Brings Back Harry Arnett, Is The Stock A Bargain?
Brand leadership change puts Callaway Golf in focus
Callaway Golf (CALY) has brought back former marketing head Harry Arnett as Senior Vice President and Chief Brand Officer, a move that puts fresh attention on how the business positions its equipment and apparel portfolio with golfers.
Recent trading shows momentum trying to rebuild around Callaway Golf. The share price return is up 7.29% over the past week and 29.35% year to date, while the 1-year total shareholder return of 61.11% contrasts with a 20.59% share price decline over 90 days and a 48.44% total shareholder return decline over five years. This hints that investors are reassessing both growth potential and risk after Arnett’s appointment.
Capitalize on renewed interest in Callaway Golf by scanning a curated set of quality consumer-focused stocks with rebuilding momentum using the 19 high quality undiscovered gems.For Callaway Golf, Arnett’s return could signal deeper confidence in the underlying franchise rather than just a swing in sentiment. The key task now is to evaluate how that story compares with the current valuation.
Most Popular Narrative: 26% Undervalued
Callaway Golf’s most followed narrative pegs fair value at $20.40, set against a last close of $15.16. This puts brand moves like Arnett’s return in the context of a wider reset around margins, balance sheet strength, and product focus.
Callaway Golf has shifted to a simpler pure-play golf structure after selling Jack Wolfskin and a majority stake in Topgolf and repaying about US$1.4b of debt, which leaves the company in a net cash position and provides more flexibility to allocate future cash flow toward earnings accretive uses such as reinvestment and share count reduction.
See why 16 investors see Callaway Golf as 26% undervalued.
Result: Fair Value of $20.40 (UNDERVALUED)
Still, this Callaway Golf reset depends on discretionary golf and apparel spending holding up, and on input costs like materials and energy not eroding margin work.
Find out about the key risks to this Callaway Golf narrative.
Another View on Callaway Golf’s Valuation
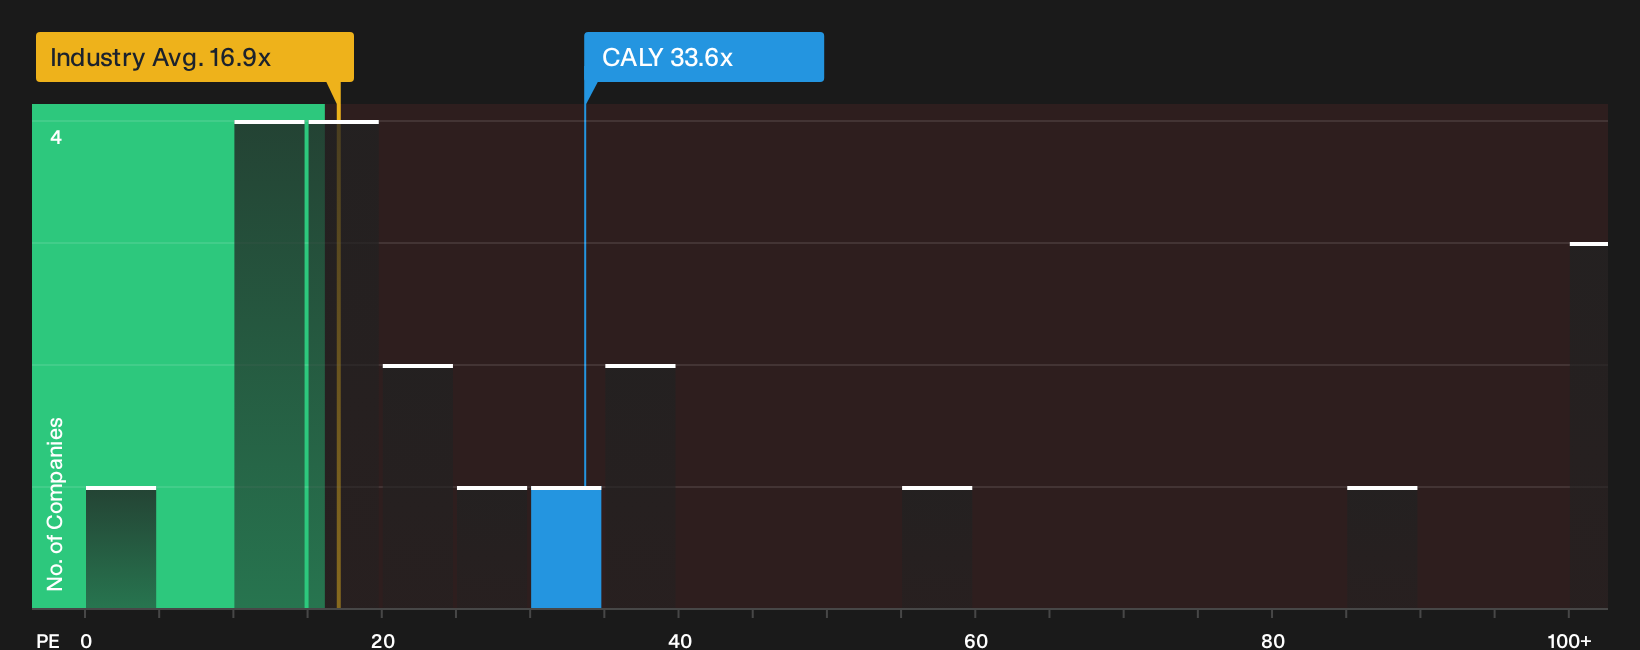
The story so far paints Callaway Golf as roughly 26% below fair value on a narrative and analyst target basis. Yet on a simple P/E yardstick, the picture looks less forgiving. CALY trades on 33.6x earnings, compared with a 21.6x peer average, a 16.9x global Leisure group, and a fair ratio estimate of 29.4x. That premium hints at valuation risk if earnings or sentiment slip, so the key question is which reference point investors give the most weight when the next set of numbers is released.
For a closer look at what this pricing gap could imply for future returns, including how earnings would need to develop for the current multiple to appear more in line with those references, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Callaway Golf is clearly split, with both concerns and bright spots in play. Take a close look at the numbers yourself and move quickly to form your own view based on the 3 key rewards and 2 important warning signs.
Looking for more Callaway Golf style ideas?
If Callaway Golf has you rethinking your watchlist, do not stop at a single ticker. Broaden your field of options so you are not relying on one story.
- Target steady compounding by scanning 33 high quality undervalued stocks that pair quality fundamentals with prices that sit below many investors’ radars.
- Protect your downside first and hunt through 29 resilient stocks with low risk scores that score well on balance sheet strength and business stability.
- Stay ahead of the crowd and work through 19 high quality undiscovered gems before the wider market starts paying attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com