


EN
Waste Connections (WCN) Could Be 11% Undervalued Following Earnings And A Dividend Rise
Waste Connections (WCN) is back in focus after its 21 October earnings release, which paired higher third quarter sales and profit with a 10% dividend increase and updated full-year guidance.
Investor attention has shifted quickly to the share price, with Waste Connections now trading at US$184.08 after a strong 19.7% 1 month share price return and a 10.7% 1 year total shareholder return. The 3 year total shareholder return of 41.3% points to momentum that has been building rather than fading.
Scan Waste Connections alongside a curated group of peers that combine recurring revenue and balance sheet strength using our list of solid balance sheet and fundamentals (24 results) for a broader view of quality in this corner of the market.
After that sharp move in Waste Connections on solid earnings, a higher dividend and fresh guidance, the real tension now sits in the valuation. Is most of the return already captured, or is there meaningful upside still on the table?
Most Popular Narrative: 11% Undervalued
Waste Connections is priced at $184.08 against a widely followed fair value view of about $206.90. This frames the recent rally as only part of the story rather than the full move.
The AI and broader digital initiative set, including the already deployed commercial pricing tool, a routing system now in pilot and customer service applications scheduled for rollout through 2027, is expected by management to deliver up to about 100 basis points of EBITDA margin uplift as these projects move from upfront spending to full operational impact.
Renewable natural gas projects, where about one third of the portfolio was already operating entering 2026 and all 12 planned plants are expected to be online by early next year with RNG capital outlays essentially complete by year end, are positioned to shift from a capital outflow to a new earnings and free cash flow contributor from 2027.
See why 19 investors see Waste Connections as 11% undervalued.
Result: Fair Value of $206.90 (UNDERVALUED)
Still, the Waste Connections story can change quickly if Chiquita Canyon cash outflows run above the US$100 million to US$150 million range or if fuel costs stay elevated.
Find out about the key risks to this Waste Connections narrative.
Another View: Waste Connections Through The P/E Lens
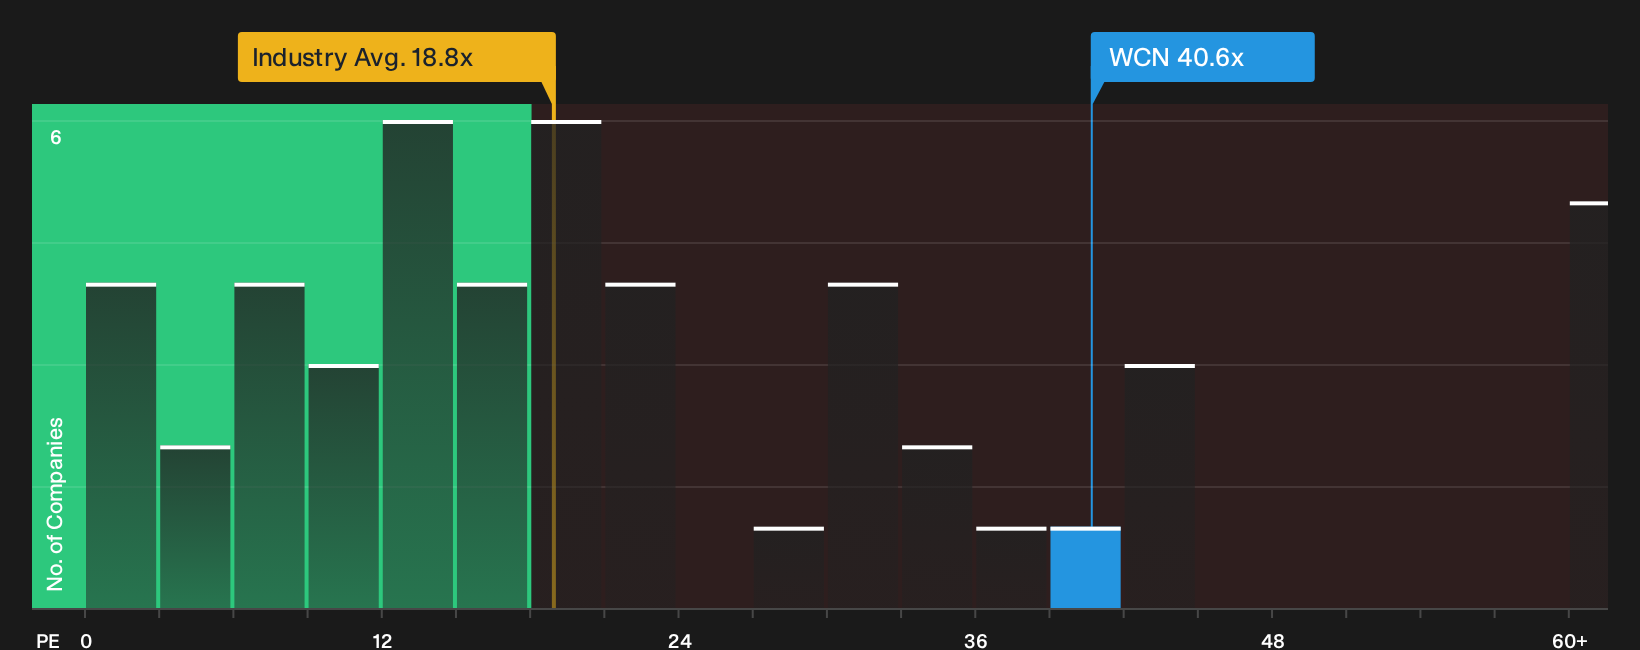
The DCF work points to Waste Connections trading at a discount to an estimated fair value, yet the P/E picture tells a very different story. At 40.6x earnings, the stock is priced far above the US Commercial Services average of 18.8x and a fair ratio estimate of 25.6x. That gap implies investors are paying a premium multiple. How comfortable are you with that kind of valuation stretch?
For a closer look at what this richer earnings multiple might mean alongside cash flow estimates, take a moment with See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Waste Connections story so far. Weigh the upside and the concerns quickly, then pressure test that view against 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Waste Connections?
If Waste Connections has sharpened your thinking on quality and price, do not stop here. Broader opportunity sits in how you build the rest of your portfolio.
Use the Simply Wall Street Screener to quickly surface other stocks and themes that match the kind of risk and return profile you want to target.
- Hunt for mispriced potential where strong fundamentals meet attractive entry points by scanning our 19 high quality undiscovered gems.
- Prioritise resilience and holdings that may help you sleep better at night by focusing on companies that rank well on stability using the 29 resilient stocks with low risk scores.
- Target a blend of dependable balance sheets and solid financial footing by filtering opportunities through the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com