


EN
Penumbra (PEN) Reports Q3 Growth And FDA Clearance, Is The Upside Already Priced In?
Why Penumbra Is Back in Focus After Q3 Earnings and FDA Clearance
Penumbra (PEN) has jumped back onto investor watchlists after two closely timed events. The company released third quarter 2026 results alongside fresh U.S. FDA clearance for its Lightning computer assisted vacuum thrombectomy technology in deep vein thrombosis.
Against that backdrop, Penumbra’s share price has held at US$318.95 with only modest recent moves. At the same time, a 1 year total shareholder return of about 40% and a 3 year total shareholder return above 60% suggest longer term momentum has been strong as investors weigh the FDA decision, continued revenue gains and margin pressure.
Scan how Penumbra’s mix of solid revenue growth and fresh FDA clearance compares with other high quality medical stocks by running the hand picked list of solid balance sheet and fundamentals (24 results).
After a strong 1 year run, a recent flat share price and fresh FDA news around Lightning have put Penumbra at an interesting crossroads. Is most of the upside already priced in, or not yet?
Most Popular Narrative: 12% Undervalued
Penumbra’s most followed narrative pegs fair value at $361.83, which sits above the last close of $318.95 and frames the current debate around how much of its thrombectomy and embolization story is already reflected in the price.
The embolization franchise, led by Ruby XL and Swift coils with strong middle meningeal artery embolization uptake and backed by a dedicated embolization sales team of more than 50 people, is emerging as a second pillar alongside thrombectomy. It can increasingly contribute to revenue diversification and operating margin leverage.
See why 5 investors see Penumbra as 12% undervalued.
Result: Fair Value of $361.83 (UNDERVALUED)
Still, the narrative around Penumbra can be tested quickly if margin progress stalls, or if the Boston Scientific deal introduces more cost and integration friction.
Find out about the key risks to this Penumbra narrative.
Another View: What Penumbra’s P/E Ratio Is Signalling
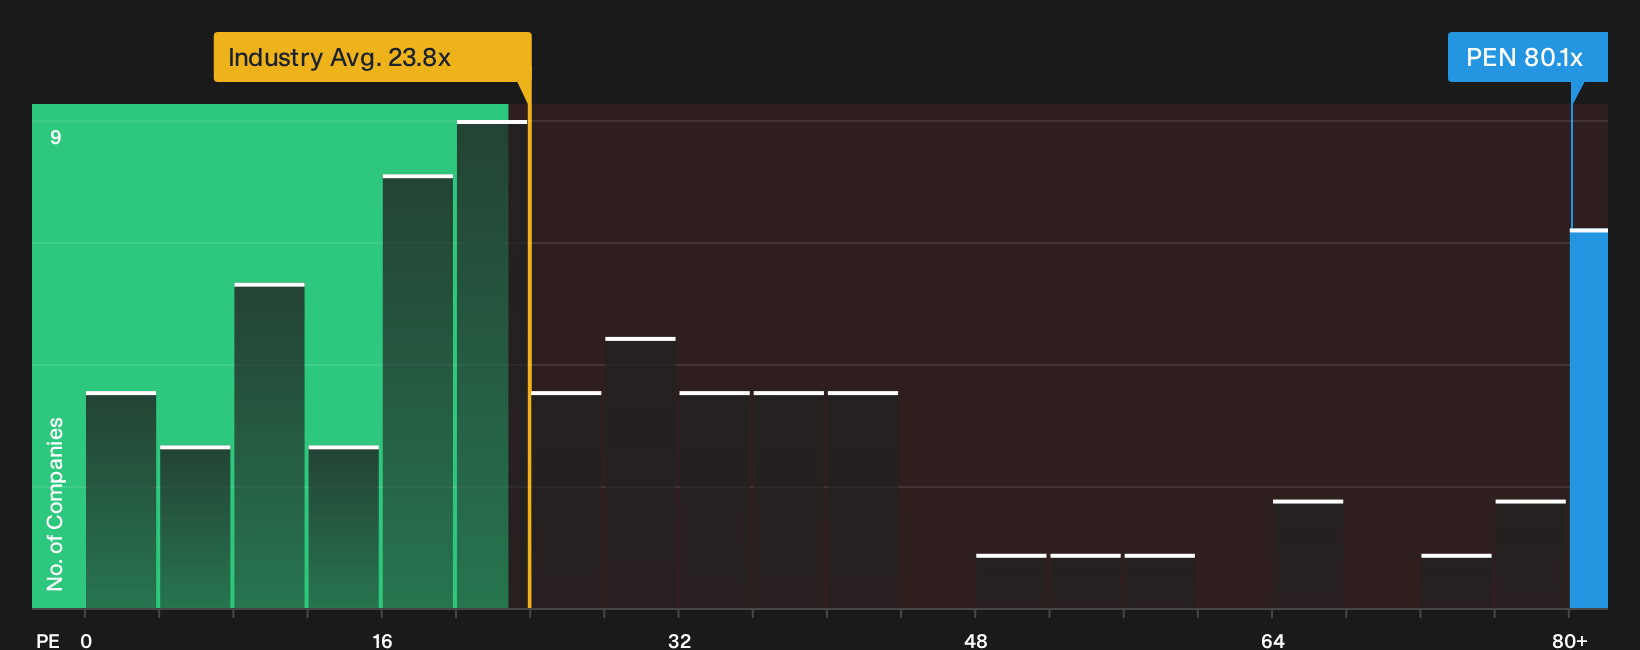
Penumbra may look undervalued against the US$361.83 fair value from the analyst model, but the current P/E of 80.1x tells a different story. The sector trades around 23.8x, while the fair ratio sits at 28.7x, which points to a rich valuation that could compress if expectations cool.
For anyone weighing that gap between current pricing and the fair ratio, it helps to stress test the optimism baked into today’s multiple and ask what sort of earnings path would justify staying this far above peers.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Penumbra is clearly split, which is exactly when it helps to look under the hood yourself and not rely on headlines. To see why some investors are still optimistic about the upside potential, take a closer look at 1 key reward.
Looking for more investment ideas beyond Penumbra?
If you stop with Penumbra, you risk missing other opportunities that fit your style, your risk tolerance, and the kind of portfolio you actually want to build.
- Target potential mispricing by scanning companies that combine quality fundamentals with appealing valuations through the 33 high quality undervalued stocks.
- Build a steadier income stream by focusing on robust payers and consistent cash generators via the 5 dividend fortresses.
- Dial back portfolio risk by concentrating on businesses that show financial resilience using the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com