


EN
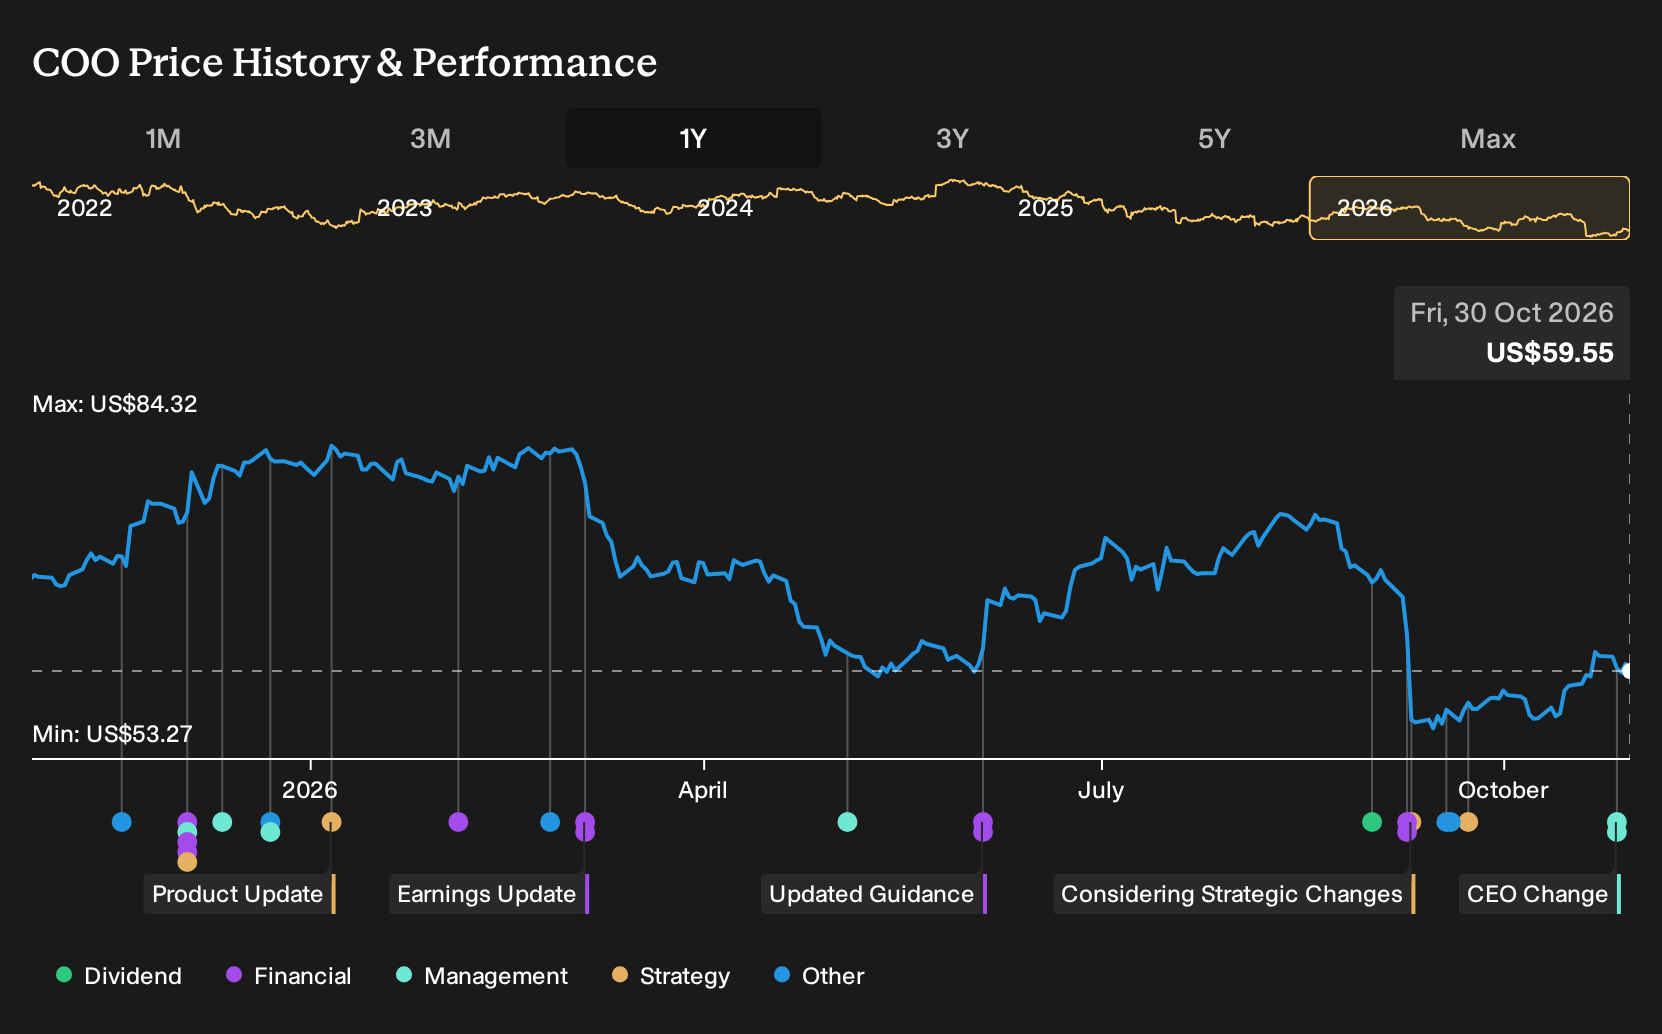
How Investors Are Reacting To Cooper (COO) CEO Exit And Board Refresh
- Cooper Companies reported a leadership overhaul after longtime president and CEO Albert G. White III stepped down from his executive roles and board seat in October 2026. Independent director Walter M. Rosebrough Jr. is taking over as executive chair and assuming day to day operational oversight while a formal CEO search progresses.
- The reshaped board now leans more heavily on veteran medical device operators such as Rosebrough and incoming director Shlomo Nachman. It is directly targeting execution on product mix, manufacturing, and capital allocation at a time when Cooper Companies is working through slower organic growth and efficiency efforts.
- We will now look at how Cooper Companies' investment narrative could be influenced by Rosebrough taking operational control as executive chair.
Scan how other medical device and healthcare operators are positioned for leadership-driven breakouts by reviewing the hand-picked 29 resilient stocks with low risk scores along with the changes at Cooper Companies.
Cooper Companies Investment Narrative Recap
To stay invested in Cooper Companies, you need to believe the premium lens and myopia management story still matters more than short term noise. The big near term swing factor is whether execution on MyDay and MiSight can offset softer Asia Pacific demand and the ongoing rationalization of older hydrogel products, which are already described as down double digits.
The largest risk remains that weaker reported growth, like CooperVision’s essentially flat Q3 2026 revenue, hints at a slower mix shift than hoped. The CEO and board shake up looks important but not yet thesis breaking. It mainly adds scrutiny on whether operations, litigation exposure at CooperSurgical, and capital deployment actually tighten up.
The most relevant fresh development is Walter Rosebrough stepping in as executive chair with direct oversight of daily operations while the CEO search runs through a dedicated board committee. For a business juggling manufacturing efficiency projects, AI enabled inventory work and MyDay production, having a long tenured medical device operator at the controls matters for near term execution risk.
His background at STERIS and current role on other healthcare boards means Cooper Companies now has a chair who is deeply familiar with product driven businesses, M&A, and complex regulatory settings. That experience aligns closely with the issues investors are watching, including CooperSurgical legal exposure, fertility growth projects, and how firmly the contact lens portfolio tilts toward higher priced daily silicone hydrogels.
Cooper Companies' narrative projects US$4.9b revenue and US$779.8m earnings by 2029. This assumes 4.8% yearly revenue growth and an earnings increase of about US$209.5m from US$570.3m today.
Uncover why Cooper Companies' fair value indicates an 11% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame Cooper Companies around margin expansion rather than leadership risk. Before this CEO shake up, the bullish camp was modeling profit margins rising from 13.5% to 18.8% and earnings reaching about US$918.6m by 2029. You can compare that more upbeat view with today’s board changes and decide which storyline feels more realistic to you.
Explore 5 other Cooper Companies fair value estimates, including one that suggests as much as 113% potential upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your Cooper Companies research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Cooper Companies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate Cooper Companies' overall financial health at a glance.
Looking For More Investment Ideas Beyond Cooper Companies?
Once you have a view on Cooper Companies, it helps to cross check that thinking against a wider watchlist of potential opportunities. A focused screener can save time and surface businesses that fit your risk profile, income goals, or preference for balance sheet strength.
- If you want stability first and foremost, start with a 29 resilient stocks with low risk scores that keeps overall risk scores in check while you compare potential returns.
- For investors hunting for mispriced quality, filter for a 33 high quality undervalued stocks that blend strong fundamentals with room for a possible re rating.
- Income focused readers can anchor their research around 5 dividend fortresses that concentrate on higher yield payouts backed by solid financials.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com