


EN
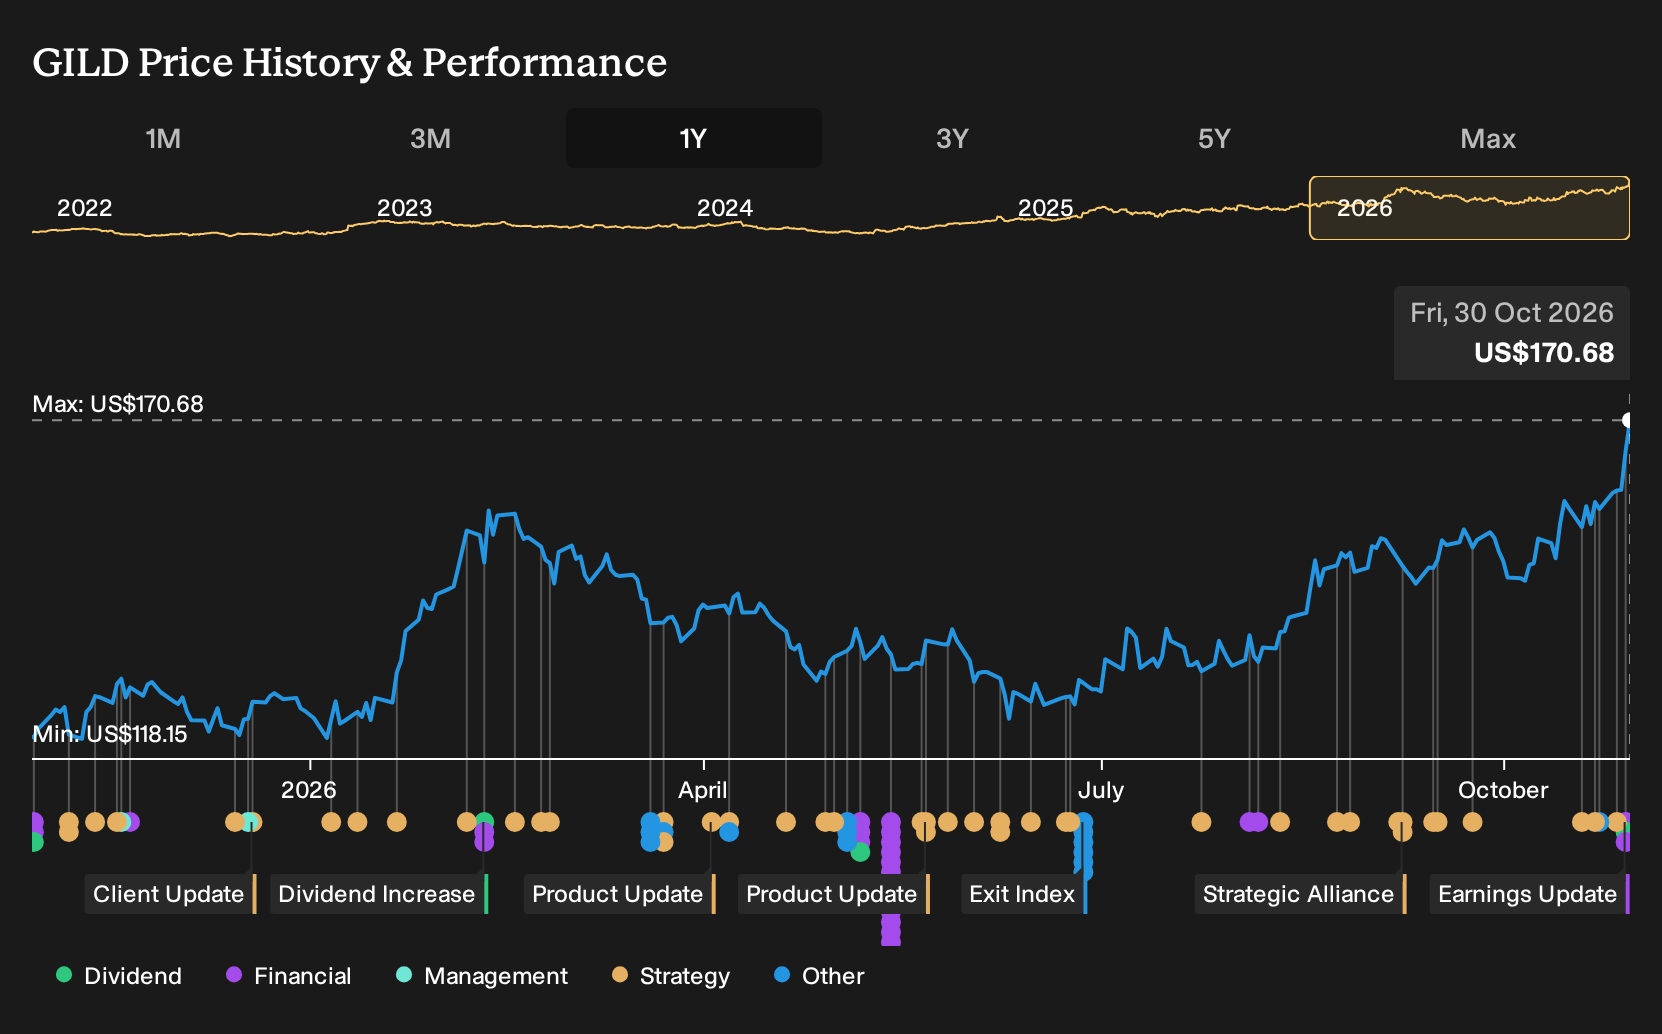
Did Earnings Beat Just Shift Gilead Sciences (GILD) Investment Narrative?
- Gilead Sciences reported third quarter 2026 revenue of US$8.3b with earnings above market expectations, raised full year product sales guidance, and highlighted strong demand across its HIV, oncology and liver disease portfolios.
- The full year outlook now includes higher projected product sales alongside a GAAP loss tied to more than US$12b of acquired R&D. This shows how Gilead Sciences is trading near term profitability for a larger pipeline in HIV, oncology and inflammation.
- We will now look at how Gilead Sciences’ upgraded 2026 sales guidance reshapes the investment narrative around its HIV led portfolio.
Scan how Gilead Sciences’ HIV and liver disease story compares with peers by lining up other healthcare stocks on our hand picked 34 healthcare AI stocks.
Gilead Sciences Investment Narrative Recap
To stay invested in Gilead Sciences, you need to be comfortable with a business that is plowing sizeable cash into acquired R&D while leaning on HIV, oncology and liver disease for near term momentum. The latest quarter showed higher revenue alongside lower net income, and management now guides to a larger GAAP loss in 2026 tied to acquired R&D.
The main short term catalyst is execution across the HIV franchise and newer launches like Livdelzi, since this portfolio is driving the upgraded product sales outlook. The biggest near term risk is that heavy dependence on HIV meets pricing pressure or softer demand, which could make those larger R&D charges feel heavier.
The most relevant update for that story is Gilead Sciences’ revised 2026 outlook. Management lifted expected product sales to US$31.0b to US$31.3b, while also flagging a larger projected operating loss and a wider GAAP diluted loss per share range due to about US$12.4b of acquired R&D this year.
For you, that combination ties the investment case directly to pipeline execution. Higher near term losses raise the bar on future approvals and commercial rollouts, especially in HIV and oncology. If those programs ramp more slowly or face tougher pricing than assumed, the earnings drag from this R&D heavy year could be harder to absorb.
Gilead Sciences’ current analyst script points to revenues of US$36.4b and earnings of US$11.8b by 2029, based on an assumed 5.6% yearly rise in revenue and an earnings swing of US$15.7b from a US$3.9b loss today to that future profit level.
Uncover why Gilead Sciences' fair value indicates a 3% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Gilead Sciences’ long acting HIV prevention push as the key swing factor. Before this quarter’s update, they were modelling revenue rising to about US$39.1b and earnings of US$16.4b by 2029. That is a much richer story than consensus and could shift again once this new guidance is fully digested.
Explore 5 other Gilead Sciences fair value estimates, including one that indicates a potential increase of up to 88% from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Gilead Sciences research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Gilead Sciences. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Gilead Sciences' overall financial health at a glance.
Looking for more investment ideas beyond Gilead Sciences?
Once you have a handle on Gilead Sciences, it can help to widen your watchlist with other stocks that match your risk comfort and income goals using the Simply Wall St Screener.
- If capital preservation is your first filter, you can start with a set of companies that score well on stability and financial risk by checking out 29 resilient stocks with low risk scores.
- For investors looking for quality at a reasonable price, you can broaden your opportunity set with our collection of 33 high quality undervalued stocks.
- If income is a priority, you can build a shortlist of potential payers by reviewing a curated set of 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com