


EN
Richards Group Inc. (TSE:RIC) Just Released Its Third-Quarter Earnings: Here's What Analysts Think
Last week saw the newest quarterly earnings release from Richards Group Inc. (TSE:RIC), an important milestone in the company's journey to build a stronger business. Richards Group reported in line with analyst predictions, delivering revenues of CA$110m and statutory earnings per share of CA$1.44, suggesting the business is executing well and in line with its plan. Earnings are an important time for investors, as they can track a company's performance, look at what the analysts are forecasting for next year, and see if there's been a change in sentiment towards the company. So we gathered the latest post-earnings forecasts to see what estimates suggest is in store for next year.
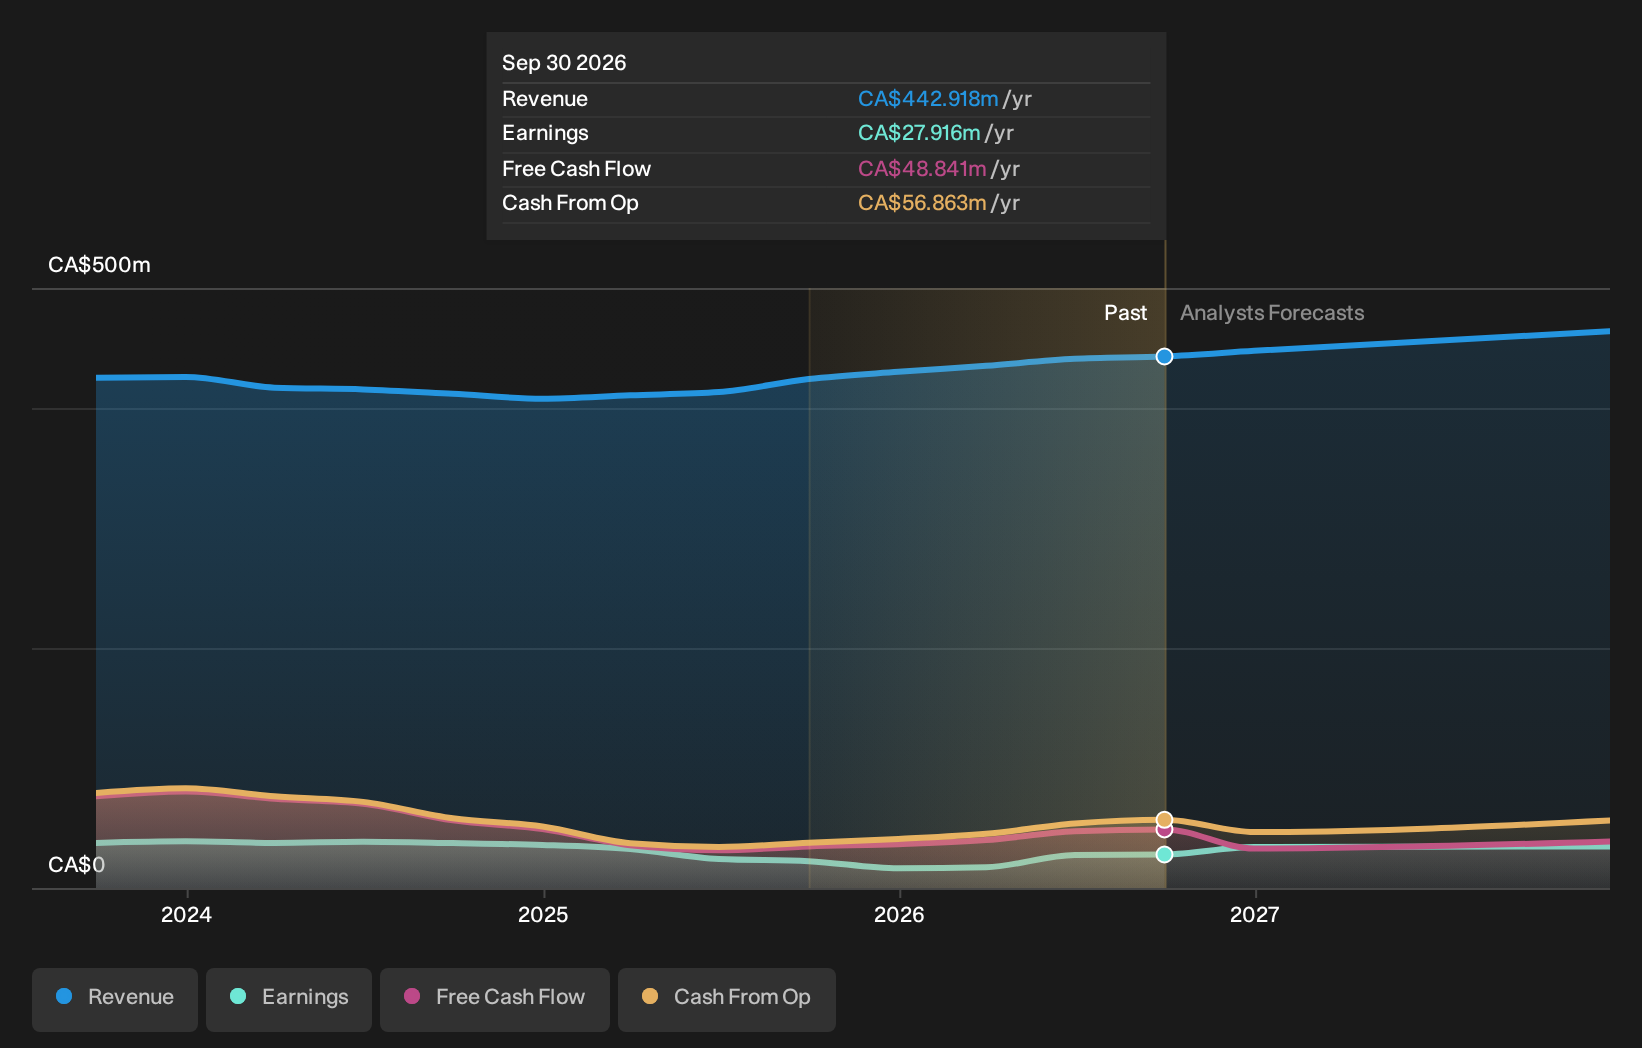
Taking into account the latest results, the most recent consensus for Richards Group from three analysts is for revenues of CA$464.0m in 2027. If met, it would imply an okay 4.8% increase on its revenue over the past 12 months. Per-share earnings are expected to ascend 19% to CA$3.13. Yet prior to the latest earnings, the analysts had been anticipated revenues of CA$464.0m and earnings per share (EPS) of CA$3.13 in 2027. So it's pretty clear that, although the analysts have updated their estimates, there's been no major change in expectations for the business following the latest results.
See our latest analysis for Richards Group
The analysts reconfirmed their price target of CA$41.33, showing that the business is executing well and in line with expectations. The consensus price target is just an average of individual analyst targets, so - it could be handy to see how wide the range of underlying estimates is. Currently, the most bullish analyst values Richards Group at CA$42.00 per share, while the most bearish prices it at CA$41.00. With such a narrow range of valuations, the analysts apparently share similar views on what they think the business is worth.
Another way we can view these estimates is in the context of the bigger picture, such as how the forecasts stack up against past performance, and whether forecasts are more or less bullish relative to other companies in the industry. One thing stands out from these estimates, which is that Richards Group is forecast to grow faster in the future than it has in the past, with revenues expected to display 3.8% annualised growth until the end of 2027. If achieved, this would be a much better result than the 1.4% annual decline over the past five years. Compare this against analyst estimates for the broader industry, which suggest that (in aggregate) industry revenues are expected to grow 4.2% annually. So while Richards Group's revenues are expected to improve, it seems that it is expected to grow at about the same rate as the overall industry.
The Bottom Line
The most important thing to take away is that there's been no major change in sentiment, with the analysts reconfirming that the business is performing in line with their previous earnings per share estimates. Happily, there were no real changes to revenue forecasts, with the business still expected to grow in line with the overall industry. The consensus price target held steady at CA$41.33, with the latest estimates not enough to have an impact on their price targets.
Following on from that line of thought, we think that the long-term prospects of the business are much more relevant than next year's earnings. We have estimates - from multiple Richards Group analysts - going out to 2027, and you can see them free on our platform here.
You can also view our analysis of Richards Group's balance sheet, and whether we think Richards Group is carrying too much debt, for free on our platform here.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.