


EN
What Sweco (OM:SWEC B)'s Earnings And Contract Wins Mean For Shareholders
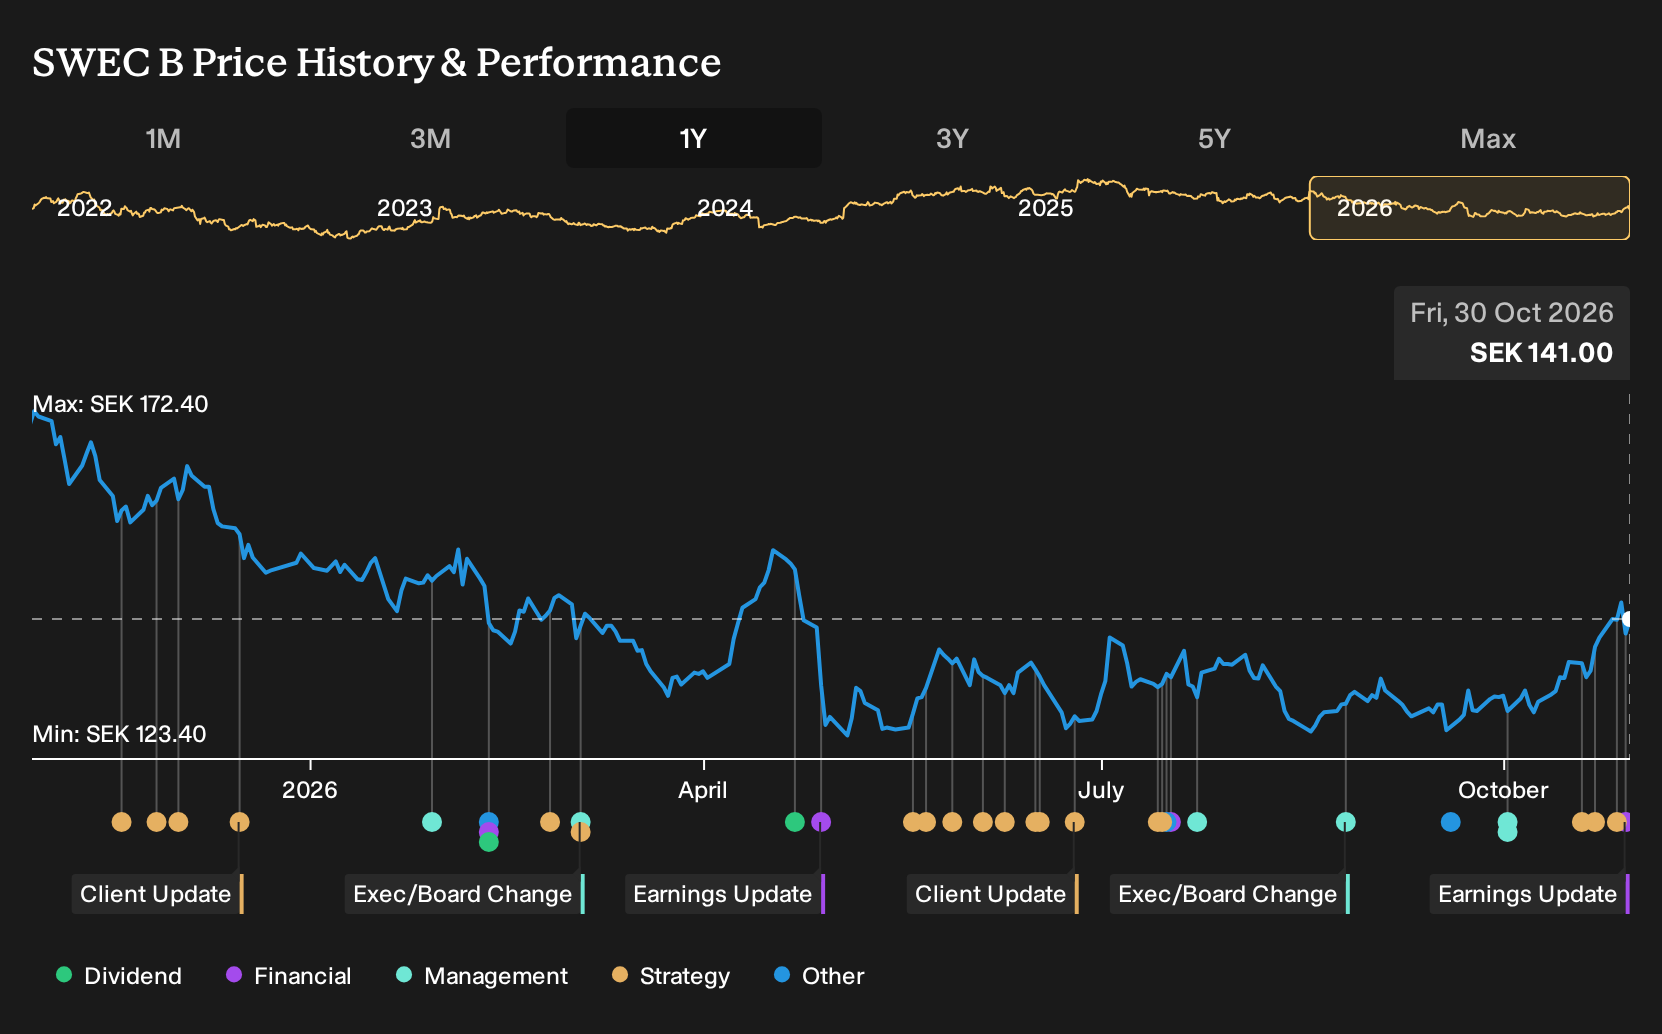
- Sweco reported third quarter 2026 sales of SEK 7,606 million and net income of SEK 521 million, alongside several large multi year consultancy frameworks in energy, transport and security focused property.
- The cluster of long dated agreements with Aalborg Forsyning, GVB and Specialfastigheter points to Sweco deepening its role in complex infrastructure and public security projects that often involve higher technical requirements and intensive project management.
- The next area of attention is how Sweco's stronger earnings and new long term framework agreements could influence the current investment narrative.
Scan how Sweco's mix of infrastructure consultancy and public sector contracts compares with peers by reviewing our curated list of list of solid balance sheet and fundamentals (199 results).
Sweco Investment Narrative Recap
To remain a Sweco shareholder, you need to believe this consultancy can keep lifting earnings through higher value work, better utilisation and disciplined integration of acquired teams. The Q3 2026 report, with SEK 7,606 million in sales and SEK 521 million in net income, supports that margin and efficiency story in the near term.
The key short term swing factor is still project mix and pricing in core infrastructure and public sector assignments, especially as weaker real estate and Finnish operations remain overhangs. Recent results and frameworks help sentiment but do not fully remove the risk that underperforming segments and slower acquisition integration drag on group margins.
The Specialfastigheter frameworks are the clearest operational link to the current catalyst debate. An estimated combined order value of about SEK 500 million in security focused properties ties directly to the narrative of Sweco leaning into technically demanding, higher fee projects that can support billing ratios and earnings quality as work is called off.
These agreements are not guaranteed volumes, which keeps execution risk very real. Actual call offs, staffing and project discipline will determine how much they offset softer demand in residential and commercial real estate or pressure in Finland. For you as an investor, tracking utilisation, EBITA margins and project adjustments around these Swedish public security assignments becomes a practical way to judge whether the thesis is playing out.
Sweco's analyst narrative points to SEK 39.4b in revenue and SEK 3.4b in earnings by 2029, which assumes 6.5% yearly top line growth and an earnings increase of about SEK 1.1b from SEK 2.3b today.
Uncover how Sweco's fair value indicates a 21% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
Some of the most optimistic analysts lean into Sweco's potential in complex energy, water and security projects, expecting about SEK 40.0b in revenue and SEK 3.7b in earnings by 2029. Those figures were set before this Q3 report and new frameworks, so you may see forecasts and storylines shift as fresh data lands.
Explore 2 other Sweco fair value estimates, including one that suggests as much as 33% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider going with your own instincts.
- A great starting point for your Sweco research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sweco. The report includes a comprehensive fundamental analysis summarized in a single visual called the Snowflake, which makes it easy to evaluate Sweco's overall financial health at a glance.
Looking for more investment ideas beyond Sweco?
If Sweco has sharpened your focus on quality and risk, it can help to line it up against a wider field of potential opportunities using the Simply Wall St Screener.
- If you prefer resilient balance sheets and steady fundamentals that can help you sleep at night, then shortlist companies through our 218 resilient stocks with low risk scores.
- If you want potential value on your side rather than paying up for every story, sort for opportunities using the 204 high quality undervalued stocks.
- For investors who care about dependable income alongside fundamentals, scan companies offering strong payouts with the 222 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com